Economy
Türkiye house sales hit year-to-date peak as mortgaged purchases surge

Home sales in Türkiye neared 130,000 units, driven by a sharp rise in mortgage-backed purchases, registering their strongest monthly performance of 2026 and the highest June figure in four years, official data showed on Friday.
According to the Turkish Statistical Institute (TurkStat), total house sales rose almost 16% year-over-year last month to 129,979 units.
Sales of newly built homes climbed 23.1% to 43,406 units, while secondhand home sales rose 12.5% to 86,573 units.
Mortgaged home sales surged 72.1% year-over-year to 25,993 units, accounting for 20% of all transactions and reflecting stronger demand despite elevated borrowing costs.
However, cumulative home sales in the first six months of the year fell 3.1% from the same period of 2025 to 699,516 units. Mortgaged sales increased 32.2% to 142,794.
Separate data from the central bank on Friday showed Türkiye’s nationwide house price index rose 24.5% annually in June, below consumer inflation of just above 32%, indicating a continued decline in real house prices.
Sales to foreign buyers rose 20.1% year-over-year in June to 2,015. They declined 9.2% in the first half of the year to 9,083.
Robust demand
Industry representatives said the June rebound reflected resilient housing demand, although they cautioned that financing conditions remain a key constraint.
“The strongest June performance in the last four years shows that demand for housing remains robust,” said Ziya Yılmaz, chair of the Housing Developers and Investors Association (KONUTDER).
He said some transactions delayed by the Eid al-Adha holiday in May were completed in June, contributing to the strong monthly figures.
Yılmaz also said the increase in firsthand home sales signaled improving demand for new housing, although such sales still accounted for around one-third of the market, well below levels seen before 2020.
He added that the sharp rise in mortgaged sales demonstrated that underlying housing demand and postponed purchases remained strong despite high mortgage rates.
Mustafa Kemal Şahin, head of the Real Estate Marketing and Sales Professionals Association (GAPAS), said the June figures suggested postponed demand was gradually returning to the market.
“The increase in firsthand sales is particularly encouraging because it points to renewed confidence in new housing projects and stronger sales performance by developers,” he said.
Şahin added that high interest rates and limited access to financing weighed on the first-half performance, but described June’s figures as an important sign of market normalization.
Sector representatives said a more sustained recovery would depend on easier access to financing, lower mortgage rates and policies supporting new housing supply, particularly for first-time homebuyers.
Developers also noted that installment plans and interest-free financing offered directly by construction companies have become an increasingly important alternative to bank mortgages.
Home prices extend real decline
Last month, the Central Bank of the Republic of Türkiye (CBRT) held its one-week repo rate steady at 37% for a third consecutive meeting as it monitored the impact of the Iran war.
Supply shocks mainly due to the fallout from the conflict had pushed Türkiye’s headline inflation higher in April and May, but June signaled the return of a downward trend.
The annual inflation eased to 32.1% last month from 32.6% in May. On a monthly basis, consumer prices rose 0.99% in June, slowing from 1.7% in May.
Since the conflict started, the CBRT has halted an easing cycle that began in late 2024 and taken other liquidity steps that pushed the Turkish lira overnight rate up to the 40% limit.
The CBRT raised its end-2026 inflation forecast to 24% from 16% in its quarterly inflation report published in mid-May, saying the short-term inflationary effects of the Iran war would remain “pronounced.” The bank projects inflation falling to 15% at the end of 2027 and 9% at the end of 2028.
Data from the bank on Friday showed the Residential Property Price Index (RPPI) rose nearly 2% month-over-month in June and was up 24.5% from a year earlier in nominal terms.
Adjusted for inflation, however, house prices fell 5.8% year-over-year, marking the seventh consecutive monthly real decline.
After recording a 1.4% annual real increase in January 2024, house prices slipped back into negative territory in February of that year and have remained below inflation ever since, except for a marginal 0.3% real increase in November 2025.
The pace of real declines has accelerated in recent months, widening from 1.4% in December to 6.1% in May. The annual real decrease stood at 2.3% in January, 3.9% in February, 3.4% in March and 4.3% in April.
France and Germany are seeking a new rapid-response trade tool that the European Union would use to position itself better against countries that harm the bloc economically in a new world where trade is increasingly used as a weapon.
German officials said the EU needed a tool as powerful as the Section 301 tariffs imposed by the U.S. or China’s restrictions on exports of critical minerals.
The new measure would not target any specific country, but highlights dumping, widespread subsidies and restriction of currency convertibility – market distortions that many EU leaders say China is engaged in.
A French-German document published on Monday, 10 days before EU leaders discuss Chinese trade imbalances at a summit in Brussels, said “systemic and persistent market distortions” jeopardize the European economy and particularly its industrial base, with widespread job losses.
The bloc, said the document, needs to deploy its trade defense tools more swiftly and efficiently, with more investigations and a broader approach to cover whole sectors.
France and Germany also said the European Commission should propose two new instruments as soon as possible to focus EU efforts on diversification and securing economic security.
The first, which the Commission has already mentioned, would seek to limit companies’ reliance on single sources for certain critical supplies.
The second would limit access to the EU single market for countries that undermine fair market conditions through political or economic means, without specifying what the trigger for EU reaction would be or what action the EU should take.
The paper said that any proposal by the Commission to activate counter-measures against another country should be adopted unless a qualified majority of EU members opposed – a lower hurdle than for some trade measures.
The paper also said the Commission should be able to activate such new measures swiftly, which German government officials said could mean a matter of days.
Legislation to enact a new instrument would still need approval by EU governments and the European Parliament.
A French presidential adviser said it was urgent for the EU to take action, that the imbalances with some trade partners had become unsustainable, and that France and Germany were keen for the bloc to deploy existing anti-dumping measures as soon as possible.
“France and Germany are very keen to put an end to the naivete on trade,” the adviser told reporters.
Brazilian assets were trading higher on Monday after right-wing Senator Flavio Bolsonaro, the son of ex-leader Jair Bolsonaro, came in first in the first round of Sunday’s presidential election.
The Bovespa benchmark stock index gained more than 8% and the country’s currency strengthened against the U.S. dollar following the vote.
The eldest son of former President Jair Bolsonaro won 47% of the votes and will face leftist incumbent President Luiz Inacio Lula da Silva, who secured about 45% of the vote, in a runoff on Oct. 25. Polls had forecast Lula would lead the first round of voting by around three percentage points.
Investors cheered on Monday morning as Bolsonaro’s strong showing was matched by gains for his allies in Congress. Analysts say a friendlier legislature would make it easier for him, if elected, to push through a pro-market agenda of tighter public spending, privatizations and tax cuts.
“Brazil wants change,” Bolsonaro said on Sunday evening, heralding the “end of the era of (Lula’s) Workers’ Party.”
Shares in retailer Magazine Luiza, stock exchange operator B3, lender BTG Pactual, homebuilder Cyrela and conglomerate Cosan jumped more than 20% each, putting them among the top gainers.
J.P. Morgan upgraded Brazil’s equities to “overweight” on Monday, saying a more favorable political backdrop after recent election developments had improved the outlook for the region’s largest market and could drive a period of outperformance.
Brazil’s real currency strengthened more than 4% against the U.S. dollar in early trading, moving below 5.00 per greenback, from around 5.22 previously, in line with analyst forecasts and with the currency’s performance four years ago when then-President Jair Bolsonaro did better than expected in the first-round vote against Lula.
The elder Bolsonaro went on to lose to Lula in the second round of that election and was subsequently convicted of trying to carry out a coup to overturn the result. The former president was sentenced to about 27 years in prison and is currently under house arrest.
Brazil’s international debt also rallied on Monday, while broader fixed-income markets were jittery. The 2056 bond was up 1.4 cents on the dollar to bid at 93.5 cents, Tradeweb data showed.
‘The market wants change’
Bolsonaro has pitched himself as a “more centered” version of his father to investors concerned about Brazil’s burgeoning fiscal pressures.
“It remains to be seen whether the senator would ultimately prove more fiscally responsible than Lula would be in a fourth non-consecutive presidential term. However, markets are likely to give him the benefit of the doubt,” said Thierry Larose, portfolio manager at Vontobel.
If he is elected, Bolsonaro would enjoy some room to maneuver with Congress after his Liberal Party emerged as the biggest winner in congressional races on Sunday.
Bolsonaro’s party increased its representation in the Senate from 15 to 28 seats, the strongest result for a party since Brazil’s return to democracy in 1985. It also is projected to secure 121 seats in the lower house, up from its current 98 seats.
“The likelihood of advancing reforms is much greater,” said Pedro Paulo Silveira, an analyst at Terra Investimentos. He noted that during the previous Bolsonaro government, reforms often depended on costly political bargaining or stalled altogether.
Analysts also expect the real to continue strengthening into 2027. Societe Generale forecast that it would move to 5.10 by the end of 2026, with scope to move below 5.00 in the first half of 2027. Morgan Stanley forecast the real could strengthen past 4.90 and toward 4.50 in the first quarter of next year.
“The market wants change, it wants reform; it doesn’t want a high public deficit; with the current government, all of this will continue,” said Pedro Galdi, investment analyst at the AGF Investments platform.
Bolsonaro’s strong showing is likely to boost market confidence in the near term, said Bryan Harris, a managing partner at Sabio.
“The market will be looking for clear signals from Bolsonaro that he is serious about tackling the country’s problems,” Harris said.
Heading into Sunday’s vote, most private polls, which largely underestimated the younger Bolsonaro’s strength, had shown the 45-year-old senator and Lula, who will turn 81 later this month, about even in a runoff vote.
Addressing a crowd at a hotel in Sao Paulo, Lula said he had been convinced he would win the election in the first round.
“Starting tomorrow, we begin a new campaign,” the leftist leader said, promising to show voters what he had accomplished as president.
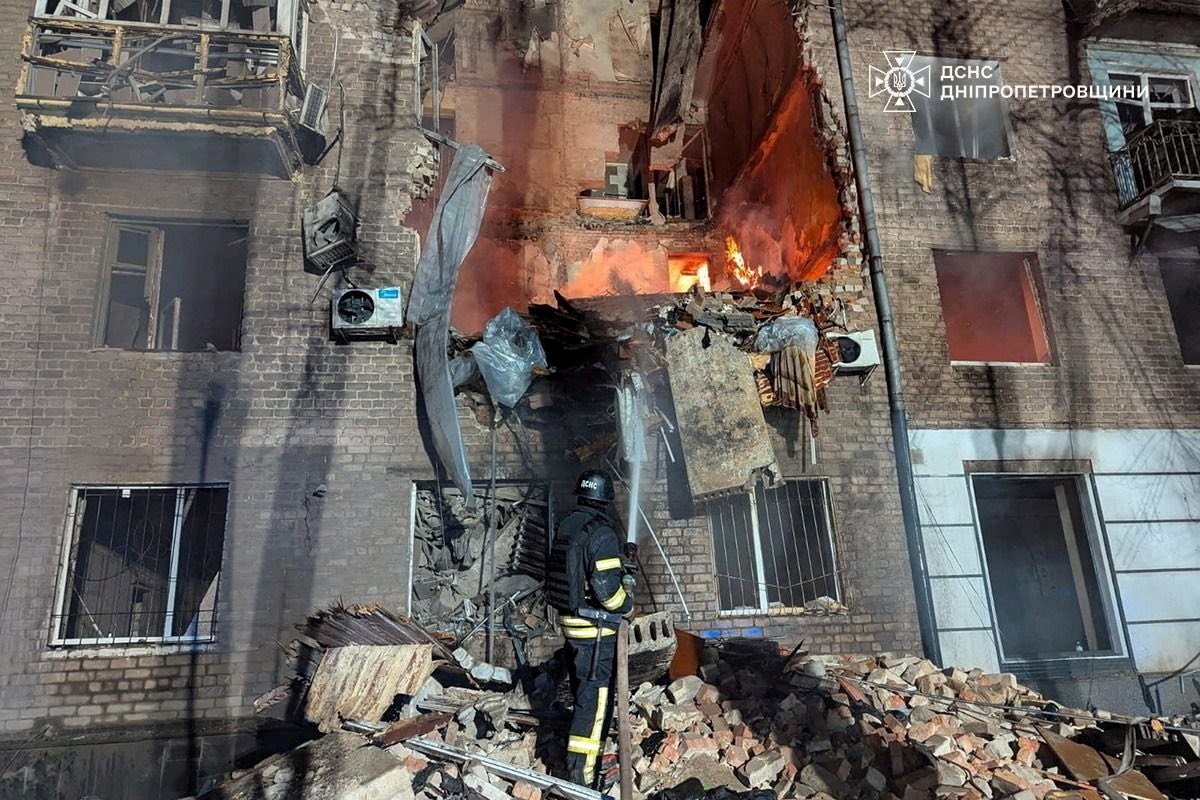
Kryvyi Rih, the hometown of Ukrainian President Volodymyr Zelenskyy, is struggling to survive. Russian airstrikes have brought the city’s huge steel plant and mines to a standstill, dragging the local economy to its knees.
Mayor Oleksandr Vilkul said the sprawling industrial city – which stretches along the banks of the Inhulets River – was doing everything possible to ensure its hospitals remain open, the lights remain on in kindergartens and schools, and buses keep running.
“In Kryvyi Rih, the situation is actually worse than anywhere else, apart from the front line itself,” Vilkul, 52, a former mining executive, said in a video address.
The financial squeeze on the city of about 600,000 people underlines the challenges facing Ukraine as the government navigates its biggest budget crisis since Russia’s full-scale invasion in 2022.
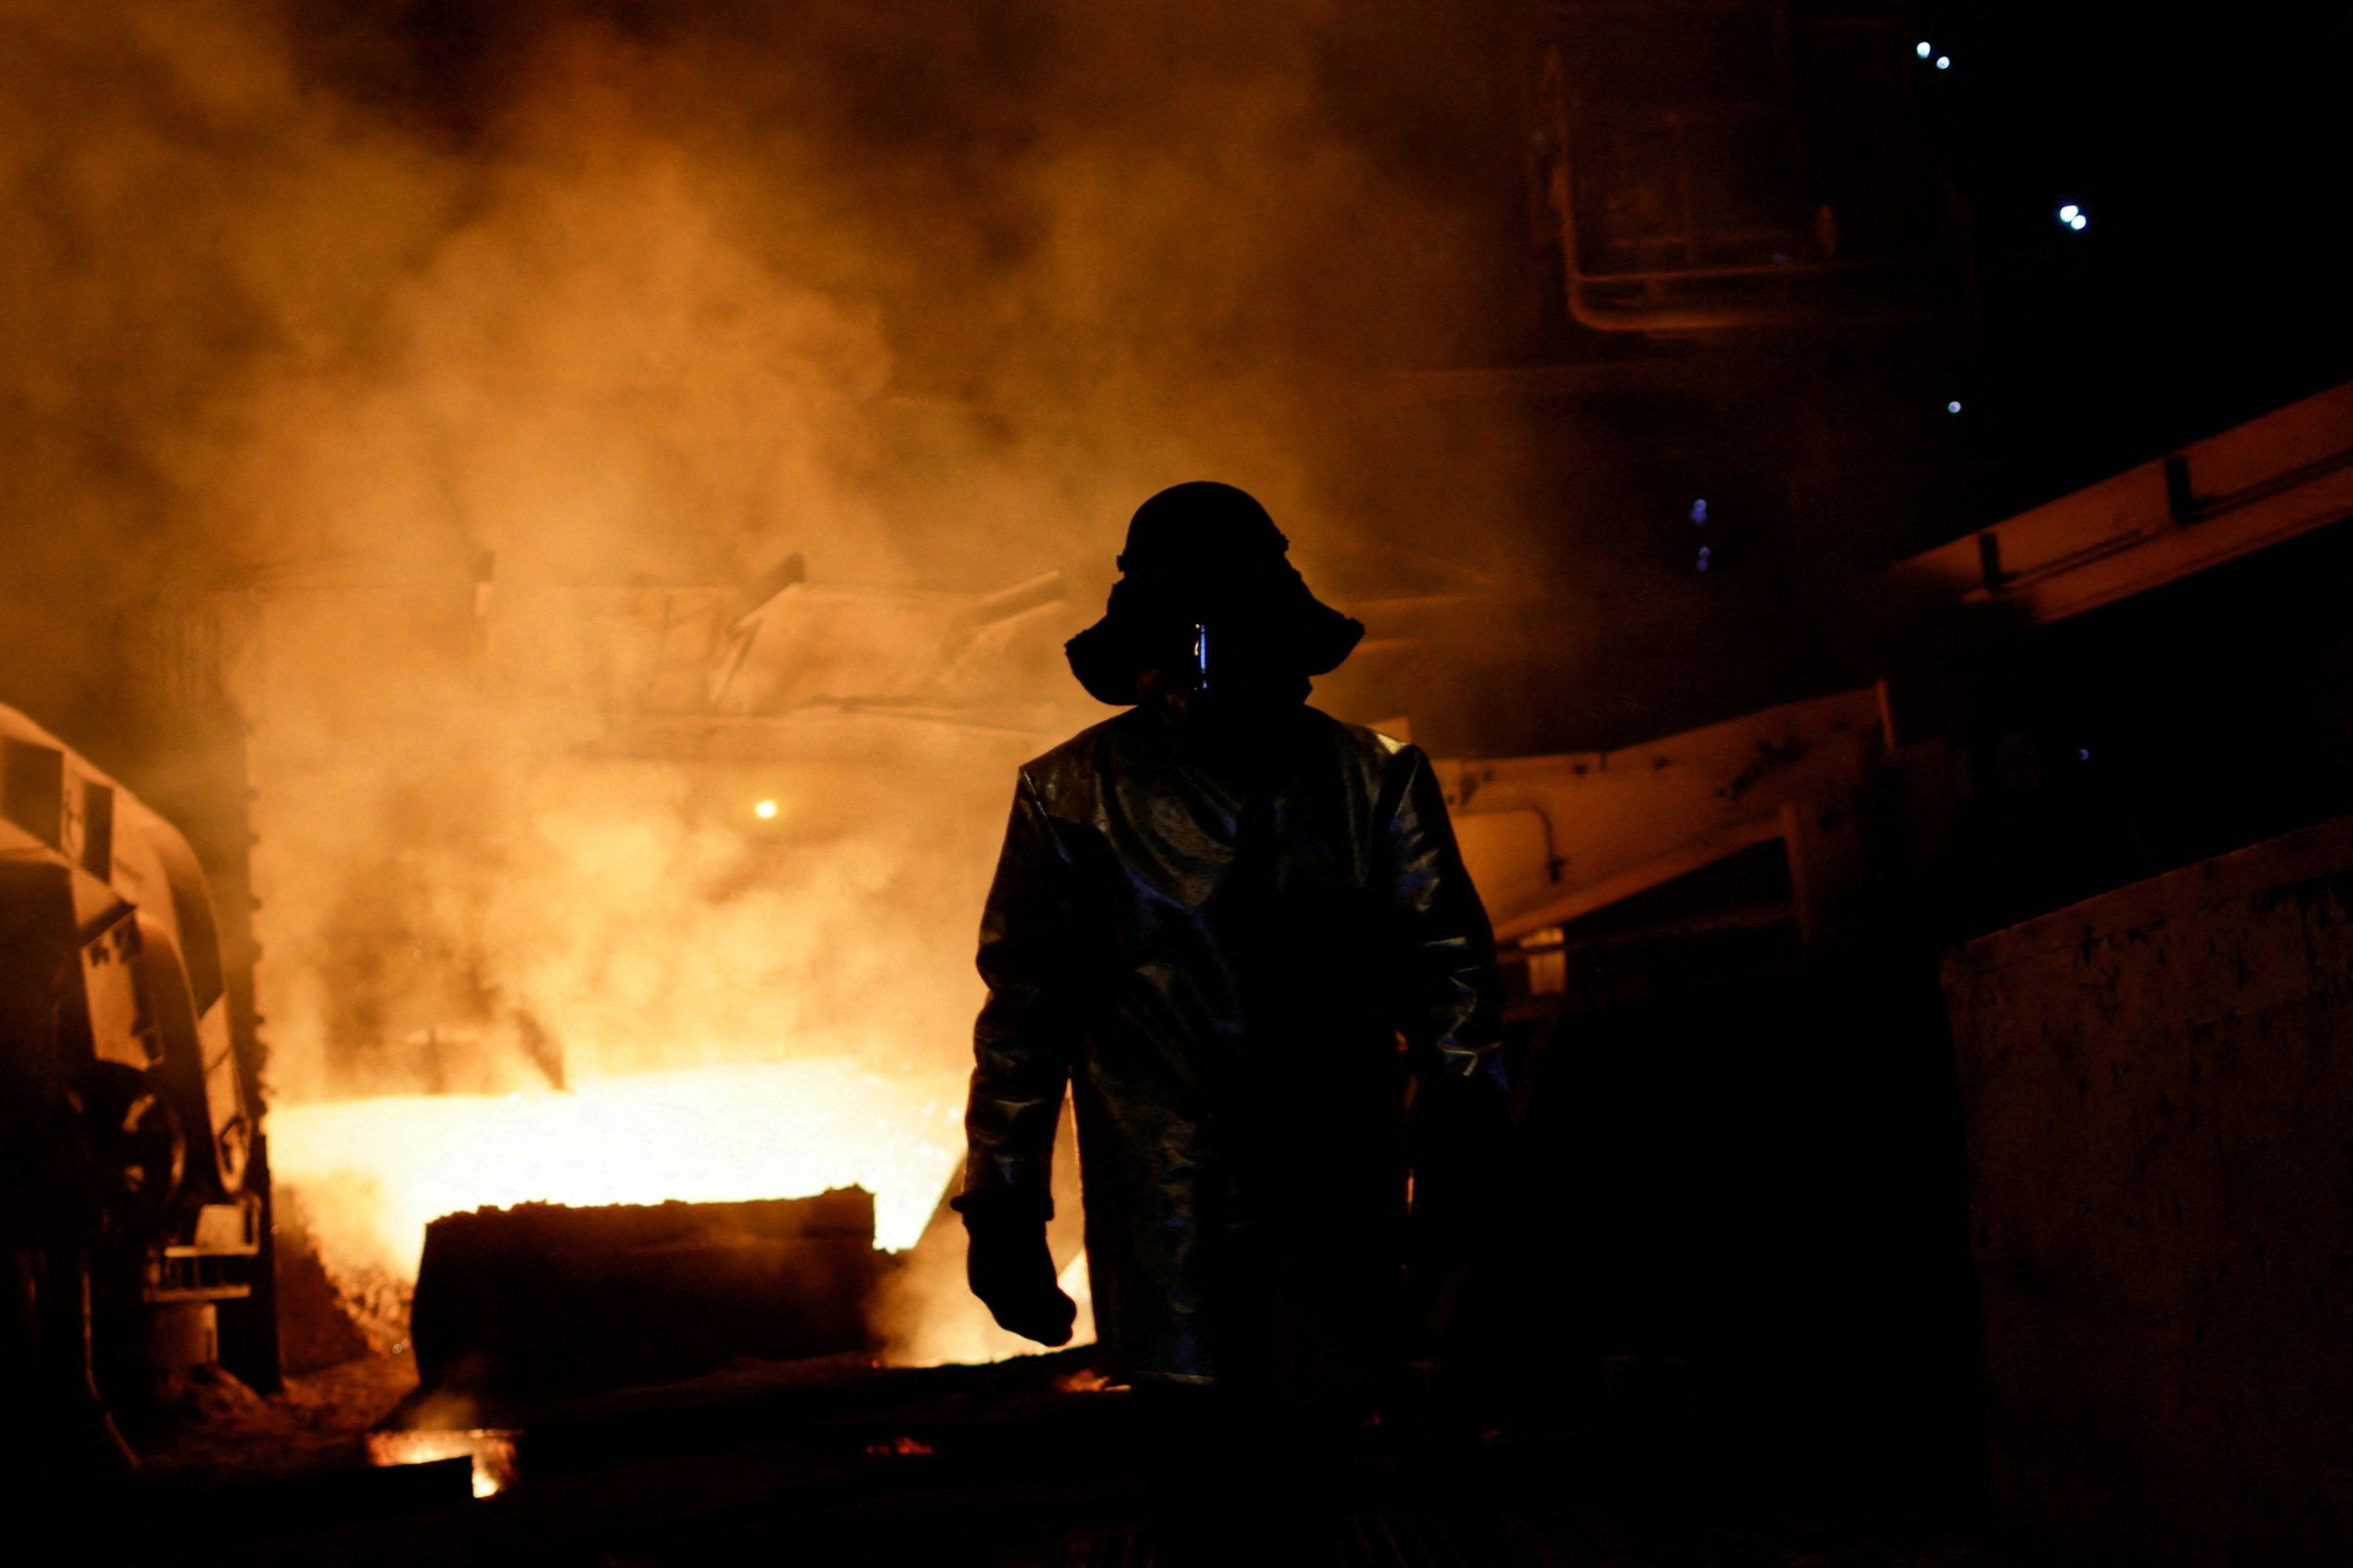
Last month, the city’s largest employer – ArcelorMittal’s hulking mining and steelmaking complex – suspended its operations following a series of Russian ballistic missile strikes that darkened its furnaces.
The prospects for next year, Vilkul said, are bleak.
“It’s about survival. Right now, we need to survive,” he said.
It’s a scene played out across Ukraine’s once-mighty steel industry, which accounted for a tenth of economic output before the war. Giant mills in Zaporizhzhia in the southeast and other industrial cities stand silent and exports have stopped.
An escalation in Russia’s drone and missile strikes this summer destroyed factories and warehouses across Ukraine, damaged ports and railways, and forced shops and businesses to close, slowing the growth of the economy and tax revenue.
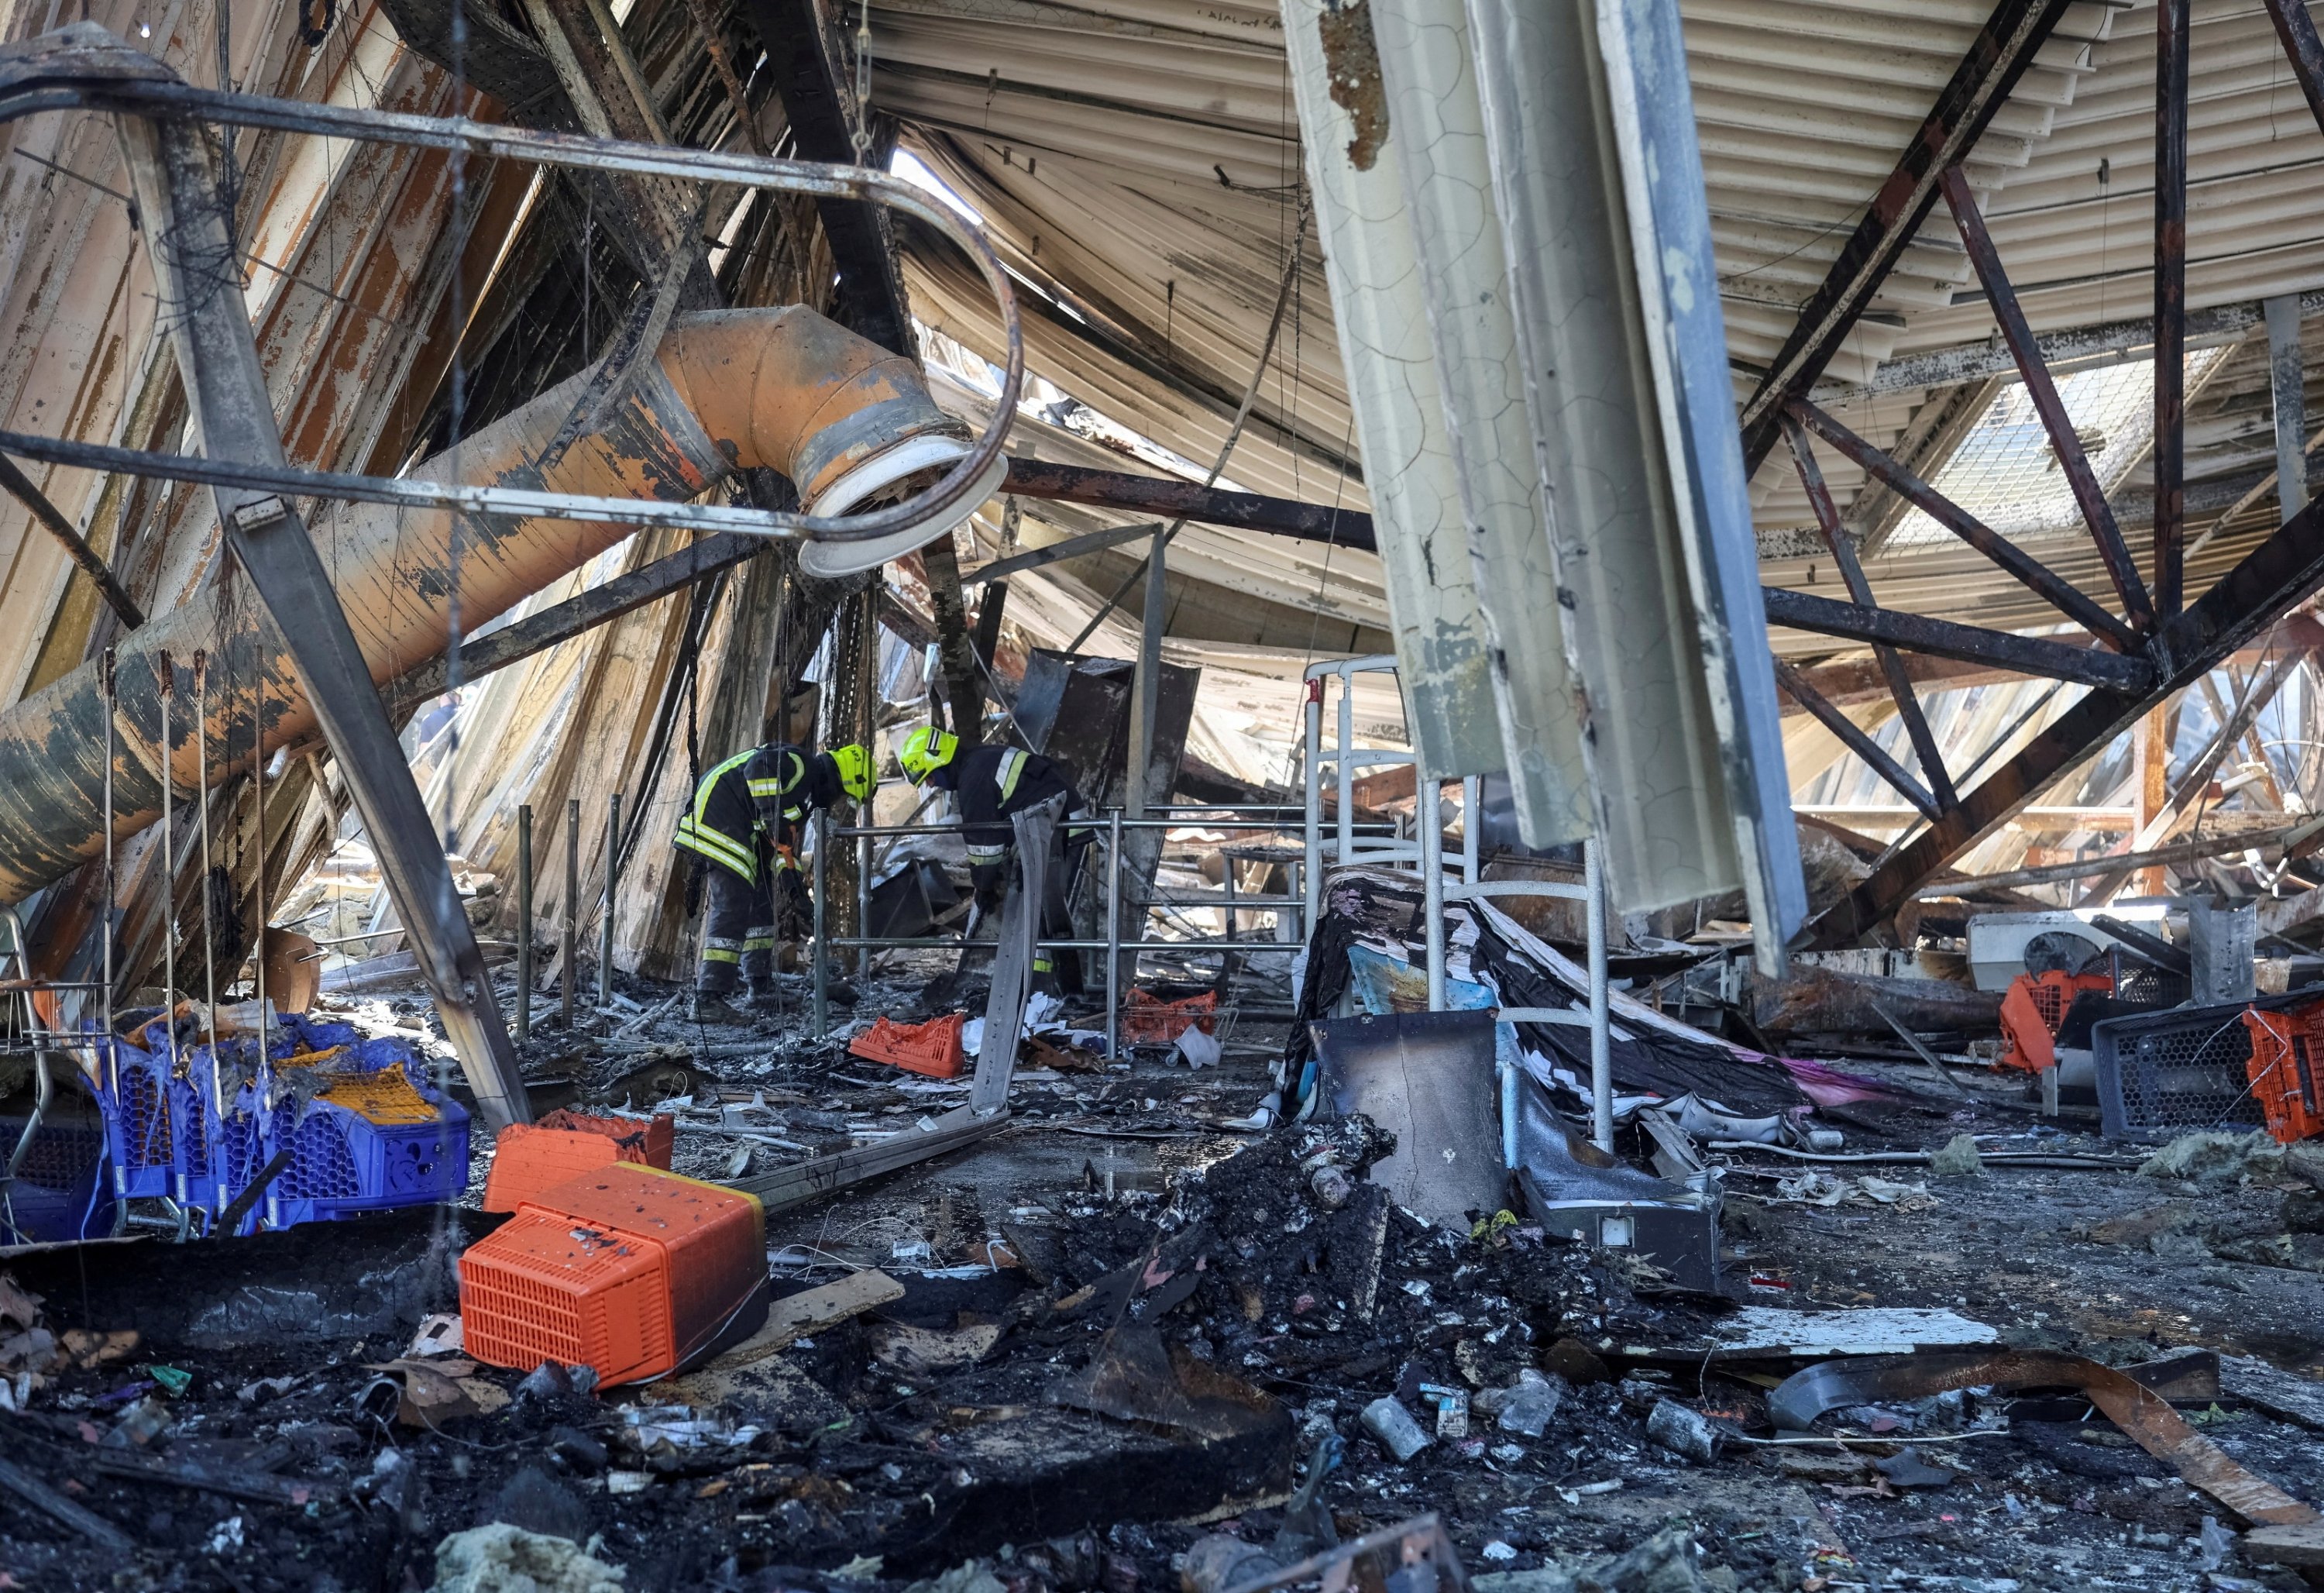
Meanwhile, the technology-driven war is becoming ever more expensive for Ukraine to fight.
Billions of euros in foreign loans have been delayed by failure to pass bills including unpopular tax reforms and anti-corruption legislation demanded by Ukraine’s Western allies, leaving a gaping hole in state coffers.
Ukraine needs $56 billion to fund that gap this year – equivalent to about a quarter of its economic output. Of that, $27 billion is military spending.
To bridge the shortfall, Ukrainian officials met European partners in Brussels last week to discuss bringing forward disbursements due next year under a 90-billion-euro ($101-billion) EU loan. The European Commission and Ukraine said they had identified funds to close the gap this year.
But three sources familiar with the talks said accelerating these payments risked increasing budget pressure next year – at a time when looming election campaigns in European allies including France and Poland could erode support for Kyiv.
Prime Minister Sergii Koretskyi acknowledges the situation is “challenging.” The government has been forced to freeze nonessential spending – including reconstruction of damaged buildings and infrastructure – to prioritize military spending, public sector wages and pensions.
“All resources should be channeled into critically important areas,” Koretskyi told reporters.
War costs soar, domestic revenues fall
Two years ago, a single day of fighting cost Ukraine $140 million, but that figure has jumped to $190 million, according to Roksolana Pidlasa, the head of parliament’s budget committee. And that does not include direct military support to Kyiv from its Western allies.
Rising costs are driven partly by the need for expensive medium- and long-range weapons capable of striking Russia’s oil refineries and military factories to reduce Moscow’s ability to continue its war.
Plus, the wage bill for an expanded army is higher than ever before, and the state must support a growing number of military families of disabled or deceased soldiers.
“Expenditure will continue to rise,” Pidlasa told a conference in Kyiv. “This is one more pragmatic reason why the U.S. and Europe need to act faster to force (Russia) to end this war.”
In the first nine months of this year, Ukraine spent more than $44 billion on defense alone, data showed. That does not include in-kind military support from allies.
In the same period, the government was able to raise only about $42 billion in tax revenue as the economy slowed.
Pidlasa said that in the first nine months of this year, Ukraine’s budget lost over 49.5 billion hryvnias ($1.1 billion) in tax revenue because of Russian attacks that not only damaged property and goods, but disrupted logistics and shut shops and businesses for hours at a time.
By the end of the year, the cumulative losses could rise to 70 billion hryvnias, the government estimates.
“We have not a temporary but a structural problem with the revenues at the very time when spending really requires resources,” said Oleksandra Myronenko, an economist at the Center for Economic Strategies, a Kyiv-based think tank.
Some Ukrainian businesses have started to scale back operations. Others have put capital expenditure on hold as the country braces for a difficult winter. Business sentiment and economic expectations are darkening.
Vasyl Khmelnytskyi, founder of an industrial park in the city of Bila Tserkva near Kyiv, said he had scrapped plans to build three new factories.
“The risks are simply too great right now – both for the business and for the people,” he said in a Facebook post.
Ukraine’s agricultural sector – its largest source of export revenues – has been particularly hard hit. Russian attacks on Ukraine’s Black Sea ports led to a 36.6% fall in grain exports year-over-year in September.
About $40 billion in export revenue is at risk this year as a result of the blockade, Economy Minister Oleksandr Kravchenko said.
Even with tens of billions of euros in foreign support, Ukraine’s economy is expected to grow only between 0.5% and 1.5% this year, economists say – down from 1.8% in 2025.
Foreign aid is delayed
During more than four years of intense fighting, Ukraine has been able to maintain macroeconomic and financial stability thanks to fiscal support from its Western partners, receiving nearly $200 billion since Russia’s invasion.
But $29.5 billion in foreign aid is now at risk this year because of delays in passing reforms, Koretskyi said. The government has postponed about $900 million of capital spending until December, in the hope the legislation will be passed.
The aim is to pass all the required legislation in parliament by Oct. 15, Koretskyi said.
“Only then we will get all the money,” Koretskyi said. “This is absolutely vital. It needs to be done as soon as possible.”
Legislators are now discussing the budget for next year. The government has proposed record defense budget spending of $110 billion. This figure does not include direct military aid.
Finance Minister Sergii Marchenko has estimated that the unfunded budget gap for the next year is already more than $32 billion.
Part of the solution, Marchenko said, is to use frozen Russian assets in Europe to fund Ukraine’s budget. EU countries immobilized some 210 billion euros of Russian central bank assets after Moscow invaded Ukraine.
“Ukraine continues to mobilize domestic resources, but the scale of Russia’s war puts clear limits on our capacity,” Marchenko said on the social media platform X.
Oil exports from the Middle East surpassed pre-war volumes for about half of September, shipping data showed Monday, though attacks on tankers and logistical constraints cloud the outlook for sustained higher flows.
Ships transiting the Strait of Hormuz face a “heightened and increasingly unpredictable kinetic threat” given the recent sharp increase in traffic, Marisks, a shipping intelligence service, said Saturday.
The seven-day moving average for crude exports from the region was 18.3 million barrels per day on Sept. 30, provisional Kpler data showed, with cargoes topping pre-war levels on 14 days in September.
That included Gulf oil sent through Hormuz, via the Red Sea, and from terminals and ship-to-ship transfers in the Gulf of Oman.
Shipments had earlier matched or exceeded pre-war levels on a handful of days in June and July, Kpler data showed, after Washington and Tehran reached a memorandum of understanding that has since lapsed.
“Forty percent now bypass Hormuz, and most crude crossing the strait changes tankers offshore,” Kpler said, adding that most of the oil flowed through Saudi and United Arab Emirates (UAE) pipelines.
These figures include flows via the Red Sea, a route increasingly used to bypass the blockade Iran is attempting to impose on Hormuz – where around a fifth of the world’s petroleum supplies crossed before the conflict.
Iran still claims control over the strait, and ships without its authorization risk coming under attack, but more and more are making it out, and alternative routes meant to bypass the waterway are operating at full capacity.
Saudi Arabia drives surge
Crude exports from the region averaged about 18 million bpd in the 12 months before the start of the U.S.-Israeli war with Iran, according to Kpler.
The recent export surge has been driven by Saudi Arabia loading from both the Red Sea and the Gulf, three weeks after a Sept. 10 attack on its East-West pipeline, Kpler said.
It has required more supertankers to shuttle crude through Hormuz, trade sources and analysts have said, adding that ship-to-ship transfers in the Gulf of Oman have reached their limits.
Iraq’s state-owned Oil Tanker Company and some refiners have chartered tankers to load Basrah crude inside the strait after Baghdad secured Iranian permission for Iraqi oil tankers to pass through Hormuz.
Shipping data provider Vortexa also said Gulf flows have recovered. It said that the 14-day moving average for Middle East crude and condensate exports hit 18.6 million bpd, exceeding the 10-year seasonal average and returning to pre-conflict levels.
“Most of this month-over-month increase seen in September comes from Saudi Arabia, which is ramping up exports to regain market share from other Middle Eastern countries,” senior market analyst Xavier Tang said.
“This increase in Middle East supplies will also help alleviate tightness in the oil market, especially for Asian refiners,” he said.
Liquefied natural gas cargoes exiting the Strait of Hormuz also rose in September to their highest since February.
Ship attacks
However, attacks on tankers continued, with at least seven incidents reported in the past week, Marisks said.
The very large crude carrier (VLCC) Kazimah III was reportedly struck on Oct. 1 by an unknown projectile while in the strait, causing a fire onboard, it added. Its owner, Kuwait Oil Tanker Company, did not respond to a request for comment.
Separately, the Liberian-flagged Aframax tanker Lipsi was reportedly struck by an unknown projectile on Oct. 4 while transiting approximately 3.9 nautical miles northeast of Jazirat Um Al Fayarin, Oman, in the Strait of Hormuz, damaging its engine room, Marisks said Monday. Dynacom, its manager, did not immediately respond to a request for comment.
The crew aboard both tankers were reported safe, with no casualties reported, Marisks said.
The United Kingdom Maritime Trade Operations agency has reported at least one attack a day in the Strait of Hormuz or the Gulf of Aden since Oct. 2.
“Current intelligence suggests that the recent pattern of incidents may not necessarily represent deliberate targeting of individually selected merchant vessels,” Marisks said.
“Instead, available information indicates the possibility that Iranian forces are launching missiles into a predetermined engagement area or ‘kill box,’ with weapons potentially acquiring and locking onto available radar signatures within that area.”
Before the Iran war started on Feb. 28, the strait typically handled about 125 large commercial vessels per day, including tankers, gas carriers, bulkers and container vessels, accounting for some 20% of global crude and LNG supply.
Türkiye’s third-biggest state-owned bank has begun an investor roadshow for a secondary share sale, its top executive said Monday, moving forward despite turmoil in the local investment fund market amid strong investor interest.
Halkbank General Manager Süleyman Özdil said he did not expect the crisis to have a negative impact on the offering, adding that the lender had met with nearly 60 investors in Abu Dhabi, Dubai, London and New York and seen strong interest.
“There is no change to the planned share offering. We will launch at the earliest opportunity, subject to market conditions,” Özdil told an interview with Reuters. He did not comment on the possible size of the offering or exact dates.
Halkbank said in August that it had applied to Türkiye’s Capital Markets Board (SPK) for a secondary public offering raising its nominal capital by TL 1.8 billion to TL 9 billion, two months after the dismissal of a U.S. case launched in 2019 alleging it had evaded sanctions on Iran.
Halkbank said after the dismissal that it expected its position in international markets to strengthen and its access to overseas funding to improve.
At current market prices, Halkbank’s planned offering would raise around $1.7 billion, according to Reuters calculations.
No impact expected from fund turmoil
Asked whether investors were concerned about the fund crisis, he said investors believed the market would emerge healthier from the turmoil.
“They think the banking sector is healthy and valuations are cheap. They see the banking sector as the first place to look for investors seeking exposure to Türkiye,” he said.
Türkiye’s main share index entered a bear market and posted its worst monthly performance since 2008 in September after a sell-off that was triggered by the fund turmoil.
Regulators last month ordered the liquidation of 131 investment funds managed by seven asset managers following warnings by some that they could not meet redemption payments.
Authorities have widened their investigation into suspected market manipulation in stocks and fund markets.
Halkbank’s IPO in 2012, raising around $2.5 billion, is still the biggest public offering in Türkiye.
The Türkiye Wealth Fund owns 91.5% of Halkbank, which has paid-in capital of TL 7.18 billion. The remaining 8.5% is publicly traded.
The benefits of artificial intelligence justify accepting some risks, OpenAI Chief Executive Sam Altman said, arguing the technology should remain broadly accessible to the public.
“We believe that the world should accept some bad things happening for the benefits of this technology and people having the agency,” Altman said in an interview with Politico’s technology-focused newsletter Decoded.
Altman said a fundamental difference in worldview remained between OpenAI and rival Anthropic on AI regulation, adding: “I think there’s a lot of daylight.”
“I disagree, but I understand the perspective of people who are like, ‘This technology is going to get so powerful, and it’s so dangerous, that a single lab in San Francisco should have it and make sure nothing bad happens, and kind of figure out how to dole out the benefits,'” Altman said.
He called that “a completely unacceptable trade-off” that runs counter to the “lighter-touch regulatory stance” backed by OpenAI.
“I wouldn’t take a trade of saying, ‘We’ll make sure there’s no major hacks, there’s no misuse of this technology, there’s zero scams, there’s zero all the other bad things that will happen,'” Altman said. “Because I think people will do tremendously – orders of magnitude more – good stuff than bad stuff.”
Altman’s remarks come amid a growing debate within the AI industry over the pace of development and the risks posed by increasingly capable systems.
Anthropic CEO Dario Amodei in September published an essay calling on the industry to slow down to “pace the frontier,” a stance that Altman publicly endorsed. Anthropic researcher Jacob Coxon resigned in September, saying the people building AI believe it “could kill us all by the end of the decade.”
Reuters reported in September that Anthropic warned that, despite AI’s potential benefits, the technology can sometimes act in ways that run counter to its makers’ intentions and penetrate other companies’ systems.
The company said advanced models could exhibit “self-preserving behaviors,” including attempts to “resist shutdown,” “conceal or manipulate information,” or generate outputs that could be interpreted as “coercive, deceptive, or manipulative.”
However, U.S. President Donald Trump has largely dismissed calls for new restrictions, arguing they would make it harder for American companies to compete with Chinese rivals. He has repeatedly said existing law enforcement agencies, including the Justice Department, provide sufficient safeguards and that no new rules are needed.


-
 Economy1 day ago
Revolut: $115 billion fintech taking on Europe’s biggest banks
-
 Politics3 days ago
Türkiye vows continued co-op with Iraq after troop withdrawal
-
 Politics3 days ago
Turkish officials urge end to attacks after Medina power station hit
-
 Economy3 days ago
Teknofest Southeast combines technology, local culture in Şanlıurfa
-
 Politics3 days ago
Sumud Flotilla repairs ships in Türkiye for new Gaza voyage
-
 Economy2 days ago
Egypt’s Sisi calls for peaceful solutions to Africa’s conflicts
-
 Economy3 days ago
Fund probe not weighing on Türkiye credit rating, S&P Global says
-
 Economy3 days ago
Canada’s PM Carney plans Türkiye visit for talks with President Erdoğan