Economy
EU approves US tariff pact ahead of Trump deadline

EU states gave their final approval Thursday to a year-old tariff deal with the United States, allowing it to enter into force ahead of a July 4 deadline set by U.S. President Donald Trump.
Struck between Trump and EU chief Ursula von der Leyen in July 2025, the deal sets levies of %15 on most of EU exports to the U.S., and zero tariffs for U.S. industrial goods coming into the 27-nation bloc.
But the EU had yet to fulfil its side of the accord – after Trump’s threats to Greenland and a U.S. Supreme Court decision striking down many of his tariffs fuelled months of delay.
The sign-off by member states – who had already agreed the deal in substance – clears the final legislative hurdle on the EU side, following parliament’s approval earlier this month.
The deal’s approval “confirms the EU’s commitment to a stable, predictable and mutually beneficial transatlantic trade relationship, while preserving the necessary guardrails to protect European economic interests,” an EU statement said.
Lawmakers added a series of safeguards, including giving the European Commission power to suspend the pact if the U.S. side fails to meet its commitments or acts to disrupt trade and investment.
Parliament also introduced an expiration date of end-2029, unless the agreement is renewed by then.
“Openness must go hand in hand with safeguarding our interests,” said Michael Damianos, the commerce minister for the Greek Cypriot administration which holds the EU’s rotating presidency.
“These measures achieve both, supporting stable and predictable trade flows with the U.S. while ensuring the EU can respond swiftly and proportionately when the deal is not respected or its interests are at stake,” he said.
The two texts enacting the EU side of the accord – removing duties on U.S. industrial goods and introducing preferential access for certain seafood and farm products – will formally take effect a day after publication in the EU’s official journal.
Türkiye plans to transform the Development Road project into a multi-billion-dollar link carrying oil, natural gas and electricity from Iraq and the Gulf to Europe, according to Energy and Natural Resources Minister Alparslan Bayraktar.
Bayraktar, who met with Iraqi Oil Minister Basim Mohammed Khudair in Ankara on Friday, said Türkiye aims to turn the Development Road into a strategic “energy corridor.”
Unveiled in May 2023, the project is a $20 billion regional infrastructure initiative designed to facilitate the transport of goods from the Gulf to Europe via the Grand Faw Port in Basra in southern Iraq. The port would be linked to Türkiye and subsequently to Europe through an extensive network of railways and highways.
In April 2024, Türkiye, Iraq, the UAE and Qatar signed a memorandum of understanding (MoU) for joint cooperation on the project.
Bayraktar said oil and natural gas transported along the route could alone generate an annual economic value of around $80 billion if the project’s energy infrastructure is developed alongside its transportation network.
“We are determined to build the Development Road as a strategic ‘energy corridor,'” he told Anadolu Agency (AA), noting that developing the energy infrastructure alongside the route will greatly boost its economic value.
Bayraktar said Iraq’s oil resources offered significant potential for the project’s energy dimension and that the route could eventually carry up to 2.5 million barrels of oil per day (bpd).
Iraq currently produces around 4 million bpd, while Kuwait has a production capacity of around 2 million bpd.
Qatari gas could be transported through Iraq
Bayraktar said the Development Road also had significant potential for natural gas transportation, particularly by providing an alternative route for Qatar’s gas exports to Europe.
Qatar, one of the world’s largest gas exporters, currently ships most of its gas as liquefied natural gas (LNG).
Bayraktar said Qatar’s LNG exports rely heavily on the Strait of Hormuz and that transforming the Development Road could provide an alternative route for some of the country’s gas.
He said the initiative could therefore evolve from a project aimed at strengthening trade and transportation links between Iraq and Türkiye into a multidimensional corridor encompassing oil, natural gas and electricity infrastructure.
Ceyhan could become global energy hub
Bayraktar said alternative routes to the Strait of Hormuz had become increasingly important at a time when energy security and supply diversification were gaining greater significance.
Extending the Kirkuk-Ceyhan pipeline, the current infrastructure connecting Iraqi oil to Türkiye’s Mediterranean export terminal at Ceyhan, to Basra and increasing its capacity could provide a strong alternative to the Gulf region and the Strait of Hormuz for oil transportation, Bayraktar stated.
Türkiye also aims for its state-owned Turkish Petroleum Corporation (TPAO) to play a more active role not only in the Kirkuk fields but also in other oil fields in Iraq, Bayraktar said.
“We will continue to strongly pursue concrete projects in close cooperation with the new Iraqi government,” he said.
“We aim to reach the target of supplying 1 million barrels of crude oil, increase trade and turn Ceyhan into a global energy hub,” Bayraktar said.
President Recep Tayyip Erdoğan said Monday that Türkiye had never allowed itself to fall behind in the space race, stressing that space should not be the preserve of a handful of powerful nations.
“The space race cannot be a competition between just a few countries,” Erdoğan told the International Astronautical Congress in the southern city of Antalya.
It is the first time Türkiye is hosting the event that brings together scientists and delegates from 111 countries.
Erdoğan set out what he called Türkiye’s principle on space: that it should not be treated as a prize for whoever gets there first.
“Militarizing space and turning it into a vehicle for an arms race would be utterly wrong,” he noted.
Erdoğan said Türkiye is now one of the few countries able to design, develop, build, test and operate its own satellites in orbit.
He pointed to the IMECE satellite, which he said gave Türkiye an important high-resolution Earth observation capability, and to the Göktürk satellites, which he said had expanded its ability to observe and survey from space.
Türkiye has also launched the Türksat 5A and 5B communications satellites. In 2024, it launched and put into service Türksat 6A, its first domestically designed and built communications satellite.
Erdoğan said that satellite had confirmed the country’s engineering capability, industrial base, human resources and confidence in space technology.
Space, he said, is not only about satellites.
In 2024, Türkiye sent Alper Gezeravcı to the International Space Station on the country’s first crewed space mission.
A suborbital research flight by Tuva Cihangir Atasever followed, giving Türkiye experience in microgravity research.
Erdoğan called these steps meaningful but not sufficient, and said Türkiye was pursuing bigger goals.
Moon program
Erdoğan said one of the most ambitious goals of the National Space Program, announced in 2021, is a mission to the Moon.
He said Türkiye had set that goal five years ago and had since turned it into a concrete program.
“We have completed the production, assembly, and integration of the lunar rover we developed as part of our Moon Research Program,” Erdoğan said. He said the spacecraft was now undergoing system-level environmental tests.
The vehicle weighs about 3.5 metric tons and has a domestic content rate of more than 80%, which he called a source of great pride.
He added that experience gained on projects such as IMECE and Türksat 6A was being carried over to the lunar mission, so that Türkiye did not have to start from scratch each time.
Spaceport in Somalia
Erdoğan said that having satellites was not enough to be a space power and that access to space was also essential.
He said Türkiye had given priority to launch access and a spaceport in its space program and had begun construction of a spaceport in Somalia. He said the project would strengthen Türkiye’s access to space and help develop the space ecosystem of the African continent.
The euro plunged to its lowest level against the dollar in 17 months on Monday amid growing concerns about France’s high debt and deficits and political future, which have sent its government bond yields higher.
An underwhelming 2027 budget plan unveiled last week fanned concerns that government spending will remain high ahead of next year’s presidential elections, in which the far-right Marine Le Pen, seen as a fiscal populist, stands a chance of winning.
That has rattled bond investors at a time when interest rates – and hence borrowing costs – are rising in developed economies worldwide to combat inflation.
French debt is projected to rise to nearly 122% of the country’s gross domestic product (GDP) next year, despite billions of euros in planned spending cuts.
That has sent its 10-year government bond yield to 4.8%, the highest since the 2011 eurozone bond crisis.
“The fact that French bonds and the euro sold off last week, and the downward momentum could persist this week, is a sign that Europe is out of favor with investors and bond market vigilantes are watching developments in the eurozone closely,” said Kathleen Brooks, research director at XTB.
A call for snap elections in Spain by Prime Minister Pedro Sanchez also surprised investors, after lawmakers rejected a hotly debated housing relief bill from his Socialist-led minority government.
“France had already been under pressure due to questions over fiscal credibility and political stability,” said Patrick Munnelly, market strategist at Tickmill Group.
“Spain now adds another layer of uncertainty,” he added. “Europe’s political risk is weighing on the euro.”
Stocks, meanwhile, were broadly higher, with the Nasdaq opening higher after hitting another all-time high on Friday in the wake of weak U.S. jobs data, and the broader Dow also still near record territory.
That tempered expectations of an imminent rate hike by the Federal Reserve (Fed), and fueled optimism on Asian and European equity markets that the AI-fuelled rally still has room to run.
Paris was dragged lower, however, by Schneider Electric after the industry group unveiled a $22.6 billion all-cash deal to buy the U.S. engineering software specialist PTC, which pulled its share price down nearly 10%.
Lower oil prices provided additional support, after G-7 countries, in coordination with the International Energy Agency (IEA), agreed on Friday to immediately release 100 million barrels of diesel and crude oil to ease supply concerns caused by the U.S.-Iran war.
Exports of Middle East oil, excluding Iran, surpassed their pre-war levels last week despite attacks on ships in the Strait of Hormuz, according to data from the maritime tracking firm Kpler.
But Saudi Aramco chief executive Amin Nasser on Monday described oil stockpiles as “scarily thin” as the European winter looms.
France and Germany are seeking a new rapid-response trade tool that the European Union would use to position itself better against countries that harm the bloc economically in a new world where trade is increasingly used as a weapon.
German officials said the EU needed a tool as powerful as the Section 301 tariffs imposed by the U.S. or China’s restrictions on exports of critical minerals.
The new measure would not target any specific country, but highlights dumping, widespread subsidies and restriction of currency convertibility – market distortions that many EU leaders say China is engaged in.
A French-German document published on Monday, 10 days before EU leaders discuss Chinese trade imbalances at a summit in Brussels, said “systemic and persistent market distortions” jeopardize the European economy and particularly its industrial base, with widespread job losses.
The bloc, said the document, needs to deploy its trade defense tools more swiftly and efficiently, with more investigations and a broader approach to cover whole sectors.
France and Germany also said the European Commission should propose two new instruments as soon as possible to focus EU efforts on diversification and securing economic security.
The first, which the Commission has already mentioned, would seek to limit companies’ reliance on single sources for certain critical supplies.
The second would limit access to the EU single market for countries that undermine fair market conditions through political or economic means, without specifying what the trigger for EU reaction would be or what action the EU should take.
The paper said that any proposal by the Commission to activate counter-measures against another country should be adopted unless a qualified majority of EU members opposed – a lower hurdle than for some trade measures.
The paper also said the Commission should be able to activate such new measures swiftly, which German government officials said could mean a matter of days.
Legislation to enact a new instrument would still need approval by EU governments and the European Parliament.
A French presidential adviser said it was urgent for the EU to take action, that the imbalances with some trade partners had become unsustainable, and that France and Germany were keen for the bloc to deploy existing anti-dumping measures as soon as possible.
“France and Germany are very keen to put an end to the naivete on trade,” the adviser told reporters.
Brazilian assets were trading higher on Monday after right-wing Senator Flavio Bolsonaro, the son of ex-leader Jair Bolsonaro, came in first in the first round of Sunday’s presidential election.
The Bovespa benchmark stock index gained more than 8% and the country’s currency strengthened against the U.S. dollar following the vote.
The eldest son of former President Jair Bolsonaro won 47% of the votes and will face leftist incumbent President Luiz Inacio Lula da Silva, who secured about 45% of the vote, in a runoff on Oct. 25. Polls had forecast Lula would lead the first round of voting by around three percentage points.
Investors cheered on Monday morning as Bolsonaro’s strong showing was matched by gains for his allies in Congress. Analysts say a friendlier legislature would make it easier for him, if elected, to push through a pro-market agenda of tighter public spending, privatizations and tax cuts.
“Brazil wants change,” Bolsonaro said on Sunday evening, heralding the “end of the era of (Lula’s) Workers’ Party.”
Shares in retailer Magazine Luiza, stock exchange operator B3, lender BTG Pactual, homebuilder Cyrela and conglomerate Cosan jumped more than 20% each, putting them among the top gainers.
J.P. Morgan upgraded Brazil’s equities to “overweight” on Monday, saying a more favorable political backdrop after recent election developments had improved the outlook for the region’s largest market and could drive a period of outperformance.
Brazil’s real currency strengthened more than 4% against the U.S. dollar in early trading, moving below 5.00 per greenback, from around 5.22 previously, in line with analyst forecasts and with the currency’s performance four years ago when then-President Jair Bolsonaro did better than expected in the first-round vote against Lula.
The elder Bolsonaro went on to lose to Lula in the second round of that election and was subsequently convicted of trying to carry out a coup to overturn the result. The former president was sentenced to about 27 years in prison and is currently under house arrest.
Brazil’s international debt also rallied on Monday, while broader fixed-income markets were jittery. The 2056 bond was up 1.4 cents on the dollar to bid at 93.5 cents, Tradeweb data showed.
‘The market wants change’
Bolsonaro has pitched himself as a “more centered” version of his father to investors concerned about Brazil’s burgeoning fiscal pressures.
“It remains to be seen whether the senator would ultimately prove more fiscally responsible than Lula would be in a fourth non-consecutive presidential term. However, markets are likely to give him the benefit of the doubt,” said Thierry Larose, portfolio manager at Vontobel.
If he is elected, Bolsonaro would enjoy some room to maneuver with Congress after his Liberal Party emerged as the biggest winner in congressional races on Sunday.
Bolsonaro’s party increased its representation in the Senate from 15 to 28 seats, the strongest result for a party since Brazil’s return to democracy in 1985. It also is projected to secure 121 seats in the lower house, up from its current 98 seats.
“The likelihood of advancing reforms is much greater,” said Pedro Paulo Silveira, an analyst at Terra Investimentos. He noted that during the previous Bolsonaro government, reforms often depended on costly political bargaining or stalled altogether.
Analysts also expect the real to continue strengthening into 2027. Societe Generale forecast that it would move to 5.10 by the end of 2026, with scope to move below 5.00 in the first half of 2027. Morgan Stanley forecast the real could strengthen past 4.90 and toward 4.50 in the first quarter of next year.
“The market wants change, it wants reform; it doesn’t want a high public deficit; with the current government, all of this will continue,” said Pedro Galdi, investment analyst at the AGF Investments platform.
Bolsonaro’s strong showing is likely to boost market confidence in the near term, said Bryan Harris, a managing partner at Sabio.
“The market will be looking for clear signals from Bolsonaro that he is serious about tackling the country’s problems,” Harris said.
Heading into Sunday’s vote, most private polls, which largely underestimated the younger Bolsonaro’s strength, had shown the 45-year-old senator and Lula, who will turn 81 later this month, about even in a runoff vote.
Addressing a crowd at a hotel in Sao Paulo, Lula said he had been convinced he would win the election in the first round.
“Starting tomorrow, we begin a new campaign,” the leftist leader said, promising to show voters what he had accomplished as president.
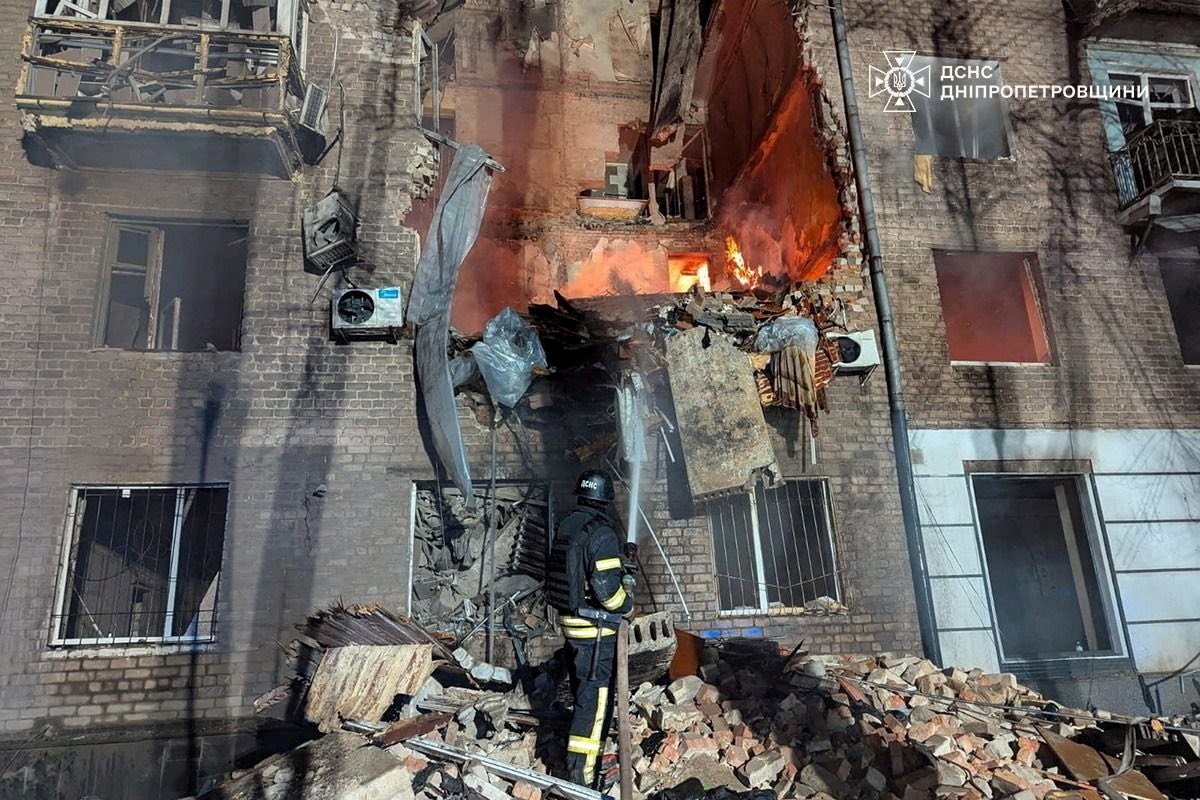
Kryvyi Rih, the hometown of Ukrainian President Volodymyr Zelenskyy, is struggling to survive. Russian airstrikes have brought the city’s huge steel plant and mines to a standstill, dragging the local economy to its knees.
Mayor Oleksandr Vilkul said the sprawling industrial city – which stretches along the banks of the Inhulets River – was doing everything possible to ensure its hospitals remain open, the lights remain on in kindergartens and schools, and buses keep running.
“In Kryvyi Rih, the situation is actually worse than anywhere else, apart from the front line itself,” Vilkul, 52, a former mining executive, said in a video address.
The financial squeeze on the city of about 600,000 people underlines the challenges facing Ukraine as the government navigates its biggest budget crisis since Russia’s full-scale invasion in 2022.
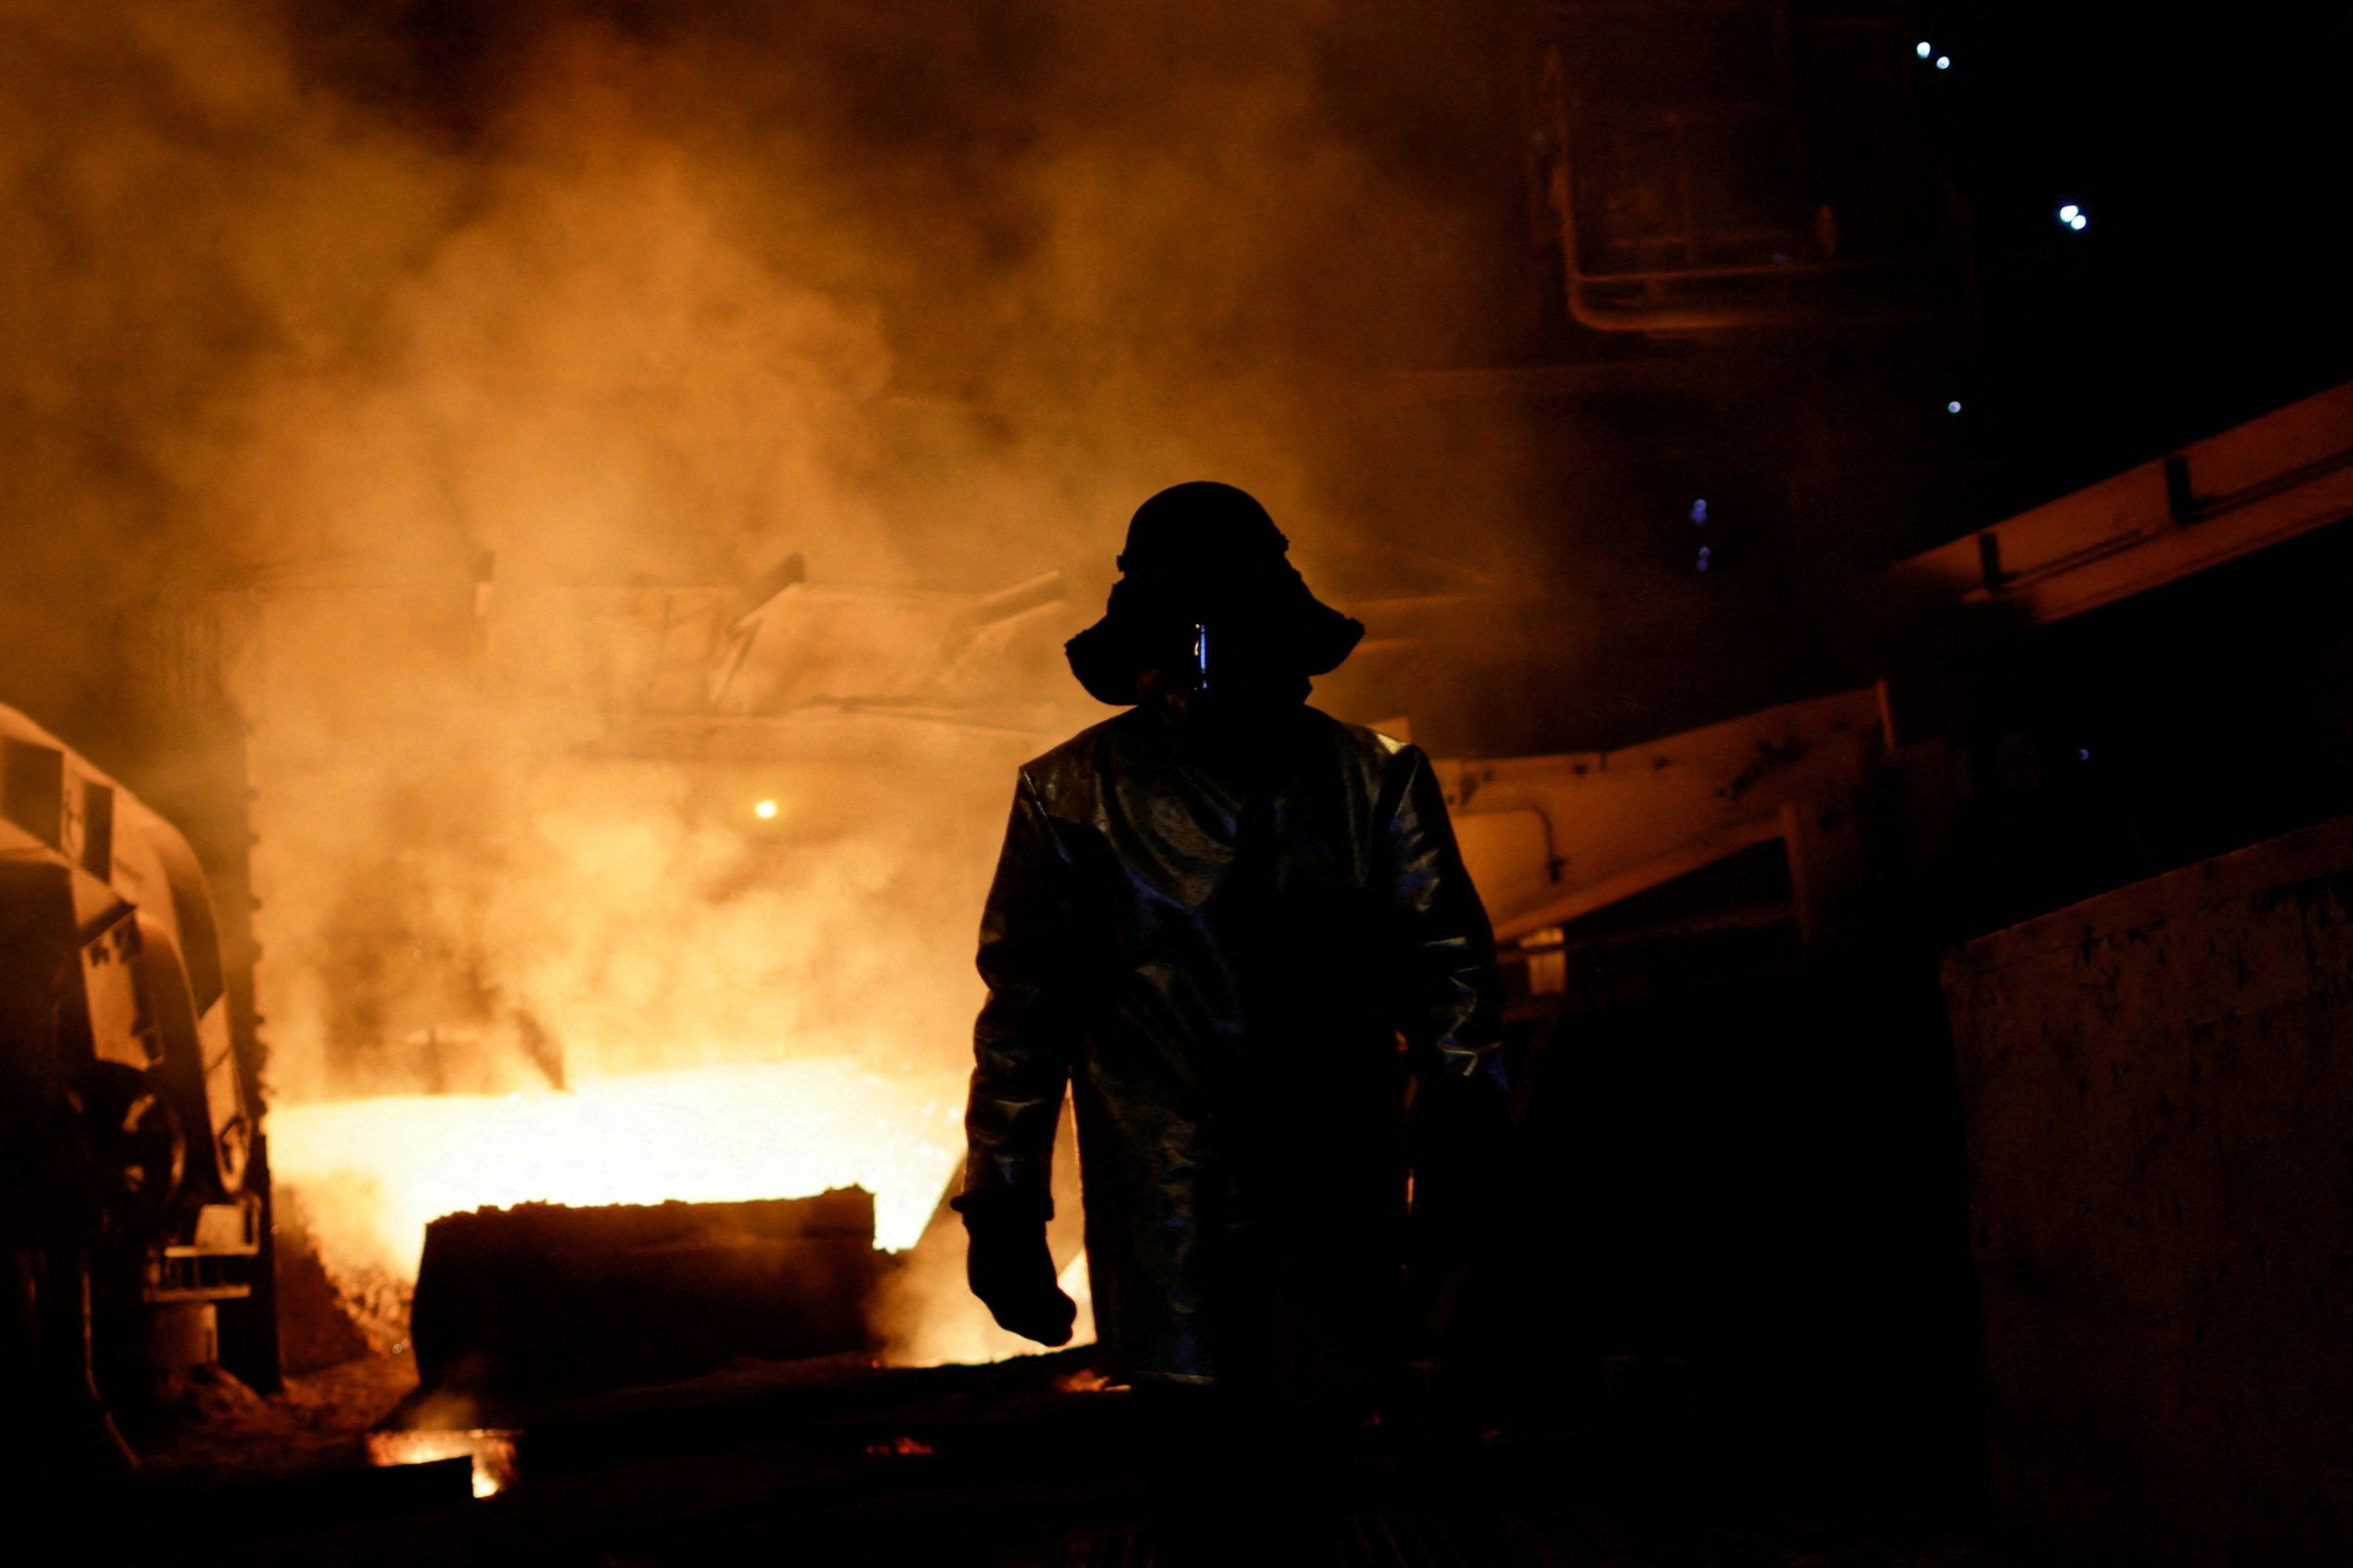
Last month, the city’s largest employer – ArcelorMittal’s hulking mining and steelmaking complex – suspended its operations following a series of Russian ballistic missile strikes that darkened its furnaces.
The prospects for next year, Vilkul said, are bleak.
“It’s about survival. Right now, we need to survive,” he said.
It’s a scene played out across Ukraine’s once-mighty steel industry, which accounted for a tenth of economic output before the war. Giant mills in Zaporizhzhia in the southeast and other industrial cities stand silent and exports have stopped.
An escalation in Russia’s drone and missile strikes this summer destroyed factories and warehouses across Ukraine, damaged ports and railways, and forced shops and businesses to close, slowing the growth of the economy and tax revenue.
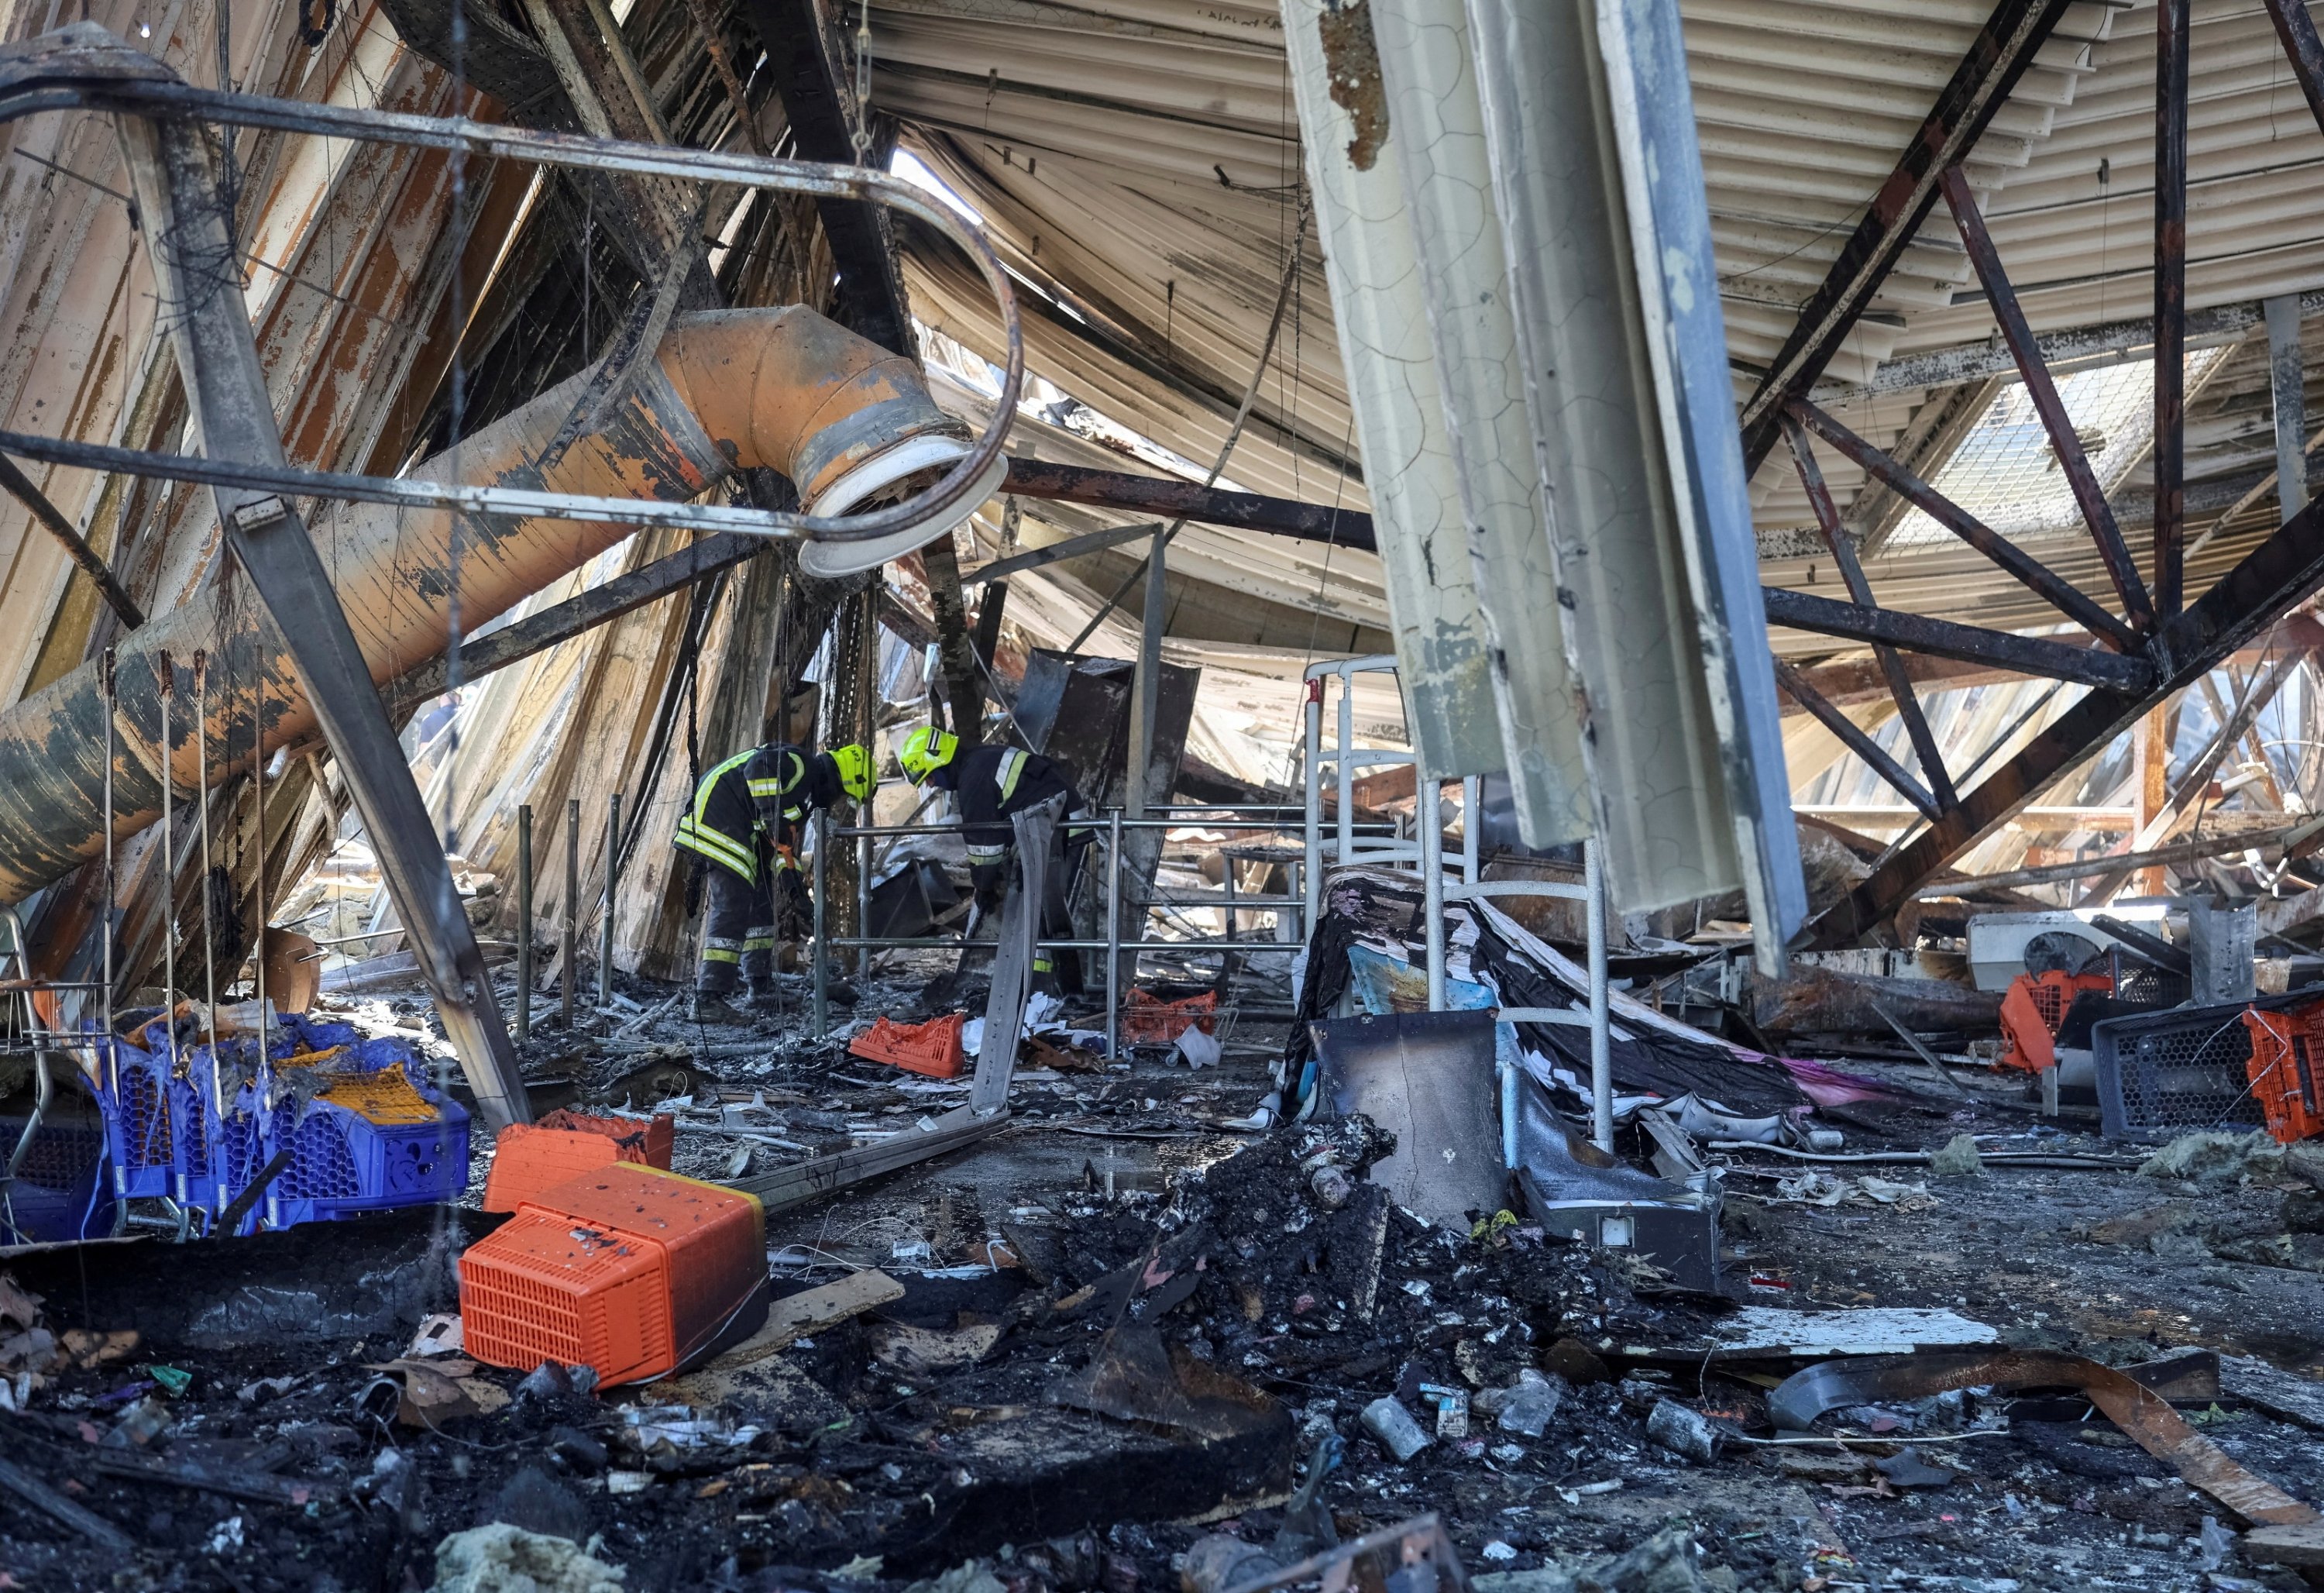
Meanwhile, the technology-driven war is becoming ever more expensive for Ukraine to fight.
Billions of euros in foreign loans have been delayed by failure to pass bills including unpopular tax reforms and anti-corruption legislation demanded by Ukraine’s Western allies, leaving a gaping hole in state coffers.
Ukraine needs $56 billion to fund that gap this year – equivalent to about a quarter of its economic output. Of that, $27 billion is military spending.
To bridge the shortfall, Ukrainian officials met European partners in Brussels last week to discuss bringing forward disbursements due next year under a 90-billion-euro ($101-billion) EU loan. The European Commission and Ukraine said they had identified funds to close the gap this year.
But three sources familiar with the talks said accelerating these payments risked increasing budget pressure next year – at a time when looming election campaigns in European allies including France and Poland could erode support for Kyiv.
Prime Minister Sergii Koretskyi acknowledges the situation is “challenging.” The government has been forced to freeze nonessential spending – including reconstruction of damaged buildings and infrastructure – to prioritize military spending, public sector wages and pensions.
“All resources should be channeled into critically important areas,” Koretskyi told reporters.
War costs soar, domestic revenues fall
Two years ago, a single day of fighting cost Ukraine $140 million, but that figure has jumped to $190 million, according to Roksolana Pidlasa, the head of parliament’s budget committee. And that does not include direct military support to Kyiv from its Western allies.
Rising costs are driven partly by the need for expensive medium- and long-range weapons capable of striking Russia’s oil refineries and military factories to reduce Moscow’s ability to continue its war.
Plus, the wage bill for an expanded army is higher than ever before, and the state must support a growing number of military families of disabled or deceased soldiers.
“Expenditure will continue to rise,” Pidlasa told a conference in Kyiv. “This is one more pragmatic reason why the U.S. and Europe need to act faster to force (Russia) to end this war.”
In the first nine months of this year, Ukraine spent more than $44 billion on defense alone, data showed. That does not include in-kind military support from allies.
In the same period, the government was able to raise only about $42 billion in tax revenue as the economy slowed.
Pidlasa said that in the first nine months of this year, Ukraine’s budget lost over 49.5 billion hryvnias ($1.1 billion) in tax revenue because of Russian attacks that not only damaged property and goods, but disrupted logistics and shut shops and businesses for hours at a time.
By the end of the year, the cumulative losses could rise to 70 billion hryvnias, the government estimates.
“We have not a temporary but a structural problem with the revenues at the very time when spending really requires resources,” said Oleksandra Myronenko, an economist at the Center for Economic Strategies, a Kyiv-based think tank.
Some Ukrainian businesses have started to scale back operations. Others have put capital expenditure on hold as the country braces for a difficult winter. Business sentiment and economic expectations are darkening.
Vasyl Khmelnytskyi, founder of an industrial park in the city of Bila Tserkva near Kyiv, said he had scrapped plans to build three new factories.
“The risks are simply too great right now – both for the business and for the people,” he said in a Facebook post.
Ukraine’s agricultural sector – its largest source of export revenues – has been particularly hard hit. Russian attacks on Ukraine’s Black Sea ports led to a 36.6% fall in grain exports year-over-year in September.
About $40 billion in export revenue is at risk this year as a result of the blockade, Economy Minister Oleksandr Kravchenko said.
Even with tens of billions of euros in foreign support, Ukraine’s economy is expected to grow only between 0.5% and 1.5% this year, economists say – down from 1.8% in 2025.
Foreign aid is delayed
During more than four years of intense fighting, Ukraine has been able to maintain macroeconomic and financial stability thanks to fiscal support from its Western partners, receiving nearly $200 billion since Russia’s invasion.
But $29.5 billion in foreign aid is now at risk this year because of delays in passing reforms, Koretskyi said. The government has postponed about $900 million of capital spending until December, in the hope the legislation will be passed.
The aim is to pass all the required legislation in parliament by Oct. 15, Koretskyi said.
“Only then we will get all the money,” Koretskyi said. “This is absolutely vital. It needs to be done as soon as possible.”
Legislators are now discussing the budget for next year. The government has proposed record defense budget spending of $110 billion. This figure does not include direct military aid.
Finance Minister Sergii Marchenko has estimated that the unfunded budget gap for the next year is already more than $32 billion.
Part of the solution, Marchenko said, is to use frozen Russian assets in Europe to fund Ukraine’s budget. EU countries immobilized some 210 billion euros of Russian central bank assets after Moscow invaded Ukraine.
“Ukraine continues to mobilize domestic resources, but the scale of Russia’s war puts clear limits on our capacity,” Marchenko said on the social media platform X.


-
 Economy1 day ago
Revolut: $115 billion fintech taking on Europe’s biggest banks
-

 Economy1 day ago
Global M&A deal rush slowed down in Q3 as borrowing costs bite
-
 Politics3 days ago
Sumud Flotilla repairs ships in Türkiye for new Gaza voyage
-
 Economy3 days ago
Teknofest Southeast combines technology, local culture in Şanlıurfa
-
 Economy2 days ago
Egypt’s Sisi calls for peaceful solutions to Africa’s conflicts
-
 Sports1 day ago
Ronaldo’s Portugal future enters uncharted waters after walkout
-
 Economy1 day ago
ACE BPSC 2026 summit to be held this week in Istanbul
-
 Politics1 day ago
Erdoğan vows action over Soma mine collapse at Teknofest