Economy
Global debt hit record high of nearly $338 trillion as of end-Q2

Global debt hit a record high of $337.7 trillion at the end of the second quarter, driven by easing global financial conditions, a softer U.S. dollar and a more accommodative stance from major central banks, a quarterly report showed on Thursday.
The Institute of International Finance (IIF), a financial services trade group, said that global debt rose over $21 trillion in the first half of the year to $337.7 trillion.
China, France, the United States, Germany, Britain, and Japan recorded the largest increases in debt levels in U.S. dollar terms, though some of that was due to a waning dollar, the IIF found.
The U.S. currency has weakened 9.75% since the start of the year against a basket of major trading partners.
Global debt surge comparable to COVID-era increase
“The scale of this increase was comparable to the surge seen in H2 2020, when pandemic-related policy responses drove an unprecedented buildup in global debt,” the IIF said in its Global Debt Monitor.
Looking at debt-to-GDP ratios – an indicator of the ability to repay debt by comparing to what is being produced – Canada, China, Saudi Arabia and Poland saw the sharpest increases. The ratio declined in Ireland, Japan, and Norway, the report found.
Overall, the global debt-to-output ratio continued to move slowly lower, standing just above 324%. However, in emerging markets, the ratio hit 242.4% – a new record after a downward revision on the last report in May.
Total debt in emerging markets rose by $3.4 trillion in the second quarter to a record high of more than $109 trillion.
Emre Tiftik, IIF Sustainable Research Director, said in a webinar that rising military spending will strain government balance sheets amid intensifying geopolitical tensions.
Tiftik noted that the debt increase is mainly in government debt, which has risen sharply in G-7 countries and China.
He added that bond market reactions are harsher in advanced economies, with G-7 10-year yields near their highest since 2011.
Bond market pressures
Emerging markets face a record high of nearly $3.2 trillion in bond and loan redemptions in the remainder of 2025, the IIF said.
It warned that fiscal strains could intensify in countries such as Japan, Germany, and France, urging caution over so-called “bond vigilantes” –referring to investors who sell off bonds of countries whose finances they deem unsustainable.
“While government debt ratios rose sharply across emerging markets in H1 – most notably in Chile and China – market reaction has been stronger in mature markets this year,” the IIF said.
The report flagged U.S. debt concerns, noting that short-term borrowing makes up about 20% of total debt and 80% of Treasury issuance.
It warned that this reliance could increase political pressure on central banks to keep rates low, risking monetary policy independence.
Türkiye said on Tuesday it plans to complete the liquidation of about half of the investment funds caught up in last month’s market turmoil by the end of this week.
The crisis began after several funds said they could not meet investors’ redemption requests during a market sell-off. That prompted a wide investigation into suspected price manipulation in a number of thinly traded stocks.
The Capital Markets Board (SPK) suspended trading in 131 funds run by seven asset management companies and placed them into liquidation, affecting nearly half a million investors.
Seventeen funds run by three of the companies, A1 Capital, Bulls and Pardus, were settled last week, with a total of TL 6.4 billion (nearly $130 million) paid back to 43,643 investors, the Communications Directorate said.
The statement came following a meeting of the Fund Coordination Board, set up to oversee the liquidation process.
The three companies have 49 other funds holding a total of TL 34.1 billion lira, and the board aims to finish liquidating them this week, the directorate said.
If it does, all 66 funds run by the three companies will have been settled. They cover 45,745 people and TL 40.5 billion lira, in cash and in kind.
The statement said a bill meant to make the liquidation fair, transparent and effective, and to give payments a legal footing, was submitted to parliament on Friday. It is expected to be discussed on Wednesday at Parliament’s Planning and Budget Committee. The bill gives priority to money market funds and small investors.
Once it becomes law, the aim is to complete interim payments quickly for the other 65 funds still in liquidation, the statement said. These belong to the four remaining companies, Tera, Pusula, Hedef and Atlas, which are due to go through the extraordinary liquidation process set out in the bill.
Vice President Cevdet Yilmaz, who chairs the board, has said the bill would provide for interim payments of up to TL 1 million of principal and that fewer than 100,000 investors would be waiting once it passes.
Prosecutors have arrested more than 80 people in a related investigation into suspected market manipulation.
The EU sought Tuesday to downplay its reliance on Russian fossil fuel imports after Moscow boasted of its sales, seizing upon the controversy sparked by a U.S. decision to buy Russian diesel.
Russia said on Monday it had sold European countries more than $320 billion worth of hydrocarbons since 2022, despite sanctions imposed over the war in Ukraine.
European countries purchased $21.3 billion worth of Russian hydrocarbons in the first nine months of 2026 alone, Russian Deputy Prime Minister in charge of energy Alexander Novak said on television.
“In other words, despite sanctions-related restrictions, we continue to supply energy resources in certain areas for which exemptions have been granted,” Novak added.
He said Russian oil exports may reach their pre-war levels by the end of the year.
The European Commission responded by providing a lower figure – $209 billion since the invasion of Ukraine in February 2022 – and stressing that the 27-nation bloc was working toward ending all Russian gas imports by the end of 2027.
“We are in this for the long term and that trend is very clear,” commission spokesperson Anna-Kaisa Itkonen told a press conference in Brussels.
Moscow pointed to its European sales after some European countries criticized a deal allowing the United States to import Russian diesel.
The rebuke did not go down well in Washington, where the administration of U.S. President Donald Trump is seeking to bring down soaring fuel prices ahead of key midterm elections in November.
“The European Union paid Russia 250 Billion Dollars for Energy, and the Fake News Media doesn’t want to get near that story. I made the right choice for the American People – ALWAYS, AMERICA FIRST!,” Trump posted on Truth Social on Monday.
U.S. Treasury Secretary Scott Bessent on Sunday accused European nations of “hypocrisy,” as they “continue to finance Vladimir Putin” while criticizing the diesel agreement.
The European Union has taken significant steps to reduce its longstanding dependence on Russian pipeline gas and sap Moscow’s war chest since 2022.
Overall Russian gas imports, which represented 45% of the total in 2021, are down to 12%, Itkonen noted.
However, the bloc has increasingly turned to LNG shipped by sea, unloaded at ports, regasified and fed into the European network.
After the United States, which supplies about 60% of the EU’s LNG imports, Russia remains the bloc’s second-largest LNG supplier, accounting for around 17% of imports in 2026.
Several landlocked EU countries, including Slovakia and Hungary, also benefit from exemptions allowing them to purchase Russian oil transported via pipeline.
Swedish Foreign Minister Maria Malmer Stenergard pointed to the figure cited by Russia on Monday, lamenting it was higher than the 218.7 billion euros ($244 billion) the bloc has sent in support to Ukraine since the beginning of the war.
“We have imported a higher amount to the EU countries than we have given support to Ukraine,” Malmer Stenergard said. “If we would use the frozen assets, we would almost double the total support that we have given to Ukraine,” she added, referring to Russian sovereign funds held by the bloc.
“That would be a game-changer, and a game-changer is exactly what Ukraine needs.”
The International Monetary Fund (IMF) lowered on Tuesday its growth projection for the Turkish economy for this year, while keeping the outlook for the next year unchanged.
The IMF published its World Economic Outlook as part of the 2026 Annual Meetings of the IMF and the World Bank, held this week in Bangkok.
The fund said it expects Turkish gross domestic product (GDP) to grow 2.7%, down from 2.9% projection it shared in July. In 2027, the economy is expected to expand at 3.6%.
The fund also said it expects Türkiye’s annual consumer inflation at 31.2% in 2026 and 26.5% next year.
Türkiye’s annual inflation dropped below 30% for the first time in nearly five years as consumer price growth eased more than expected to 29.73% in September, according to official data.
For the global economy, the monetary body lifted the outlook by 0.1 percentage points to 3.1% this year. However, it cited disruptions caused by conflicts and the AI’s transformative role.
Business leaders and diplomats used a summit in Brussels on Tuesday to push for closer economic ties between Türkiye and the European Union, again calling for a modernized customs union, a place in the bloc’s industrial supply chains and a clearer accession perspective.
Belgium’s foreign minister also voiced support for updating the over 30-year-old trade agreement.
Speaking at the EU-Türkiye Business Summit, executives and officials argued that deeply integrated economies need a political and institutional framework that reflects their commercial reality.
Foreign Economic Relations (DEIK) President Nail Olpak quoted Jean Monnet’s line that Europe will be forged in crises and will be the sum of the solutions adopted for those crises.
“We are living in such a time. And I believe deeper integration with Türkiye is one of the answers Europe needs today,” Olpak said.
Priorities
He set out three priorities for the partnership.
The first is modernizing the customs union, which he said has been the backbone of economic ties for more than three decades but no longer meets current needs. “In a world that has changed this fast, we’re missing too many opportunities together,” said Olpak. An update would open up cooperation in services, e-commerce, public procurement and agriculture.
The second is recognizing Türkiye’s place in European industry. Olpak referred to the European Union’s proposed “Made in EU” rules, or how he reframed it, “Made with EU,” saying Türkiye has been part of the continent’s supply and value chains for over 30 years. Treating Turkish-made products as part of Europe’s industrial ecosystem “without new quotas or barriers,” he argued, is critical to Europe’s own resilience and competitiveness.
The third is connectivity. Citing the war in Ukraine and instability in the Middle East, he said the Middle Corridor, which links Europe with Central Asia via Türkiye and the South Caucasus, should remain a shared strategic priority. He also pointed to emerging north-south links connecting Europe and Türkiye with Iraq and the Gulf. He said geopolitical shocks “showed why we need reliable links for transport, energy and data.”
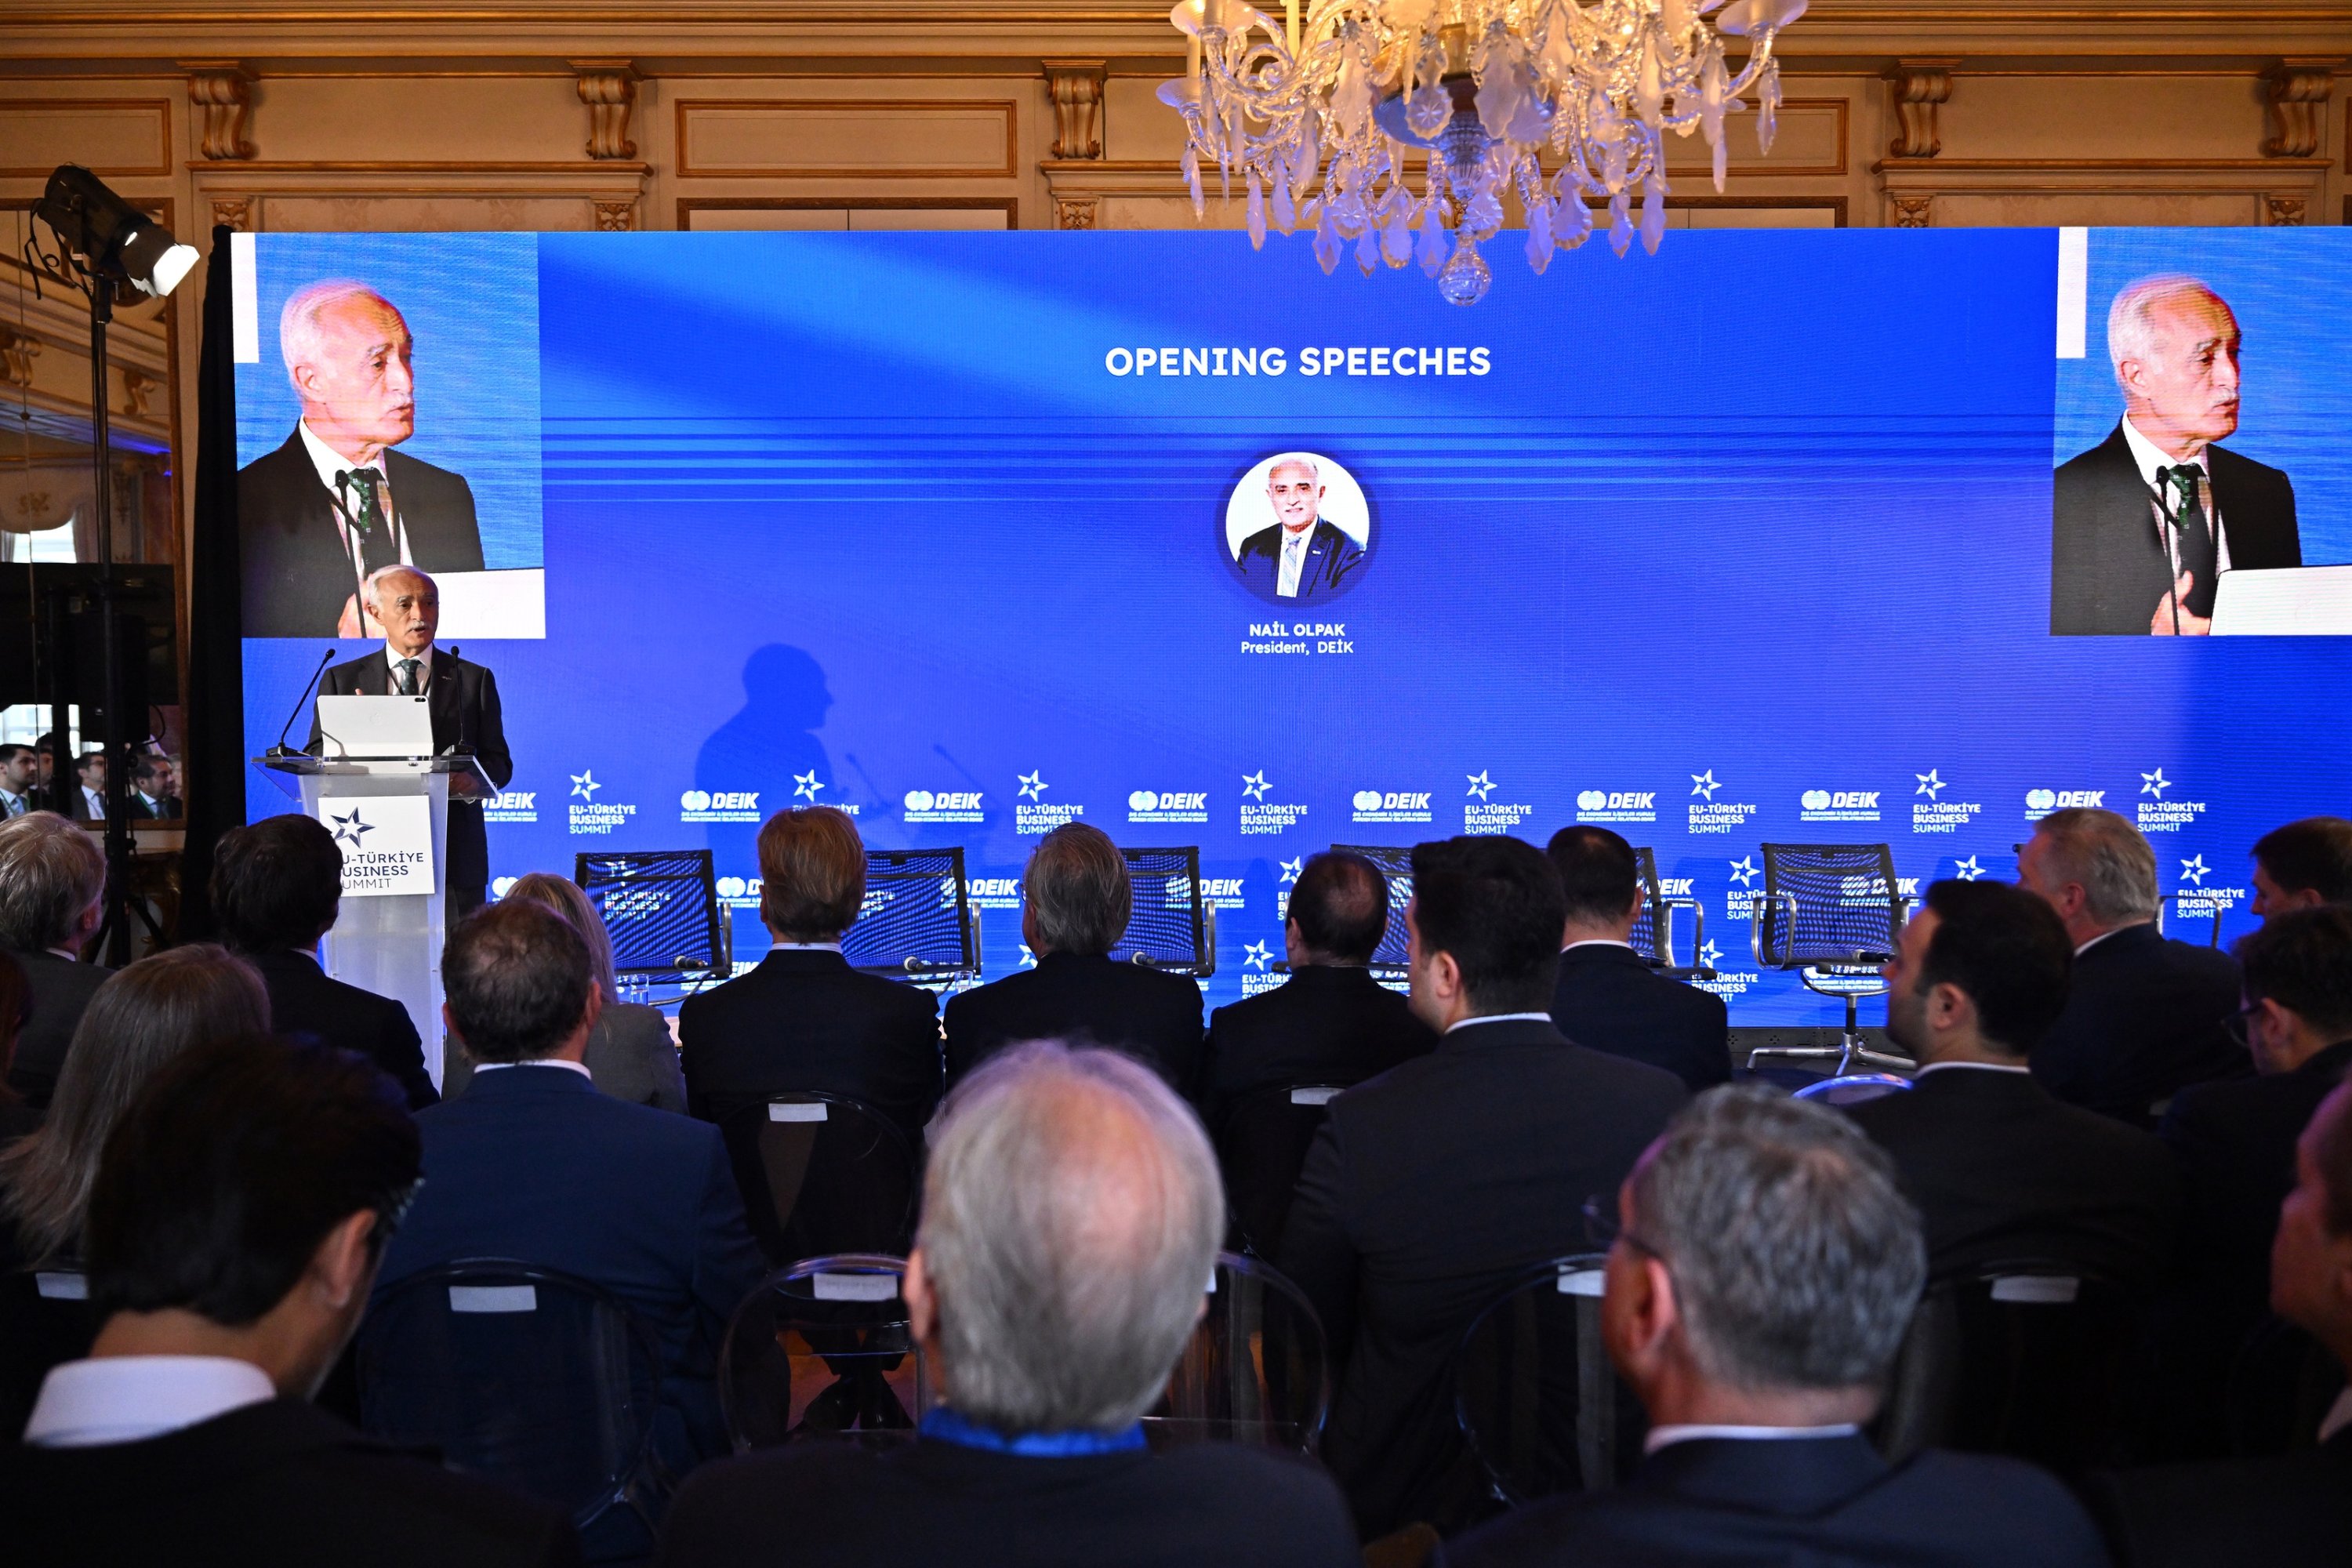
Tying the themes together, Olpak spoke of “competition on trust,” saying trust is built through performance rather than words and that Türkiye has proven itself a dependable partner through every crisis.
Türkiye’s European journey began more than 60 years ago, he noted, and full membership remains its goal. “After so many years, we need fresh momentum,” Olpak said.
Call for clear membership signal
Mehmet Ali Yalçındağ, coordinator chair of the DEIK Türkiye-EU Business Councils, said a “clear and credible reaffirmation” of Türkiye’s membership perspective would give the relationship direction, encourage reform and strengthen confidence in Europe’s ability to act with purpose.
He noted that the heads of DEIK’s 26 business councils with EU member states wrote earlier this year to the leaders of the European institutions, asking for renewed momentum in the accession process. He also welcomed European Commission President Ursula von der Leyen’s recent State of the Union address, which he said put competitiveness, security, affordable energy, AI and democratic resilience at the center.
Europe “will not become more competitive by excluding Türkiye from the economic space where our businesses already work together,” Yalçındağ said, adding that it grows stronger by building on its value chains rather than drawing new boundaries through them.
He urged both sides to move beyond arguments repeated for too long, saying caution has at times replaced initiative, to the benefit of competitors. Political dialogue, credible conditionality and practical cooperation can advance together, he said, without every disagreement being resolved first.
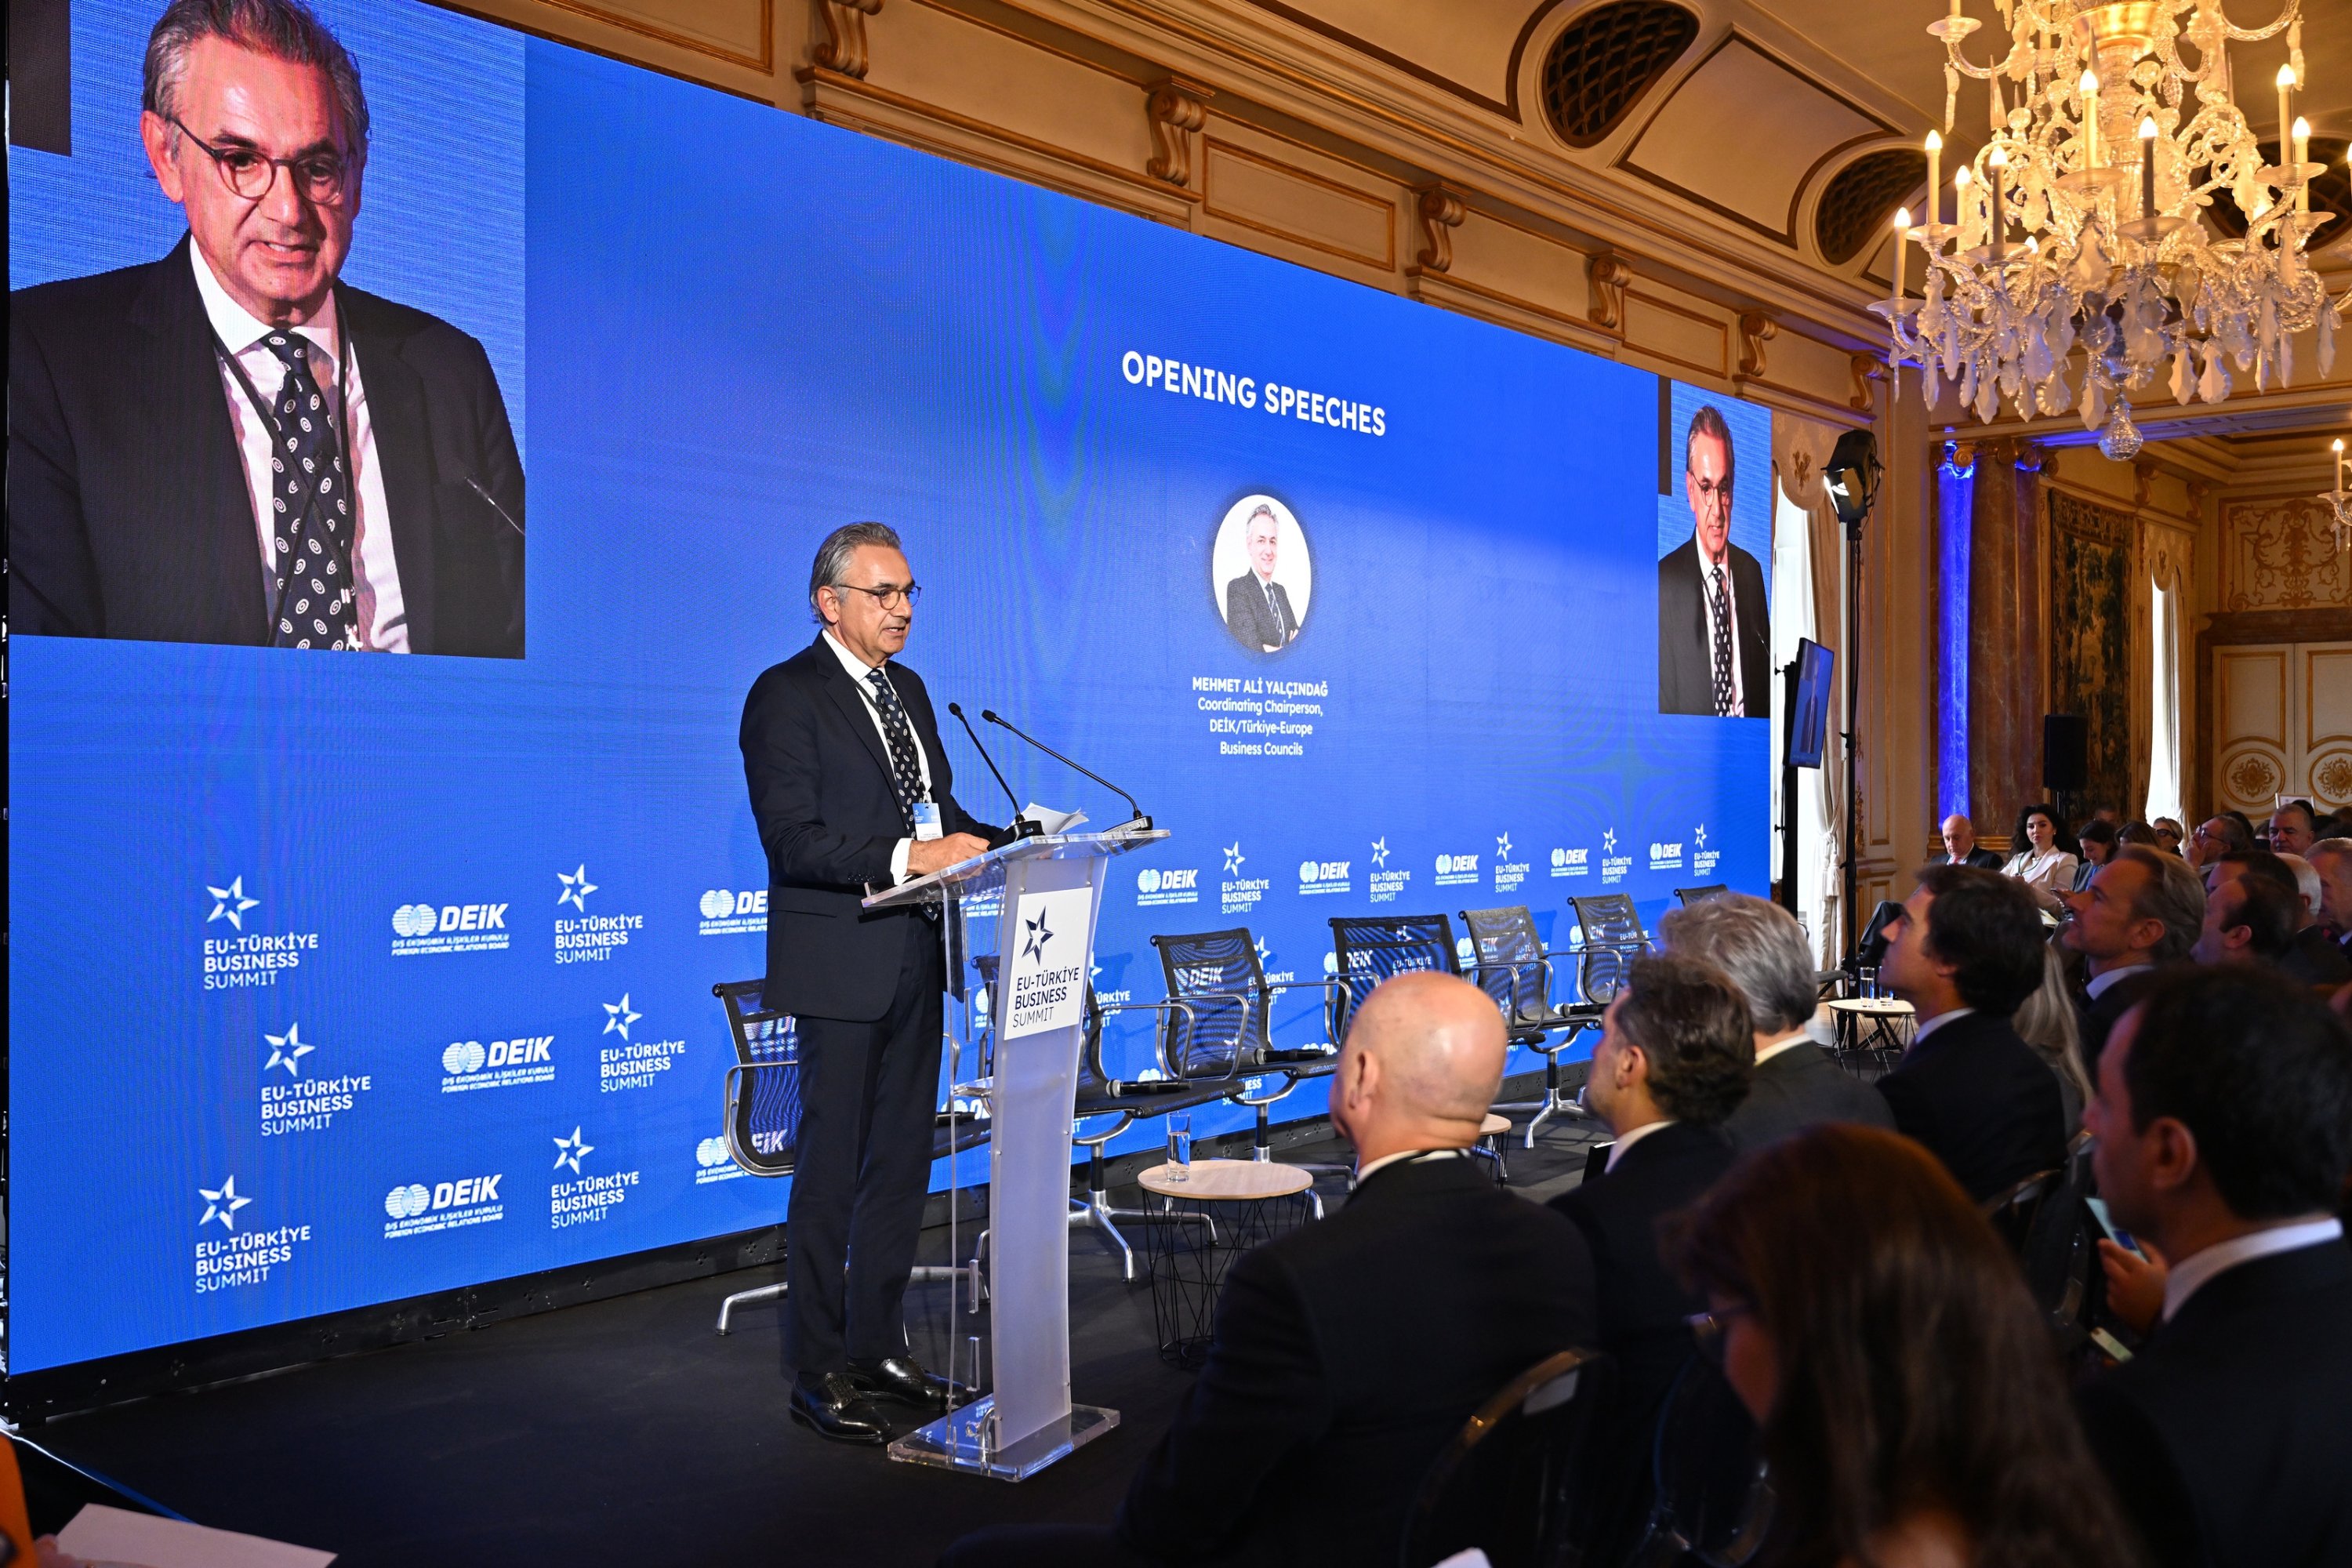
A clear commitment to Türkiye’s European future, he added, could help open the way to a modernized customs union, easier business mobility and visas, and closer cooperation on technology, energy, transport, defense and the green transition. He closed by urging both sides to act without adding “another ‘yes, but'” to a relationship already burdened by too many.
Industrial Accelerator Act in focus
“Türkiye and the EU need each other more than ever,” said Ambassador Yaprak Balkan, Türkiye’s permanent delegate to the EU, speaking at a summit session titled “Made in Europe or Made with Europe? The Industrial Accelerator Act Revisited.”
She said Türkiye shares the EU’s goals of building more resilient industry and speeding up decarbonization, but that neither side should weaken the value chains that make both more competitive.
Balkan said much of her team’s recent work has centered on the “Made in Europe” approach, which would prioritize European-made products in public procurement and subsidies under the proposed act, and that they have been working day and night to persuade partners with facts and scientific data.
Her central argument was legal. Decision 1/95 of the Association Council, which established the customs union, provides for removing duties and non-tariff barriers on industrial goods. If the act takes shape in the way Ankara fears, she said, it could contradict existing commitments.
Türkiye’s unique relationship with the EU through the customs union must be fully reflected in the legislation, Balkan said, and if it defines which partners are covered, Türkiye must be included from the outset. Where origin requirements are met, vehicles made in Türkiye should receive equivalent treatment.
Bilateral trade between Türkiye and the EU reached a record of about 207 billion euros last year. Automotive trade alone totaled 54 billion euros, roughly a quarter of the total, making Türkiye the third-largest export market for the EU automotive industry.
About 70% of vehicle production in Türkiye rests on direct or joint investments by major European manufacturers, Balkan said, and more than half of the parts and components in a car made there are imported from the EU.
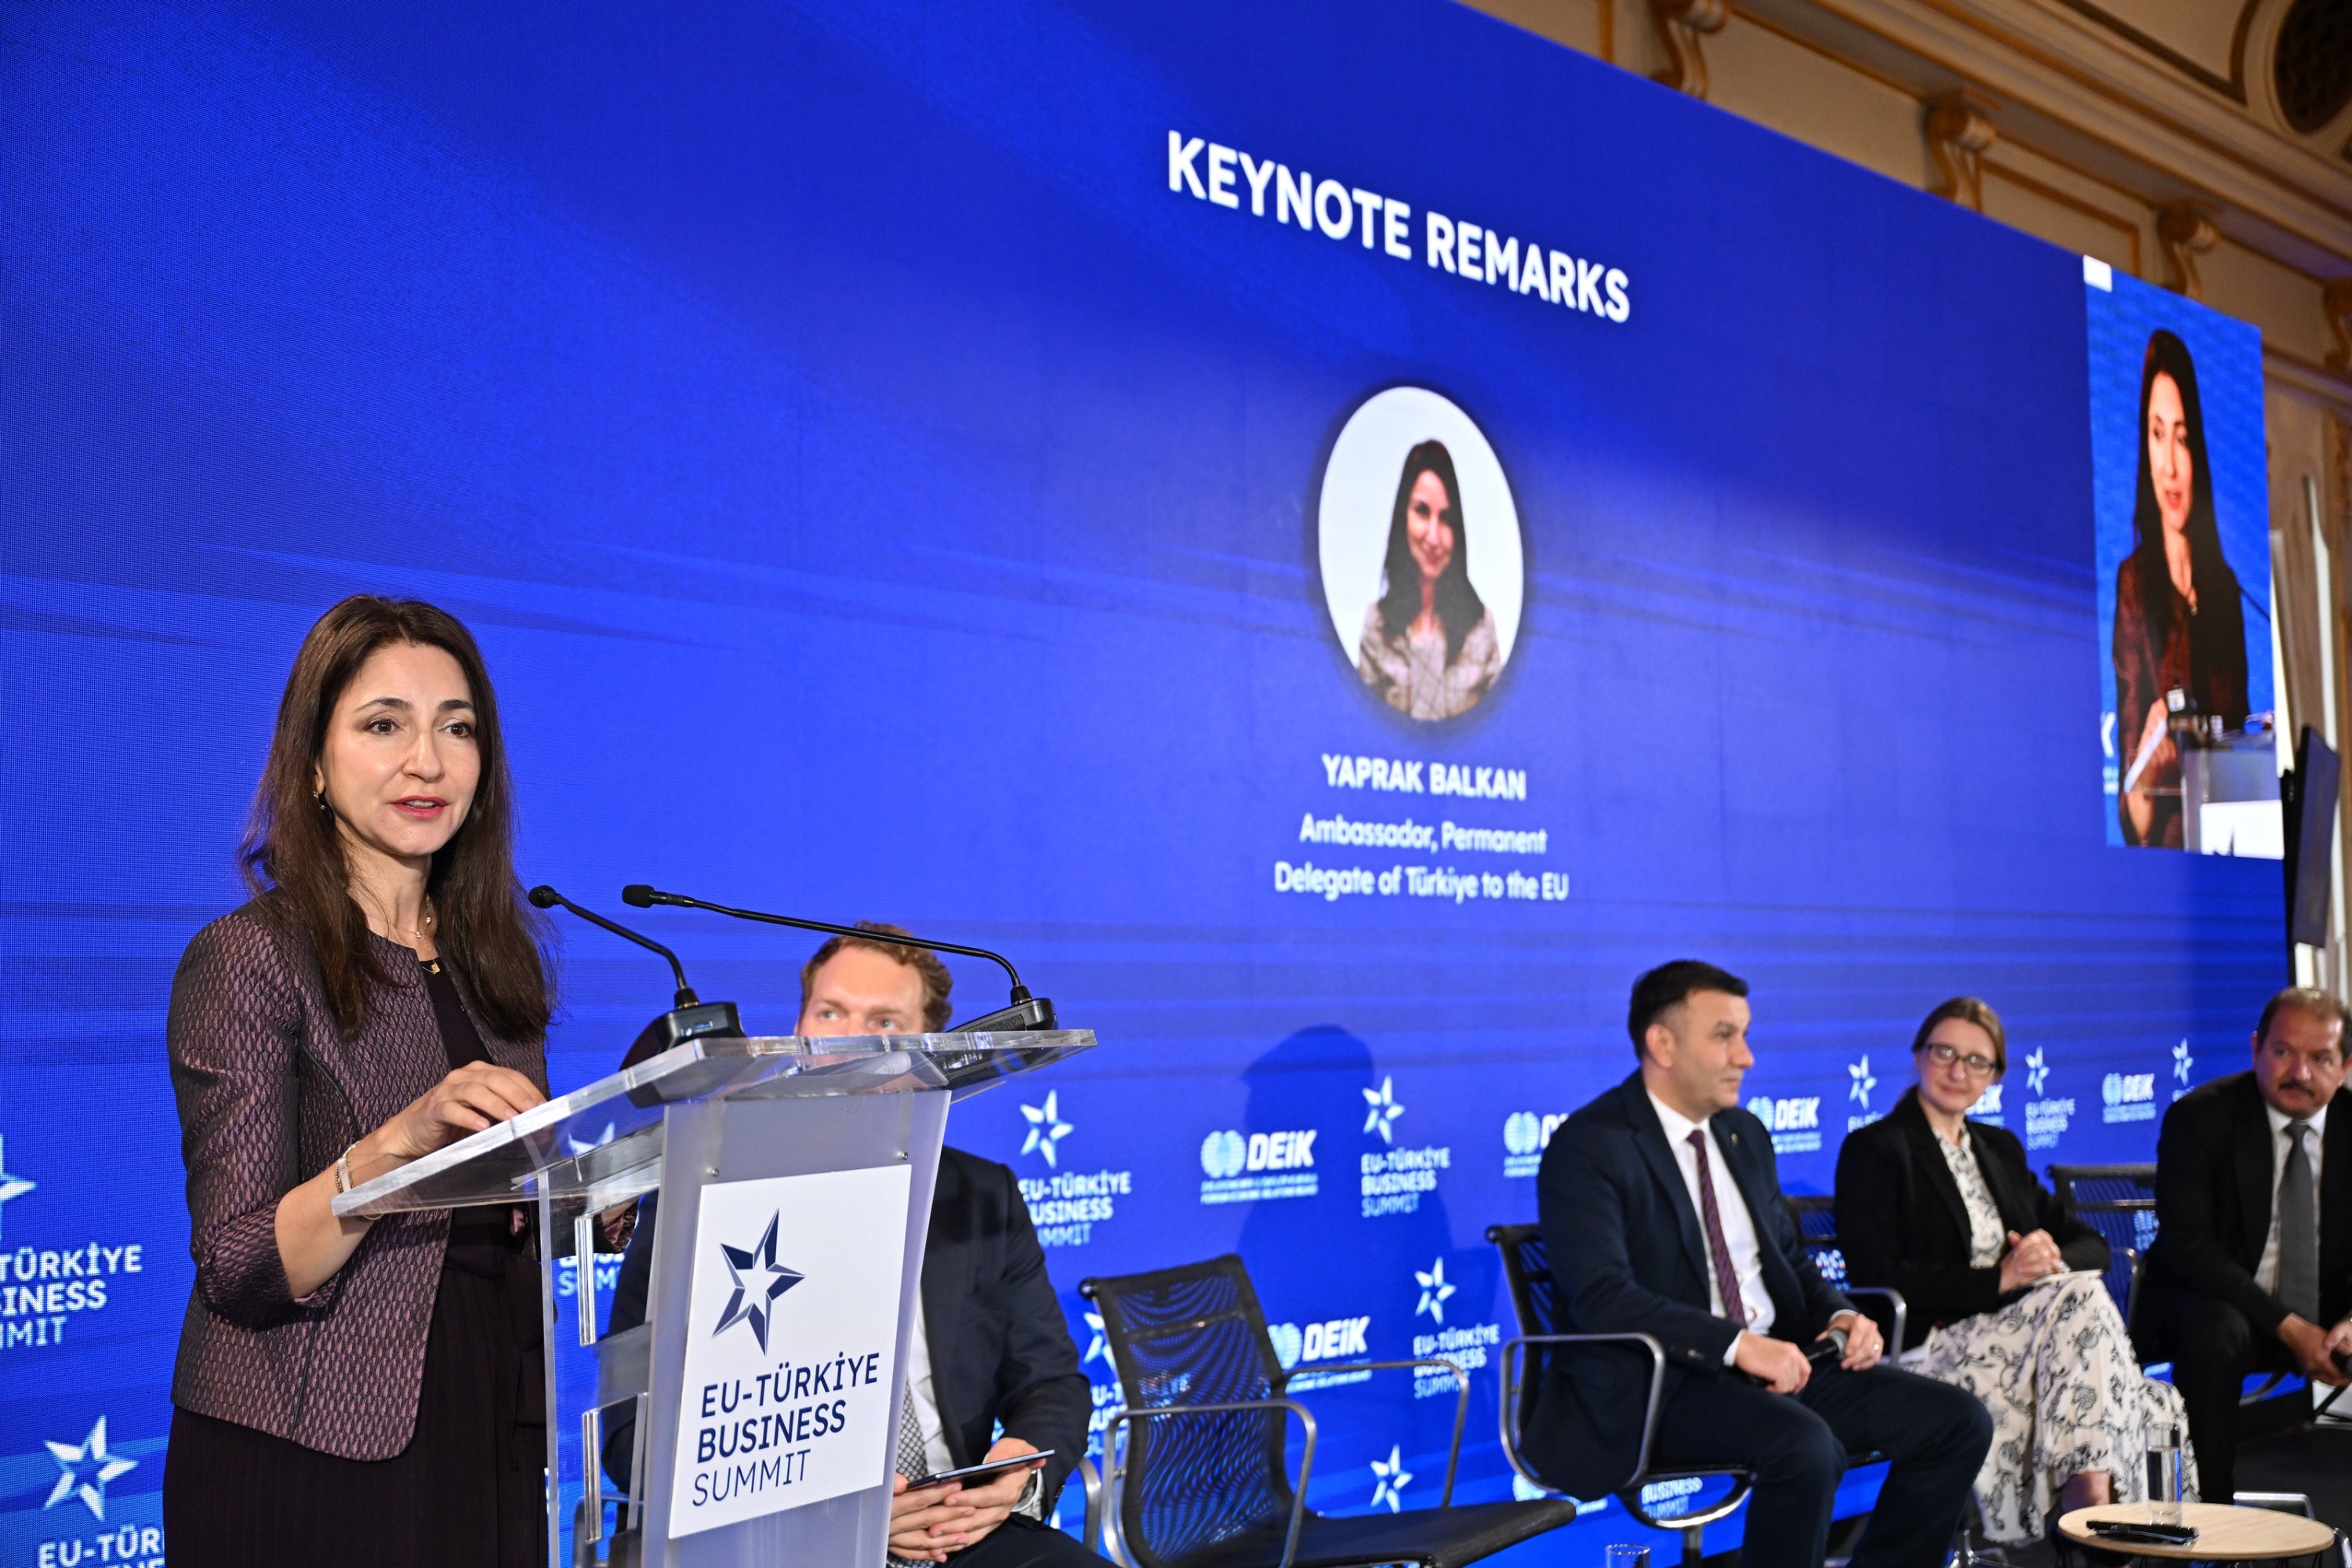
She dismissed claims that third-country goods would enter the EU through Türkiye as an “urban myth,” saying Türkiye will not become a back door for circumventing the rules and that Turkish industry also suffers from unfair competition and overcapacity.
On public procurement, Balkan said a law passed in Türkiye in July contributes to the process toward an agreement with the EU, that Ankara wants negotiations to start as soon as possible, and that reciprocity will be ensured. She added that senior executives of European carmakers have themselves lobbied for Türkiye’s inclusion.
Future cooperation, she said, should focus on joint research, advanced manufacturing, cleaner materials, batteries, circularity and skills. “Inward-looking attitudes and protectionism cannot be the solution,” she said.
Belgium: Türkiye can help reduce Europe’s dependencies
Belgian Foreign Minister Maxime Prevot also addressed the summit, saying Türkiye has an important role in helping Europe reduce its strategic dependencies, particularly in key industrial sectors.
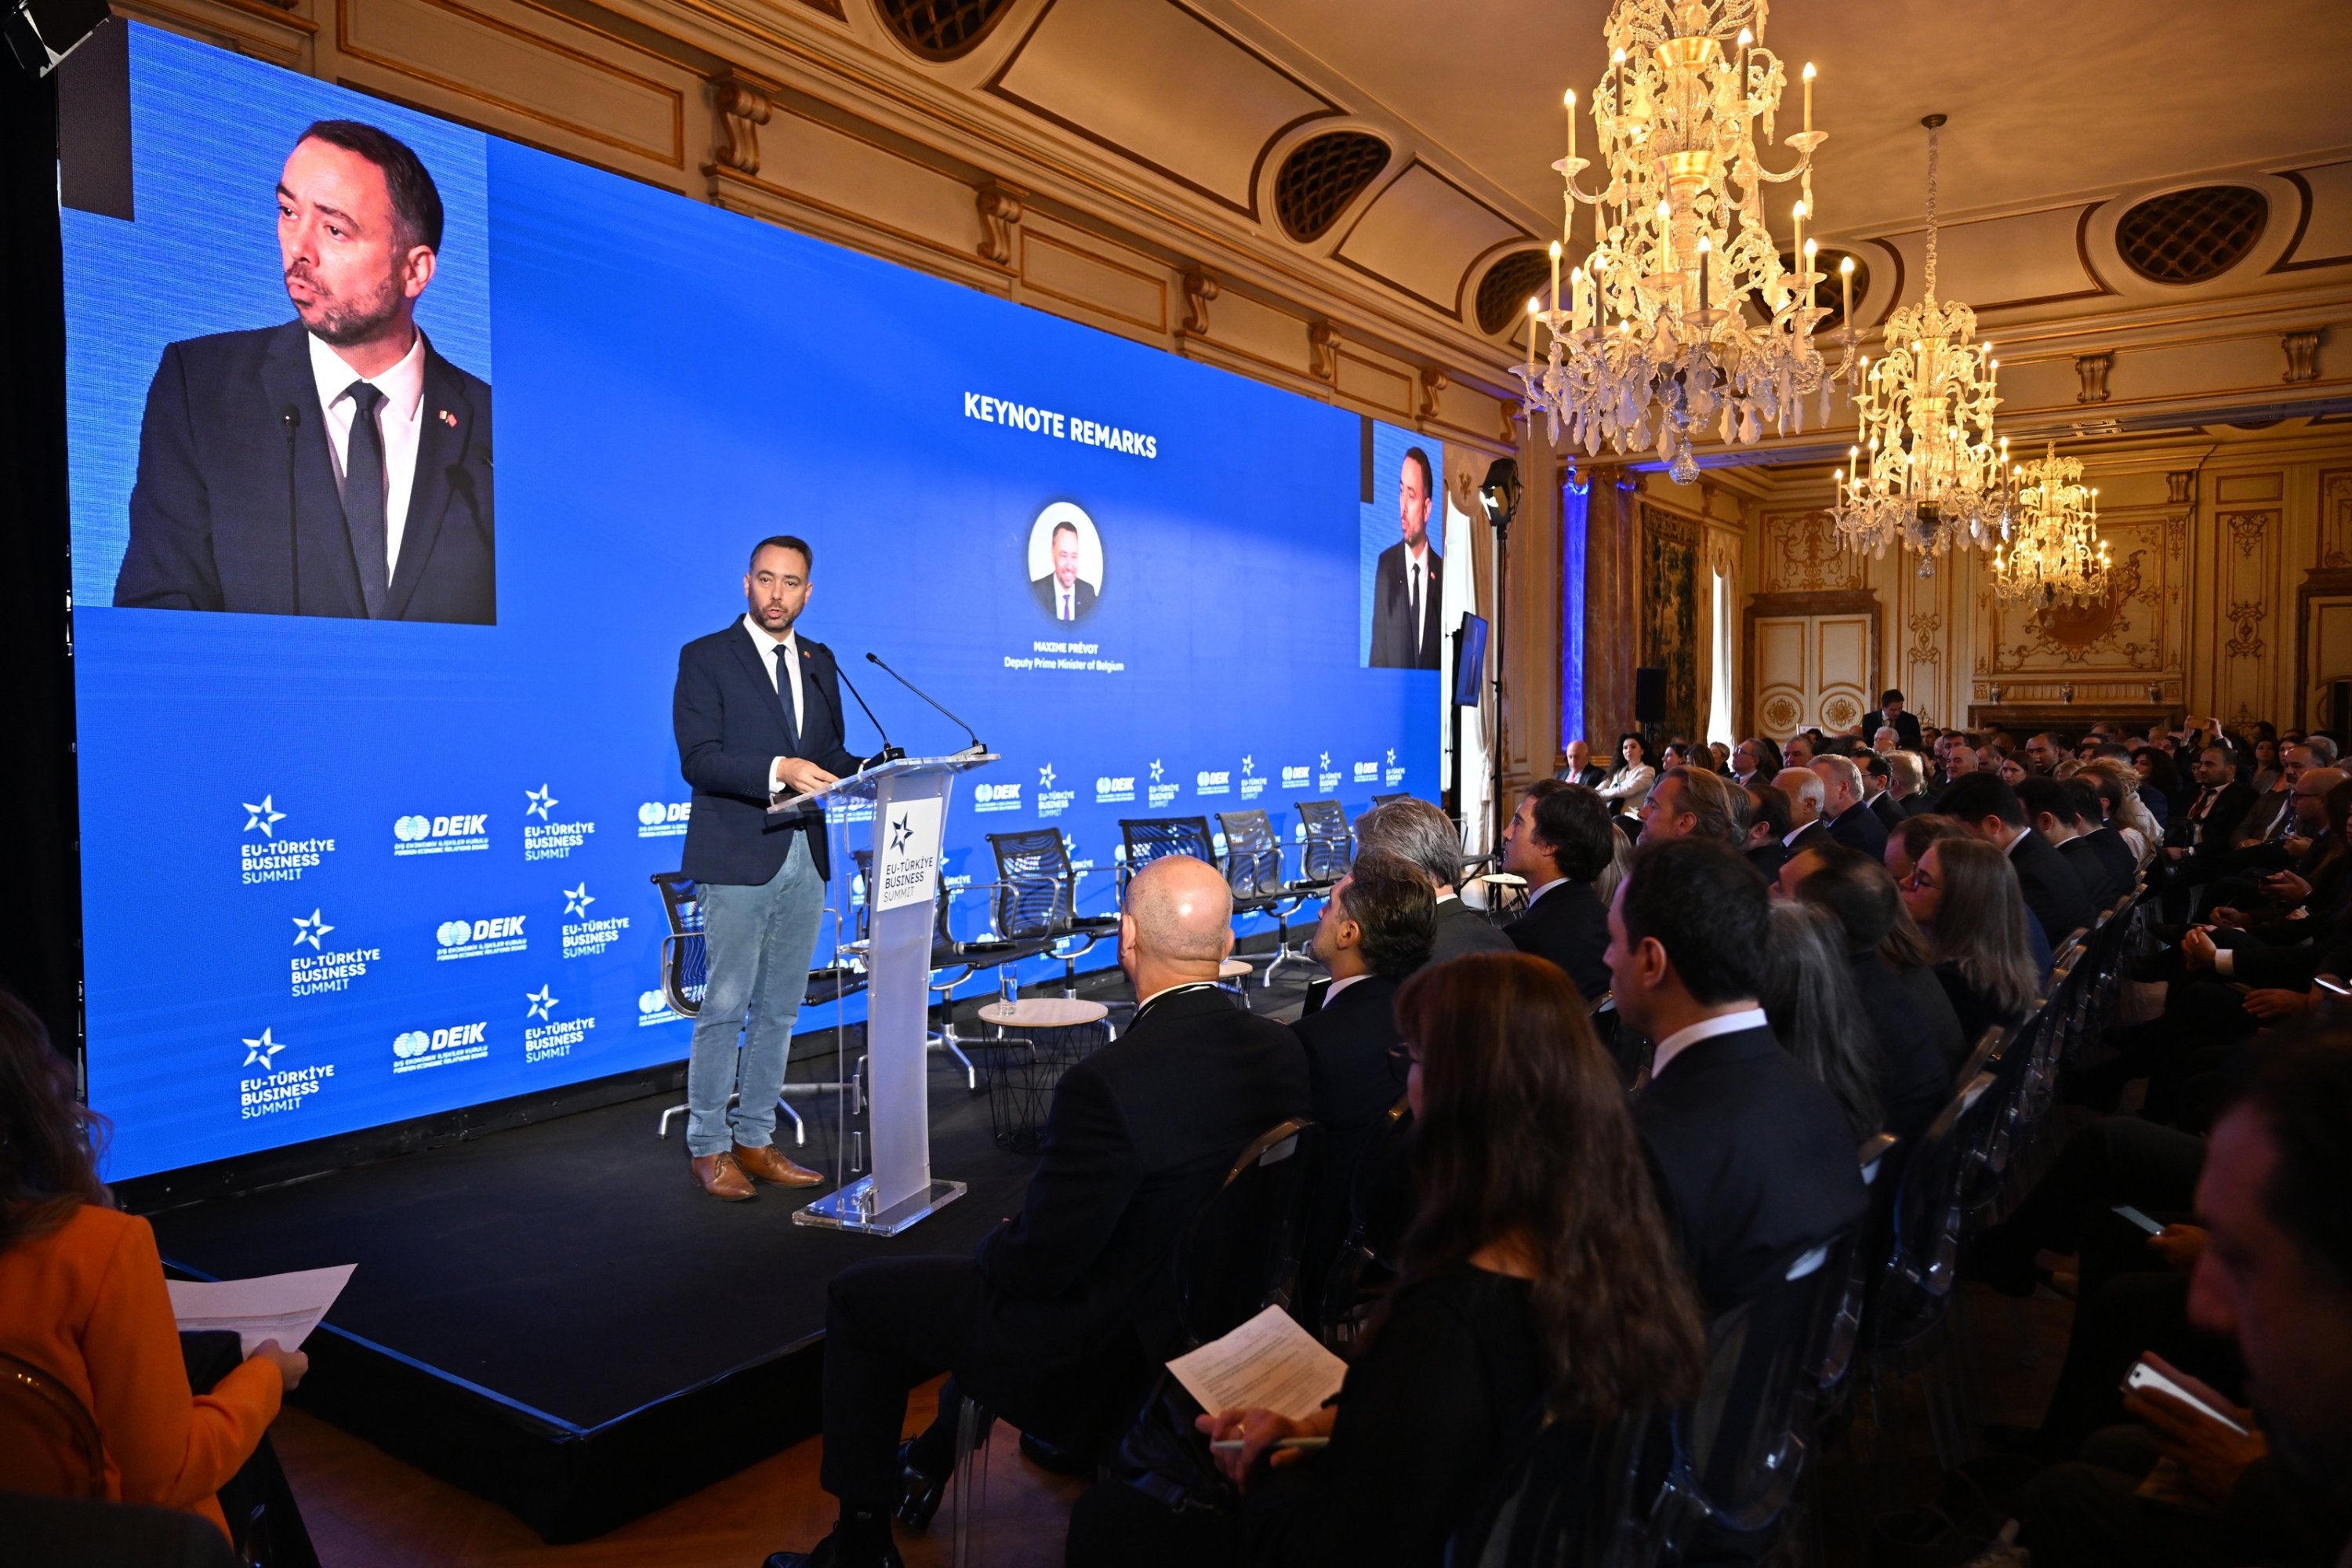
He said shifting global dynamics, the war in Ukraine and supply chain disruptions had made Europe increasingly aware of its economic vulnerabilities.
“Türkiye has an important role to play, not only as an industrial market but also as a gateway to markets in the wider region,” he said, stressing its manufacturing capacity, industrial expertise and links to neighboring markets.
European companies are increasingly seeking reliable partners closer to home as they reconsider where to manufacture and store their goods, Prevot said, and Europe should make the most of Türkiye’s proximity, especially in sectors where it needs to cut strategic dependencies.
He described Türkiye as a NATO ally, an EU candidate country and a major industrial economy connecting Europe, Asia and the Middle East, whose capabilities could make European supply chains more resilient. He called for stronger cooperation between Brussels and Ankara in economic security, defense, innovation, clean energy and digital technologies.
“Our economic relationship should no longer be limited to buying and selling goods. We should also be developing, producing, and investing together,” he said.
Prevot also backed modernizing the customs union, which he said has served both economies for around 30 years but needs to reflect changing global economic conditions.
Türkiye logged a current account surplus of $4.05 billion (TL 199.94 billion) in August, official data shared by the country’s central bank showed Tuesday.
Excluding gold and energy, the current account indicated a net surplus of $8.2 billion during the month, the Central Bank of the Republic of Türkiye (CBRT) said in its balance of payments data.
The surplus narrowed from $4.62 billion a year earlier as the goods deficit widened, while the services surplus increased.
The reading marked the second consecutive month in which the current account posted a surplus. Prior to that, the balance last posted a surplus in October 2025, when it stood at $477 million.
The country’s goods deficit reached nearly $3.75 billion in August, up from $2.8 billion a year earlier, the bank stated.
Meanwhile, the services surplus increased to $9.71 billion from $9.34 billion over the same period.
Travel revenues reached $7.28 billion, and transportation revenues reached $3.26 billion.
The primary income deficit edged down to $1.89 billion from $1.9 billion, while the secondary income deficit fell to $18 million from $21 million.
Direct investment saw a net inflow of $141 million in August, as nonresidents recorded a net inflow of $719 million.
Portfolio investment recorded a net outflow of $1 billion in August.
The country’s official reserves increased by $7.14 billion during the same period.
In the first eight months of 2026, Türkiye’s current account deficit widened to $31.5 billion from $19.67 billion in the corresponding period a year earlier.
The 12-month rolling deficit stood at $42.1 billion as of August, according to central bank data.
The International Monetary Fund (IMF) revised slightly upward its outlook for the world economy growth for this year, while also warning of growing risks from rising debt, including borrowing related to artificial intelligence.
The IMF says it expects the global economy to grow at a 3.1% pace this year.
That’s up from its July forecast for 3.0% growth and well below the 3.5% expansion in 2025. Growth in 2027 should rebound to 3.4%, it said in its latest Economic Outlook.
The report, released as world economic and financial leaders gather in Bangkok for the fall meetings of the IMF and World Bank, predicts that growth in the U.S. will remain steady at 2.3% in 2026 and 2027.
Collectively, advanced economies will grow 2.1% this year, up from 2.0% in 2025. But growth is forecast to slow to 1.9% next year, it said.
The forecasts are based on a nearly 41% increase in oil prices this year, at an average of $96 a barrel. Global inflation is foreseen at 4.7% in 2026 and falling to 4.1% next year.
They also are based on the assumption that shipments of oil and gas through the Strait of Hormuz will resume by March, and that the boom in AI demand will moderate.
The boom in artificial intelligence is offsetting damage from sharply higher prices for oil and gas, IMF economists say, but it also carries risks.
Its benefits are not shared equally: the U.S. and China account for more than three-quarters of net demand for imports of computer chips and other AI-related equipment, the report said.
“The outlook is highly uneven,” Silvana Tenreyro, the IMF’s director of research, told reporters in Bangkok.
Growth is increasingly concentrated, with 32 countries accounting for 95% of global growth, the report said. That compares with 54 countries as of April.
“The global economy is not simply slowing or accelerating; rather, growth is being reallocated across countries according to their exposure to the war-induced supply shock and AI-related demand strength,” it says.
Athanasios Vamvakidis, deputy director at the IMF’s Monetary and Capital Markets Department, said an AI-related correction in stock markets is just one of the risks. Rising bond yields are another evolving problem, along with cyberthreats that could disrupt financial systems, he said.
AI’s effects on employment are another key focus of the meetings in Bangkok, which IMF Managing Director Kristalina Georgieva described during an event Monday as “a slow moving tsunami, but a tsunami nonetheless.”
“The impact over time on jobs globally we estimate to be around 40% – jobs either augmented or downgraded or eliminated. And we are already seeing some of this impact,” she said.
Last week, the IMF chief urged countries both rich and poor to do a better job of improving their national finances, urging policymakers to do more to tame mounting levels of debt.
That’s especially true at a time of high borrowing costs, Tenreyro said.
Countries that are somewhat insulated from the energy shocks of the Iran war and that are benefiting from rapid adoption of AI are managing to keep growth on track.
Middle East contraction
But developing economies and emerging markets more vulnerable to higher costs for oil and gas will see growth slow to 3.7% this year from 4.5% in 2025, the report says. It forecasts they will regain momentum next year, expanding at a 4.4% annual pace.
The situation is much worse in the Middle East and Central Asia, where those regions’ economies are expected to contract this year before recovering to a 6.3% rate of growth in 2027.
The 21 European countries that share the euro currency are expected to grow by 1.1% this year and 1.2% in 2027.
China, the world’s No. 2 economy, is expected to expand 4.5% this year, down from 5% in 2025, in line with the government’s official target.
India is once again forecast to be the world’s fastest-growing major economy, advancing at a 7% clip, down from a sizzling 7.7% last year.
The IMF is a 191-nation lending organization that works to promote economic growth and financial stability and to reduce global poverty. At the meetings in Bangkok, finance ministers and central bank governors will assess the state of the world economy and discuss strategies to support financial stability and sustained growth.


-
 Economy2 days ago
Can diesel prices fall after Trump-Russia deal?
-
 Politics2 days ago
Türkiye-France defense cooperation spark concern in Greek media
-
 Politics2 days ago
Türkiye presses Greece to hand over FETÖ members, crime bosses
-
 Economy2 days ago
Tehran’s once-bustling bazaar struggles as war dampens demand
-
 Economy2 days ago
Top oil execs drop from major event schedule after Riyadh attacks
-
 Sports2 days ago
Bezzecchi wins Indonesian GP to hand Martin championship lead
-
 Economy1 day ago
Türkiye says 17 funds settled, eyes Atlas deal this week
-
 Sports2 days ago
Deadly Houthi strike on Riyadh airport draws int’l condemnation