Economy
Türkiye considers updating taxes in line with inflation targets: Şimşek

The Turkish government is considering updating tax values by taking into account the inflation targets, a top economy official said Thursday, also pointing to expectations for the disinflation trend to continue.
In a presentation to Parliament’s Planning and Budget Commission, Treasury and Finance Minister Mehmet Şimşek said the government anticipated that disinflation would continue in the coming period, driven by tight monetary policy and supportive fiscal policy.
Starting his speech by addressing developments in the global economy, he emphasized that they expect the global economic situation to take a more favorable course for Türkiye.
He went on to highlight the gains achieved in the last two years thanks to their program, adding: “We have made significant progress in strengthening macro-financial stability, which is one of the primary objectives of our program, and improving our resilience to shocks.”
He also noted that reserve adequacy according to international standards has been ensured, stating that from May 2023, gross reserves increased by $87 billion, and net reserves, excluding swaps, increased by $112.6 billion.
“We are successfully managing the exit from foreign exchange-protected deposits (KKM),” Şimşek further said, referring to a scheme adopted in 2021 that aimed to counter a fall in the lira and protect deposits by covering depreciation costs.
Following a shift to more conventional macroeconomic policies back in 2023, the authorities placed a focus on discontinuing the scheme.
“As of Oct. 24, we expect the balance, which has fallen to TL 171 billion ($4.05 billion), to drop below TL 5 billion by the end of the year. With the increased confidence in Turkish lira assets, the share of the Turkish lira in total deposits reached 59.8%,” said Şimşek.
Furthermore, explaining that they have reduced macroeconomic imbalances to make the gains from the program permanent, he said they have eliminated the current account deficit “as a source of concern,” citing achieving significant improvement.
“The ratio of the annualized current account deficit to national income, which was 5% in the middle of 2023, decreased to 0.8% in 2024,” he added.
“We foresee that this ratio, which is 1.3% as of the second quarter of 2025, will remain at sustainable levels with an average of 1.2% during the Medium-Term Program (MTP) period.”
Similarly, he said that along with the improvement in current balance, they foresee that the gross external financing need, which he said was 23% as a ratio to national income in June 2023, will decrease to approximately 17% by the end of this year.
‘Disinflation continues’
“Although temporarily slowed by seasonal effects, the disinflation process continues,” the minister noted.
“Annual inflation decreased by 15.7 percentage points in October compared to the same month last year, reaching 32.9%,” he added.
Official data released earlier this week showed inflation easing following an uptick in September and also reaching its lowest level since late 2021.
“We anticipate that the disinflation process will continue in the coming period with tight monetary policy, supportive fiscal policy, prices managed and guided within budgetary limits, aligned with targets, and supply-side measures, particularly social housing.”
Şimşek also stated that they are considering setting lower tax and fee updates, taking into account inflation targets rather than the revaluation rate, in line with budgetary constraints. He added that they will continue to implement policies aimed at establishing price stability in a coordinated and determined manner.
Highlighting the ongoing moderate trend in economic activity, he further said: “We expect moderate growth similar to 2024 in 2025. We foresee that the growth path will support disinflation during the MTP period.”
He also suggested that employment increased by 1.1 million people during the program period.
“Due to the weak trend in labor force participation, the unemployment rate remained in single digits. To revive the weak production, especially in labor-intensive sectors and to maintain employment, we will continue to increase our support for the real sector,” Şimşek said.
Addressing budgetary developments, he said they expect the budget deficit to the national income ratio to be 3.6% in 2025. He indicated that the upward revision of the 2025 budget deficit from 3.1% as predicted in the MTP last year is mainly due to some tax revenues falling short of expectations.
Also evaluating taxation, he said their aim in tax audit is not to impose penalties but to inform taxpayers and increase voluntary compliance.
“We completed our work on the audit standards to be applied in tax examinations aimed at protecting taxpayer rights, and we will publish them in the coming days,” he maintained.
“Our fight against informality is yielding results. We have achieved significant increases in the number of returns and declared incomes. This year, 473,000 taxpayers filed returns for the first time,” he added.
Şimşek also pointed out that as of October, they have secured long-term and favorable financing of approximately $13.6 billion from multilateral investment banks for infrastructure, transportation, health, combating natural disasters, environment, energy, and supporting the real sector.
“This amount is the highest achieved on an annual basis,” he added.
Several top energy executives have been dropped from the schedule of a major summit in Riyadh, as Saudi authorities pressed ahead with the event Monday despite deadly attacks on the capital claimed by Yemen’s Iran-aligned Houthis.
The chief executives of ExxonMobil, TotalEnergies, Shell, Chevron and BP had all been expected at the WPC Energy Congress, which began on Sunday, but were no longer on the agenda that conference organizers released early Monday.
“To everyone who traveled to Riyadh, thank you,” said Saudi Energy Minister Prince Abdulaziz bin Salman, who opened Monday’s session of the gathering for energy policy and industry.
“You know this country is safe and that we hold your protection at whole heart…Our gathering here does not mean the risk is gone.”
Prince Abdulaziz said the events of recent weeks were serious and that the kingdom’s response must be “equally serious.”
The strikes are a blow to Vision 2030, Saudi Arabia’s multi-billion-dollar program to diversify the economy away from oil, modernize society and position the kingdom as an investment and tourism hub.
Hosting international events is a priority of the program, which was already facing delays and recalibrations. Prince Abdulaziz said the kingdom must remain focused on the decades ahead and Vision 2030 must continue.
The WPC Energy Congress was originally scheduled for April of this year, but was postponed after the U.S. and Israeli war on Iran began in late February. Saudi Arabia was named host in October 2022, the first time the event, first held in Britain in 1933, has been held in the kingdom.
Chief executives of major energy companies are a regular fixture at WPC Energy events and had been scheduled to speak on stage this week about global oil and gas markets, energy security and the energy transition.
A BP spokesperson said the company had “made every effort to participate” in the conference. “Unfortunately, due to travel disruption, we are unable to be there in person. We greatly value our long-standing partnerships across the region.”
The WPC Energy Congress is taking place this week at a conference center some 10 kilometers (6 miles) from Riyadh’s international airport, which has been attacked four times in the last week.
One person was killed and nearly a dozen hurt in a new attack on the airport on Sunday evening, Saudi authorities reported, a day after a strike claimed by Houthis killed 13 people and wounded more than 300, the deadliest attack in the kingdom in more than a decade.
Upcoming midterm elections in the U.S. stand as a main reason behind the Trump administration’s sudden announcement that Russian diesel would be released immediately to American and global markets, analysts and critics say.
On Friday, U.S. President Donald Trump said he concluded a “highly successful discussion” with Russian President Vladimir Putin and noted it was agreed that Russia would “immediately” supply over 300,000 tons of diesel fuel to the American and global marketplace.
“Another 500,000 Tons during the month of November, and 1,000,000 Tons immediately therafter,” he wrote in a post shared on his Truth Social.
Separately, the U.S. Treasury Department has shared a notice and issued a temporary exemption from sanctions against Russia, permitting the sale, supply, unloading and import of Russian diesel until April 7, 2027.
Russian Deputy Prime Minister Alexander Novak also announced the immediate lifting of Russia’s ban on diesel exports, according to the state news agency Tass.
Record diesel prices
The prices of diesel reached record highs in the U.S., and many advanced economies, including the U.K., France and Germany, in recent weeks amid the ongoing war between the U.S. and Iran in the Middle East and Ukraine’s attacks on Russian energy infrastructure.
U.S. national average diesel prices reached $6.27 per gallon as of October, according to AAA Fuel Prices.
However, with the midterm elections next month, critics argue that the amount of supply volume shared by Trump is insufficient, also suggesting that Russia is likely unable to produce as much at its refineries impacted by Ukrainian attacks.
Before the reported lift on the ban, Russian authorities had recently extended the ban on exports of diesel untill end of October amid the domestic crunch in supplies – a rare case for the country, which before the invasion of Ukraine was one of the top global energy suppliers.
Can deal ease pressure on prices?
The U.S.-Russia deal, which has led to a rebuke by Ukraine and its European allies, such as Germany, raised a question: could it actually help alleviate the recent cost pressures the customers across Europe and the U.S. have been facing?
Following Trump’s announcement, diesel futures in fact dropped, trading about 4.5% lower at $4.67 per gallon. Data from the NY Harbor chart, displaying costs of futures on Oct. 9, showed that the November price dropped by 4.1% to $4.68.
Still, it is unclear how it would reflect on crude oil prices, with tensions in the Middle East and lately between Saudi Arabia and Houthi rebels also weighing on the outlook.
Diesel is a refined product, and additional shipments do not automatically increase crude production.
WTI price settled Friday at $91.85 per barrel, up 0.39%, while Brent crude closed at $104.72, gaining 0.42%. Both benchmarks finished higher despite the initial reaction to Trump’s announcement.
But since diesel is used in logistics and agriculture and coupled with the recent G-7 decision to release additional emergency stockpiles, any drop in prices would be welcomed by farmers and companies, which have voiced dissatisfaction with the current level of prices.
The U.S.-Russia deal was also criticized by Ukrainian President Volodymyr Zelenskyy, after which Trump said the war-torn country needed a new president.
“Allowing Russia to sell petroleum products is an investment in the war, which must be ended, not prolonged,” Zelenskyy wrote on Telegram on Friday evening.
German Education Minister Karin Prien on Sunday also criticized Trump over his call for a new Ukrainian president amid the recent U.S.-Russia diesel agreement.
“For a few liters of diesel. What a moral bankruptcy,” Prien said on X in response to Trump’s remarks.
Trump on Saturday called for Ukraine to “get a new president,” accusing Zelenskyy of repeatedly failing to reach a deal to end the war with Russia.
“I suggest they get a new leader who can make a deal, because he could have made many deals that, for some reason, he never does,” Trump said.
Meanwhile, Germany reaffirmed its commitment to sanctions against Russia on Saturday following the Trump-Putin agreement, according to German media.
The bank accounts of 214 individuals and companies have been frozen as part of the ongoing investigation into funds and asset management companies following the liquidation order by Turkish authorities, with TL 187 billion (about $3.8 billion) in earnings under scrutiny, according to a Sunday report by Sabah newspaper.
As part of an ongoing investigation into investment funds in Istanbul, authorities identified 141 individuals and 73 companies, 214 in total, who reportedly earned more than TL 100 million from three funds, the report suggested.
The Istanbul Chief Public Prosecutor’s Office is said to have sent the list of these individuals and companies to the Savings Deposit Insurance Fund (TMSF), which has begun formally notifying them about the return of their earnings, it added.
Court orders have also imposed travel bans preventing the relevant individuals and company executives from leaving Türkiye.
Moreover, investigators are reportedly tracing where the money went after it was withdrawn from the investment funds.
On Friday, another report said that Turkish prosecutors have identified 214 individuals and companies they say made a combined TL 187.65 billion from three of the investment funds at the center of the country’s fund turmoil.
The Sunday report names Melis Sütşurup Sandal, the wife of Turkish singer Mustafa Sandal.
According to the investigation documents cited in the report, she reportedly earned TL 2.355 billion from Tera’s TLY investment fund, placing her first among the individuals listed.
Her total withdrawals from fund accounts during 2026 reportedly amounted to nearly TL 15.8 billion. As of Sept. 16, 2026, her fund account reportedly held approximately TL 250 million.
The Financial Crimes Investigation Board, known as MASAK, has also begun examining the bank accounts of people who transferred money from their fund investments into their personal bank accounts. Investigators are said to be preparing detailed reports to determine where the approximately TL 187.65 billion ended up.
Authorities launched a sweeping investigation and market intervention last month after suspected price manipulation in a number of thinly traded stocks triggered heavy losses and redemption pressures at investment funds.
The Capital Markets Board (SPK) halted trading in more than 130 funds on Sept. 17. Nearly half a million investors have been affected.
India targets increasing its steel capacity to 604 million metric tons by 2047 from around 220 million tons at present, according a draft steel policy for public consultation released late on Saturday.
Reuters reported last week, citing the draft document, that the policy lays out plans to cut sector emissions and shore up access to iron ore and coking coal, key raw materials, to meet anticipated demand.
The policy aims to cut the sector’s average carbon-emission intensity to around 1.54 tons of carbon dioxide per ton of crude steel by 2047 from the current 2.54 tons, in line with India’s net zero emission goal for 2070, according to the draft document.
The steel ministry expects iron ore demand at 772 million tons and plans to secure access to high-grade reserves by pursuing foreign assets and joint ventures, the document said.
The ministry also expects coking coal demand to reach 236 million tons, the document said, with the government planning to diversify its sourcing via “strategic global outreach” and acquire overseas assets.
Türkiye generated nearly $823 million from vegetable exports from January through September, up 10% from a year earlier, according to a report on Saturday.
Some 651,087 tons of tomatoes, peppers, cucumbers, zucchini, and other vegetables grown in Türkiye found buyers in international markets, according to information compiled by Anadolu Agency (AA) from data provided by the Türkiye Exporters Assembly (TIM).
Fresh vegetable export revenues, which amounted to some $749.15 million between January and September last year, increased by 10% during the same period this year, reaching $822.68 million.
Tomatoes ranked first among fresh vegetable exports, generating $304.16 million in revenue. Peppers followed, bringing in $275.48 million in export earnings.
Compared with the same period last year, revenue from tomato exports increased by 4%, while revenue from pepper exports rose by 29%. Together, these two products accounted for approximately 70% of total fresh vegetable export revenues.
During this period, Türkiye earned $61.38 million from cucumber and gherkin exports, $57.44 million from zucchini exports, and $39.64 million from carrot and radish exports.
Romania largest export market
Romania ranked first among Türkiye’s fresh vegetable export markets, purchasing products worth approximately $147 million.
Germany followed with $132.7 million, while Russia ranked third with $76 million.
During the same period, Türkiye exported fresh vegetables worth $55.48 million to Bulgaria, $49.96 million to Ukraine, and $47.8 million to the Netherlands.
Hayrettin Uçak, the chair of the Turkish Fresh Fruit and Vegetable Exporters’ Associations Sector Board, told Anadolu Agency (AA) that they viewed the increase in export revenues positively, despite changing conditions throughout the vegetable production season.
“Our exports increased by 10% over the previous year during the first nine months, and this success in exports makes us happy,” Uçak said.
“Neighboring and nearby markets are important for our vegetable exports. We need to closely monitor consumer expectations and shopping habits in the European market. Being able to supply buyers with the products they want, in suitable packaging and on time, plays a decisive role in commercial relationships. In this respect, we consider the growth in exports to Romania and Germany particularly important,” he added.
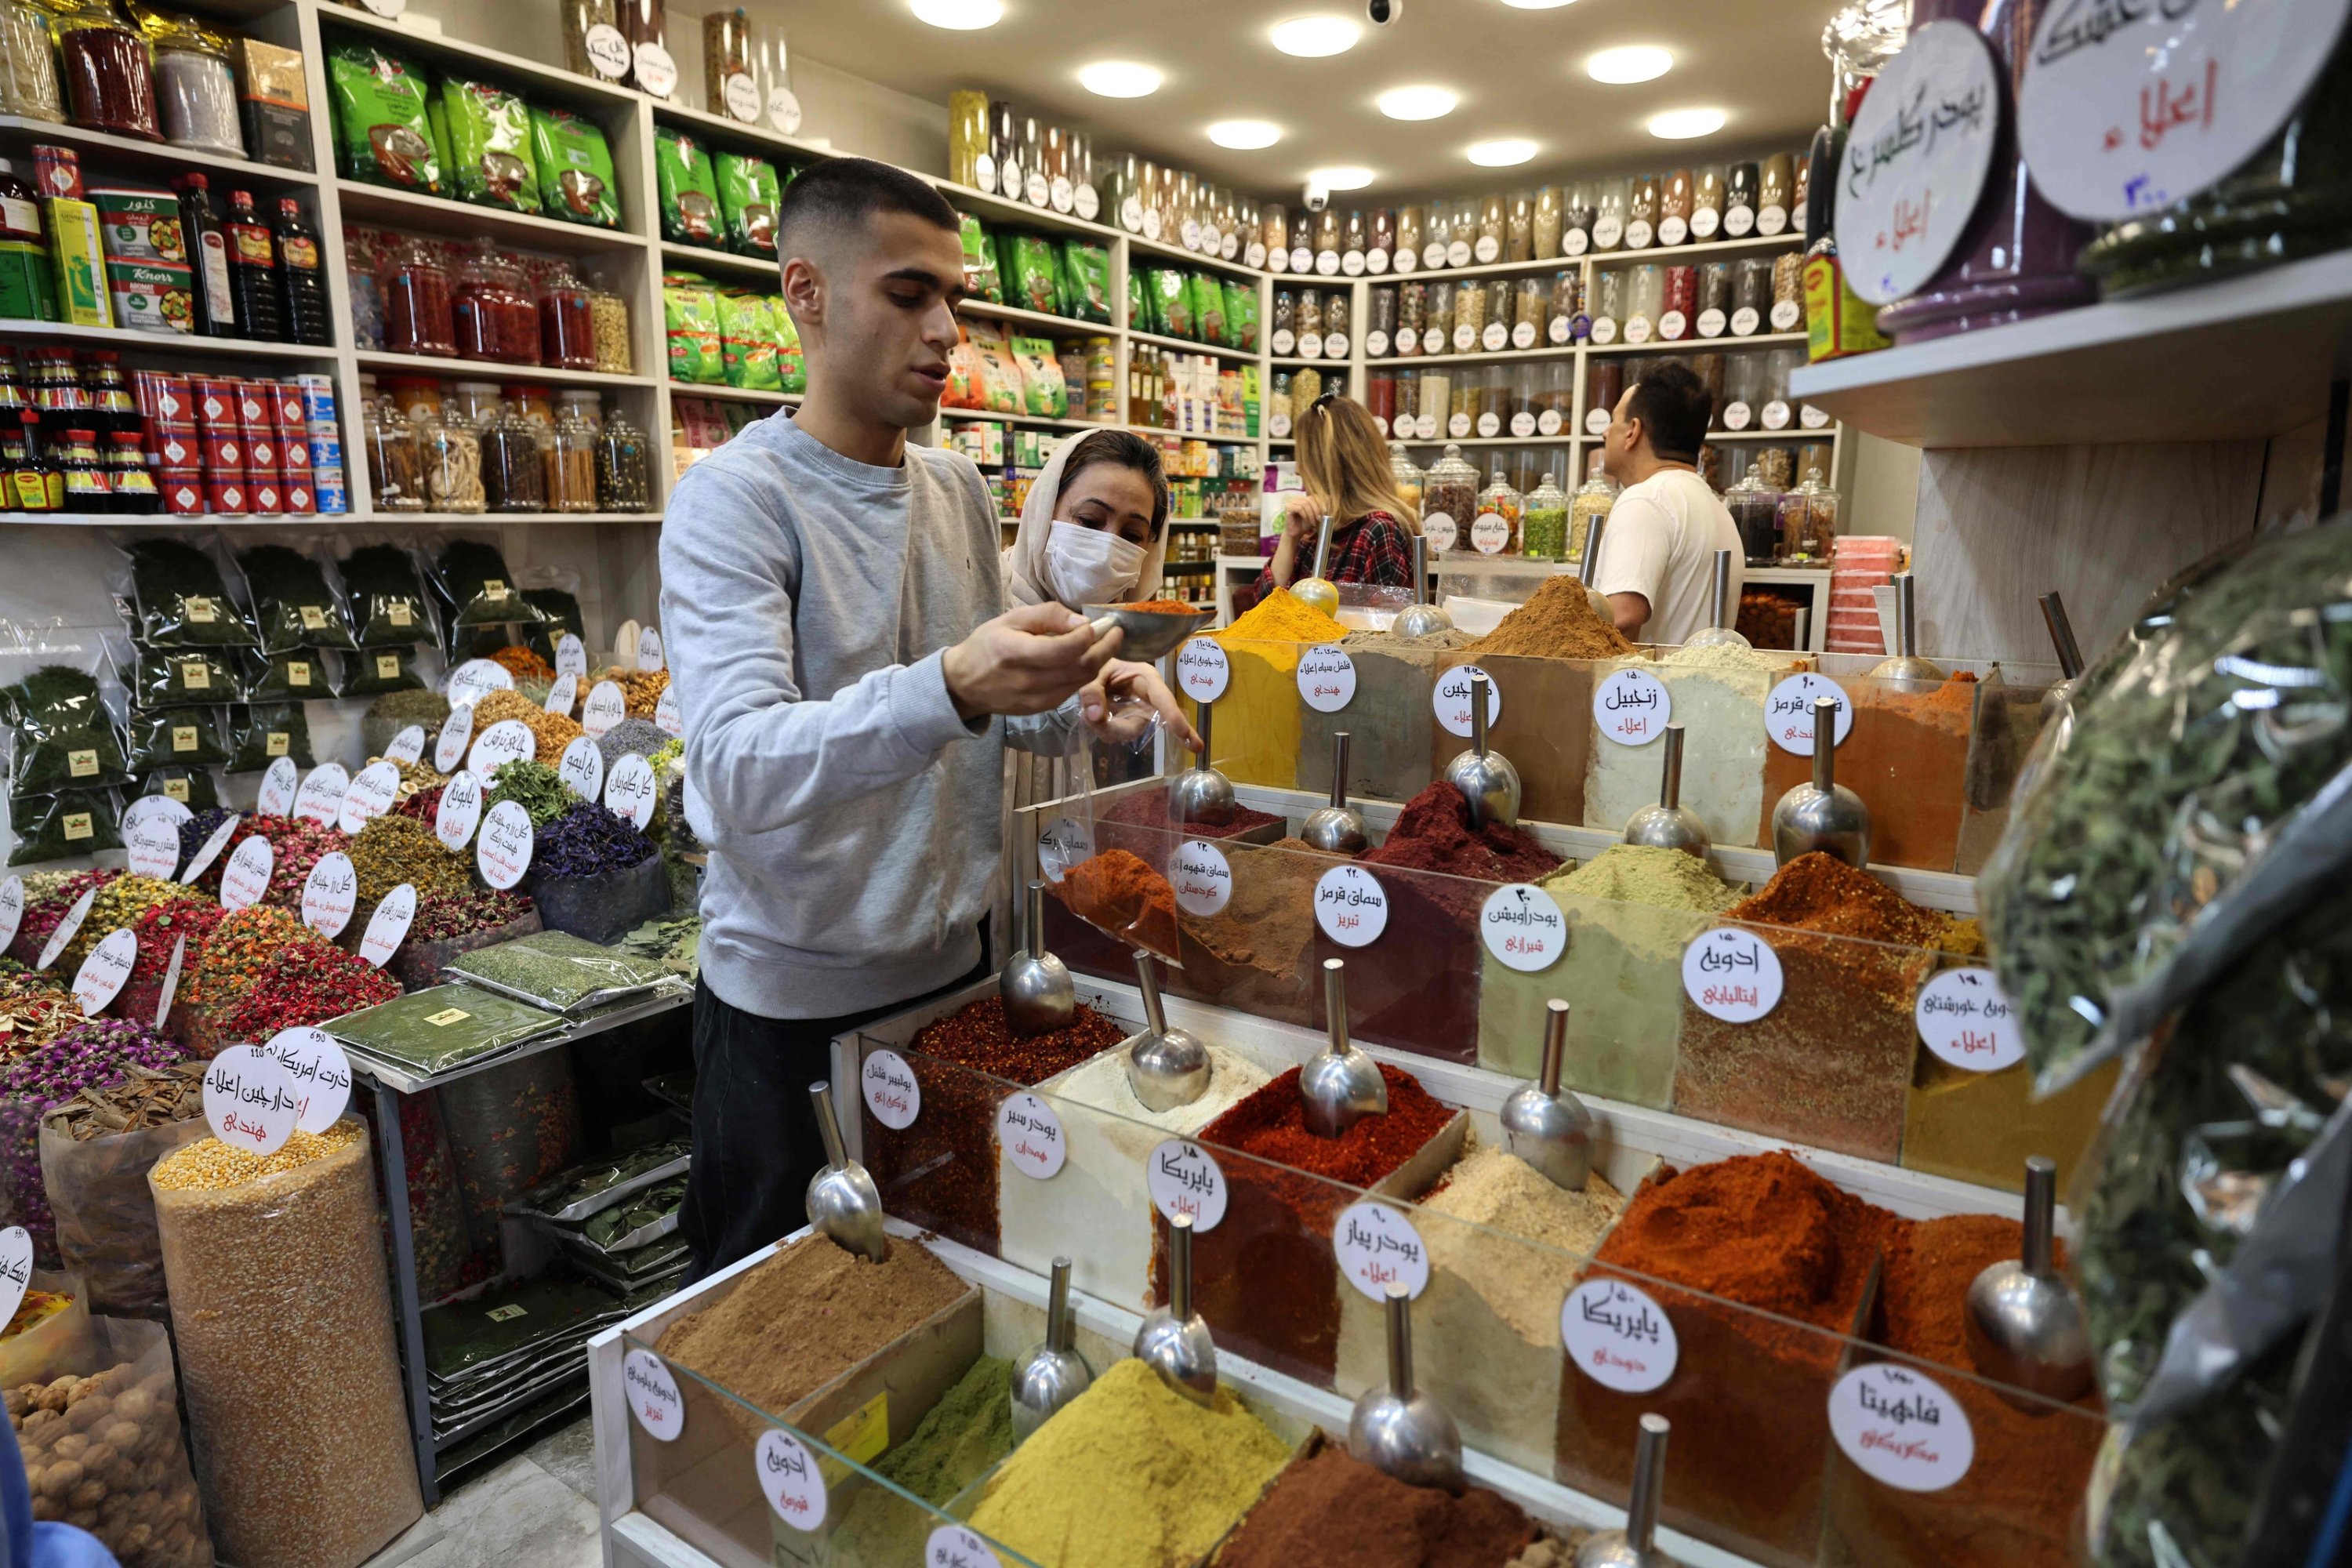
The scent of fragrant herbs and spices drifts through Tehran’s bazaar, but business is far from brisk. Shopkeeper Nasir says locals who once purchased nuts by the kilo are buying less as the U.S.-Iran war-driven price increases squeeze demand and push traders to the brink.
The marketplace in the Iranian capital’s north would usually be abuzz with customers, but shops now sit mostly empty with only small numbers of people walking its old narrow paths, a jarring shift for the sellers shouting to promote their goods.
“There used to be customers who bought 2 to 5 kilograms. Now, they’re down to buying one kilogram or half a kilogram,” said the 61-year-old.
“Prices are truly high. We all know it, and it would be a lie to say otherwise.”
Nasir called on authorities to stabilize the currency so businesses could plan ahead.
“We’re left in limbo; everyone is,” said the fruit and nut seller.
“They need to stabilize the dollar exchange rate.”
Iran’s economy has been battered by years of sanctions, but the conflict that began in February with U.S.-Israeli attacks and an American blockade of the country’s ports has put extra strain on daily life.
Rising inflation, nearly 90% year-over-year in September according to official figures, and erratic currency exchange fluctuations have driven up the cost of everyday items. Food prices have more than doubled since last year.
At the bazaar, a historic covered market in Tehran’s Tajrish square, locals surrounded by Iranian flags and Persian signage try to escape the economic gloom, scanning sweets, jewellery, traditional garments and cuts of meat before their weekend begins.
In an alley, a street artist plays a guitar while another drums his hands on a box to draw tips from passersby.
‘Just need stability’
But across the commercial district, many struggle to see a future for their businesses.
“It is a desperate, last-ditch struggle. Manufacturers are going bankrupt, laying off staff and closing shops, and the impact inevitably reaches us,” said Ali Nowruzi, 36, who runs a sportswear shop in the bazaar.
The businessman now orders only a few items for display on his shop’s shelves to stop them from looking bare like his warehouse, which he says lies empty due to lack of demand.
“We have absolutely no plan for the future. When people don’t come to buy … it effectively spells bankruptcy for the business,” he said, citing rising rent and utility bills.
“We just need some stability.”
Many shoppers, whose purchasing power has weakened since the outbreak of war, are seen leaving the bazaar without buying anything.
Azadeh, a 45-year-old woman currently out of work, says she just goes there to “watch the shops”.
Mounting pressure over the war saw Iran’s gross domestic product (GDP) contract 10.1% year-over-year between late March and late June, according to official figures.
The rial traded at around 2.7 million to the dollar on the unofficial market in the past week, compared with about 1.7 million before the war.
The minimum monthly wage that stood at around $120 a year ago has fallen to $65.
The country’s economy minister has rejected predictions of an imminent economic collapse, accusing Iran’s foes of trying to fuel public anxiety and drive up exchange rates.
Prices ‘skyrocketed’
Azadeh offers a price comparison of a kitchen cloth bought several months ago for 22 cents. She says that the item now costs $1.10, five times more.
“It shows that prices haven’t just gone up; they’ve truly skyrocketed,” she said.
She has stopped buying some fruits and says she can no longer afford holidays.
“We aren’t meant to just exist, we’re meant to actually live, right?” she asked.
Car mechanic Mojtaba Rezaei says his customers have “dropped to a 10th of what it was” because “goods now cost two or three times as much.”
“I actually feel embarrassed telling prices to customers. People just come in, ask the price, and leave,” the 57-year-old told Agence France-Presse (AFP) at the bazaar.
“So many things – buying clothes, going out for leisure, dining at restaurants – have all been cut out of our lives.”


-
 Economy3 days ago
Türkiye’s Kalyon PV to build solar panel factory in US
-
 Economy3 days ago
Türkiye identifies 214 people, firms made about $3.8B from troubled funds
-
 Politics3 days ago
Türkiye rules out ops against Houthis, vows to help Saudi defense
-
 Politics3 days ago
Türkiye, France deepen military ties under new road map
-
 Economy3 days ago
Türkiye extends high-speed rail network to EU border
-
 Politics3 days ago
Türkiye’s Akıncı drones extend gendarmerie’s reach across country
-
 Economy3 days ago
European firms called to expand partnerships with Turkish contractors
-
 Politics3 days ago
Türkiye cooperates with EU for foreign nationals in need