Economy
Türkiye’s Şimşek joins global finance chiefs’ talks amid Mideast shock

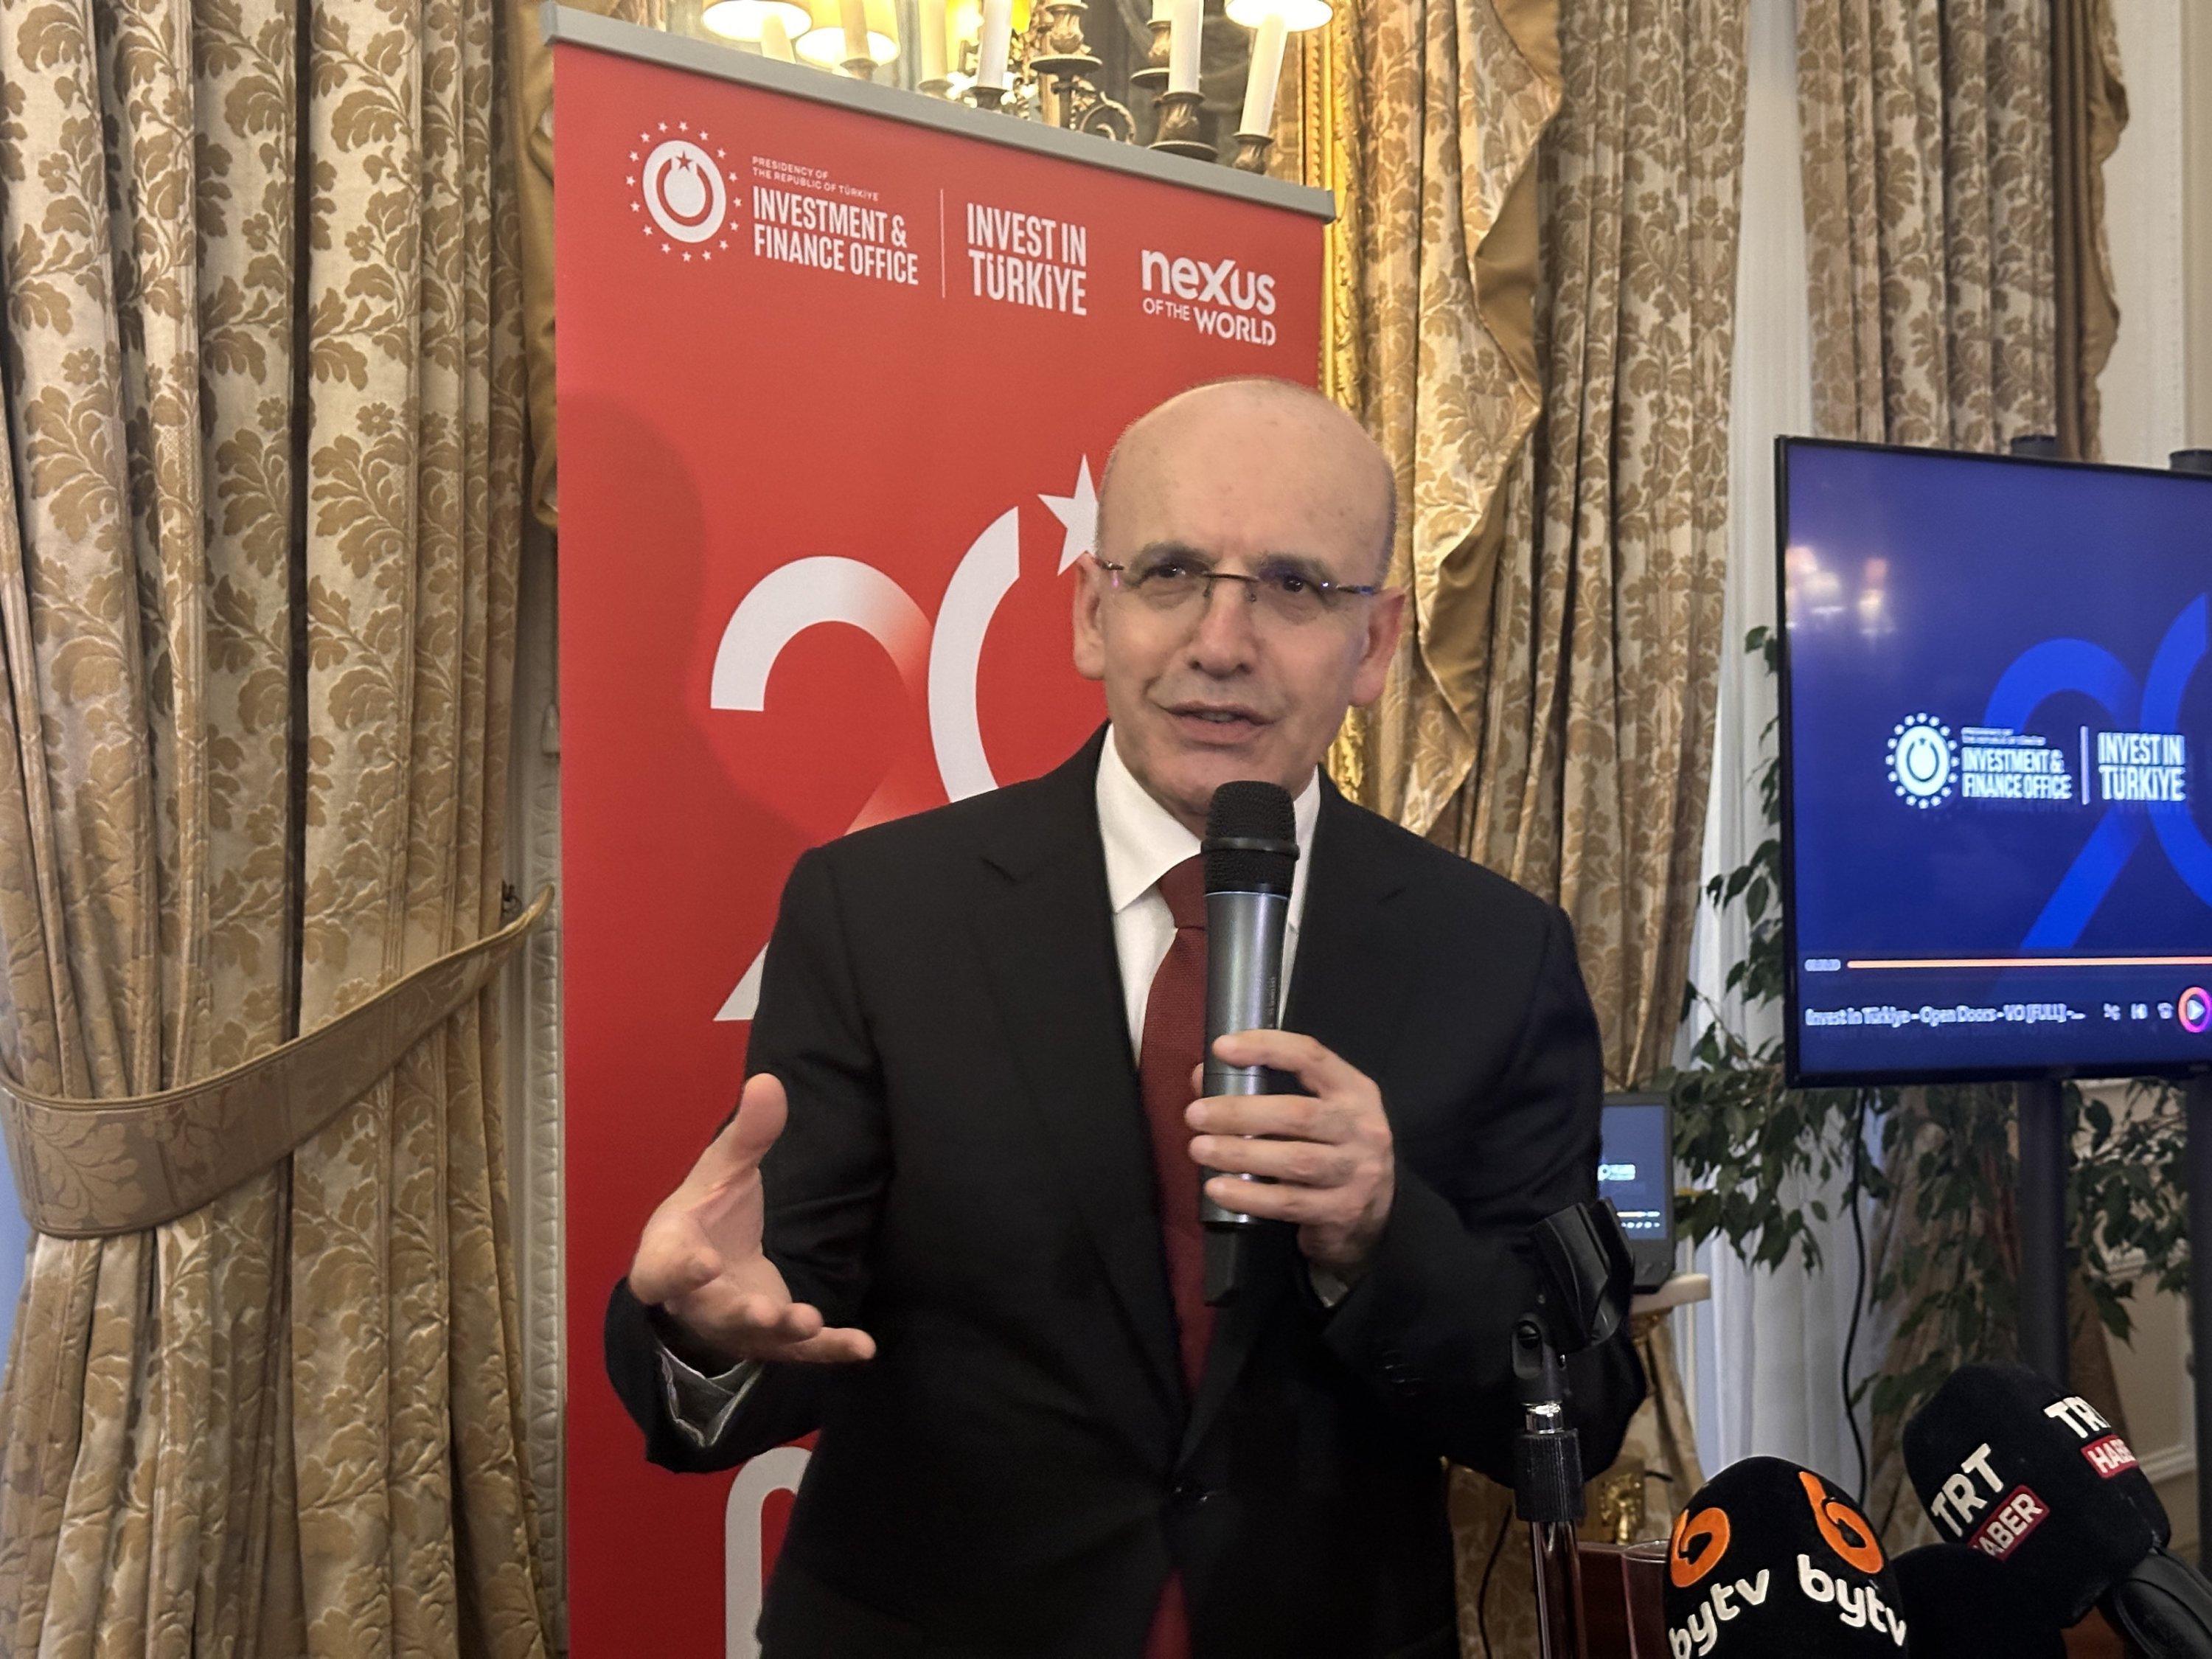
Treasury and Finance Minister Mehmet Şimşek will hold a series of high-level meetings in the U.S. this week, engaging with global investors and financial institutions on the sidelines of the IMF-World Bank spring meetings.
Şimşek will join top finance officials from around the world will convene under the shadow of the war in the Middle East, which has delivered a third major shock to the global economy after the COVID pandemic and Russia’s full-scale invasion of Ukraine in 2022.
Weekend talks between the U.S. and Iran brokered by Pakistan failed to reach a deal to end the war that has effectively shut the Strait of Hormuz, sending energy prices soaring and causing the worst ever disruption in supplies.
Starting on Monday, the U.S. military said it would begin a blockade of ships leaving Iran’s ports on Monday, and Tehran threatened to retaliate against ports of its Gulf neighbors.
Şimşek began his trip in New York City and was scheduled to attend a roundtable jointly organized by Citigroup and the Turkish-American Business Council. He was also said to hold a bilateral meeting with Citigroup CEO Jane Fraser.
In addition, Şimşek is expected to meet real sector representatives at an event organized by JPMorgan Chase and the top Turkish business association, MÜSIAD, as well as representatives of international credit rating agencies and leading global investors.
Global focus shifts to Washington
Following his New York program, Şimşek will travel to Washington for the International Monetary Fund-World Bank meetings, which kicked off on Monday and will last through Saturday.
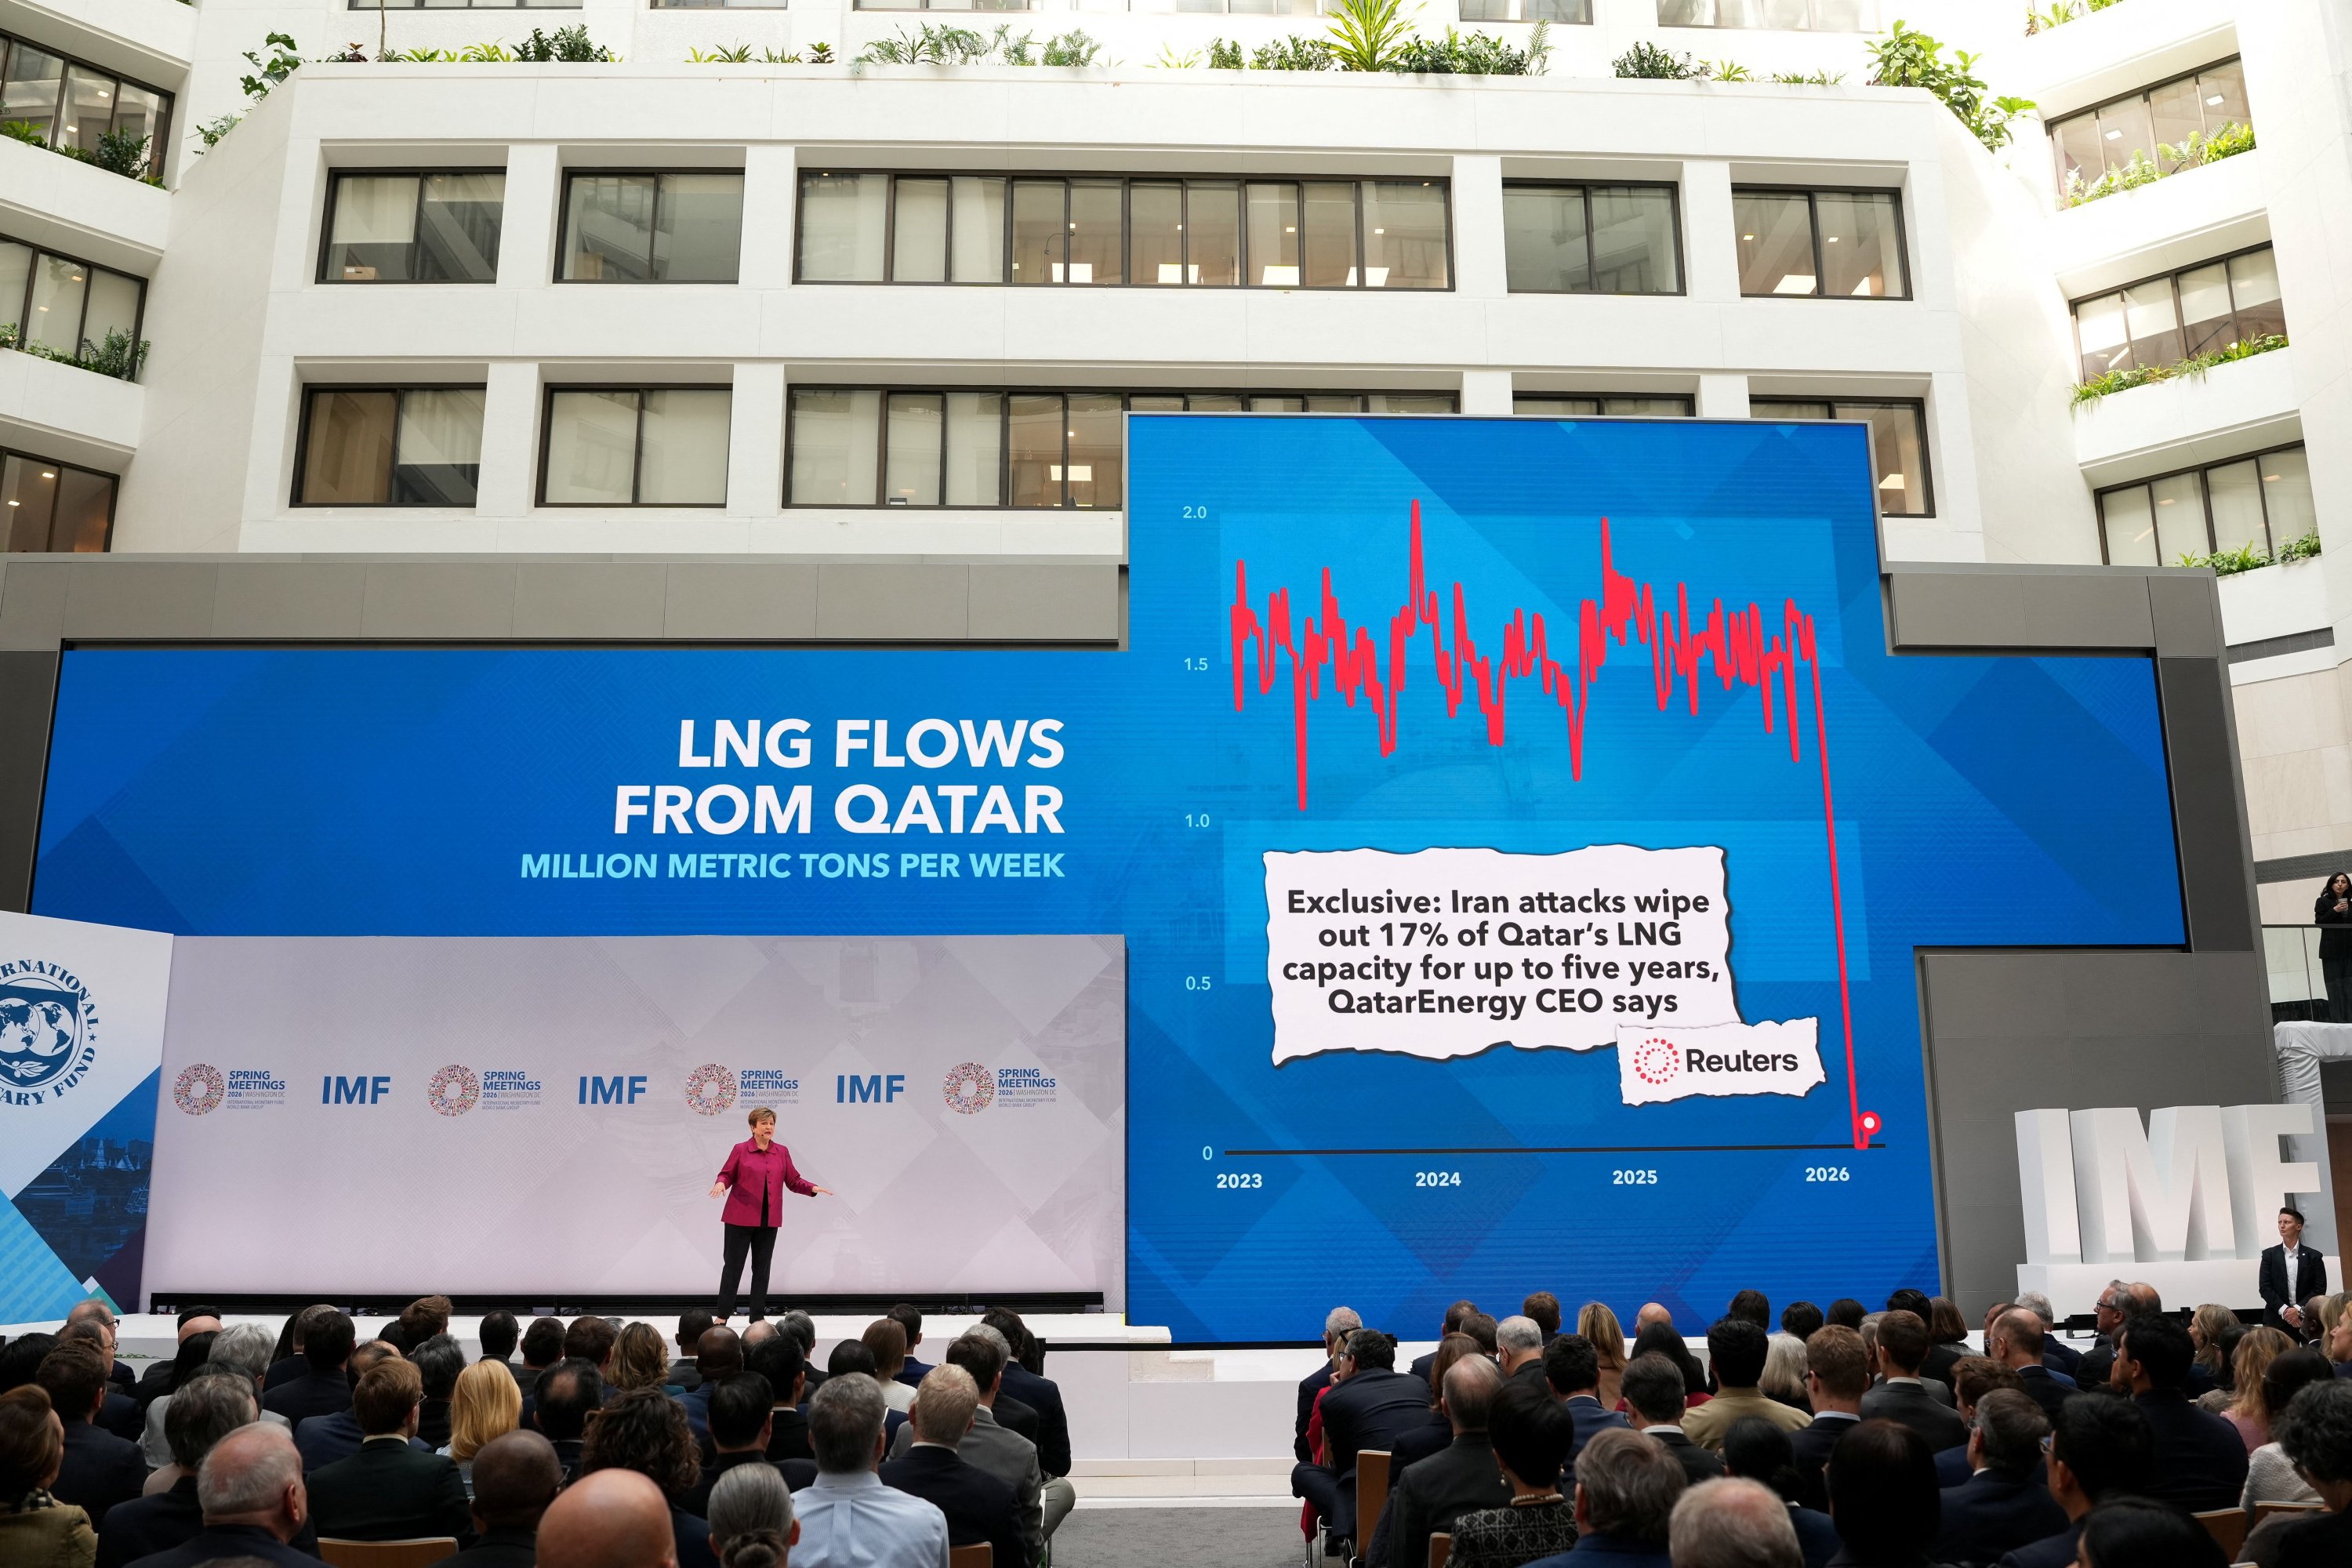
The gatherings bring together finance ministers, central bank governors, private sector leaders and academics.
Top IMF and World Bank officials last week said they would downgrade their forecasts for global growth and raise their inflation predictions as a result of the Iran war, warning that emerging markets and developing countries will be hit hardest by higher energy prices and supply disruptions due to the effective closure of the Strait of Hormuz.
The U.S. military said it would begin a blockade of all maritime traffic entering and exiting Iranian ports and coastal areas starting at 10 a.m. ET (1400 GMT) on Monday. Washington has sought help to reopen the strait from allies, who have not expressed interest.
Before the Iran war broke out on Feb. 28, both institutions had expected to lift their growth forecasts given the resilience of the global economy – even in the wake of major tariffs imposed by U.S. President Donald Trump beginning last year. But the war has delivered a series of shocks that will slow progress on recovering growth and beating back inflation.
The World Bank’s baseline estimate now projects growth in emerging markets and developing economies of 3.65% in 2026, down from 4% in October, but sees that number dropping as low as 2.6% if the war lasts longer. Inflation in those countries was now forecast to hit 4.9% in 2026, up from the previous estimate of 3%, and could spike as high as 6.7% in the worst case.
The IMF warned last week that about 45 million additional people could also face acute food insecurity if the war persists and continues to disrupt fertilizer shipments needed now.
The IMF and World Bank are racing to respond to the latest crisis and support vulnerable countries at a time when public debt levels have reached record levels and budgets are tight.
The IMF said it expects demand for $20 billion to $50 billion in near-term emergency support to low-income and energy-importing countries. The World Bank has said it could mobilize some $25 billion through crisis response instruments in the near-term, and up to $70 billion in six months, as needed.
‘Shock to system’
But economists are urging governments to use only targeted and temporary steps to ease the pain of higher prices for their citizens, since broader measures could fuel inflation.
“Leadership matters, and we’ve come through crises in the past,” World Bank President Ajay Banga told Reuters, lauding work on fiscal and monetary controls that had helped economies weather previous storms. “But this is a shock to the system.”
Countries now face a tough balancing act managing inflation while keeping an eye on growth and the longer-term challenge of creating enough jobs for the 1.2 billion people who will reach working age in developing countries by 2035.
IMF and World Bank also face a far different global landscape with tensions running high between the U.S. and China, the world’s largest economies, and the Group of 20 (G-20) major economies hobbled in its ability to coordinate a response.
The U.S. currently holds the rotating presidency of the G-20, which also includes Russia and China, but it has excluded another member – South Africa – from participation, complicating the group’s ability to coordinate on this crisis.
“You’re trying to operate on consensus when there’s no consensus in the world right now on anything,” said Josh Lipsky, chair of international economics at the Atlantic Council.
Lipsky said statements by the IMF, World Bank and other multilateral lenders about their readiness to support countries hit hard by the war were clearly aimed at reassuring markets.
“It’s a signal to private creditors. This is not a time to flee countries that are in problematic waters. They will have support from the multilateral development banks and the international financial institutions. This is not going to be COVID. This is something that we can handle.”
Tougher conditions for many
Mary Svenstrup, a former senior U.S. Treasury official now with the Center for Global Development, said many emerging market and developing economies entered the crisis worse off than just a few years ago, with lower buffers, higher debt vulnerabilities and lower reserves.
“We need to have this crisis be a catalyst for IMF stakeholders to really rethink how the Fund supports vulnerable countries with the recognition that we’re going to be seeing more global shocks,” she said. “We can’t ask them to sacrifice growth and development for the sake of rebuilding buffers.”
Svenstrup said countries should pursue more ambitious reforms if they received fresh funds. “There probably does need to be more financial support from the (international financial institutions) but it needs to be affordable, and it needs to be in the context of reform programs and potentially broader debt relief,” she said.
Martin Muehleisen, a former IMF strategy chief who is now with the Atlantic Council, agreed, saying the IMF should work with donor countries to accelerate debt restructuring for borrowers and “get them off the debt cycle.” New lending should be tied to a credible debt-reduction road map, he said.
Eric Pelofsky, vice president at the Rockefeller Foundation, said low-income and lower middle-income countries paid twice the amount to service their debts in 2025 than before COVID, limiting funds for education, health care and other critical social programs. Half were now in or near debt distress, up from a quarter, just a few years ago.
“This new conflict threatens any recovery that occurred since the pandemic or the Ukraine war, and it takes countries that have basically been treading water, trying to stay away from default, and keeps them in a long term debt-growth-investment trap,” he said.
Money leaving the investment funds now being liquidated in Türkiye has largely moved into bank deposits, the country’s central bank chief said Tuesday, adding that the risk of the turmoil spreading to the wider financial system remained limited so far.
Regulators last month ordered the liquidation of over 130 investment funds managed by seven asset managers following warnings by some that they could not meet redemption payments.
Authorities have widened their investigation into suspected market manipulation in stocks and fund markets. Eighty-five suspects have been arrested so far in the probe, Justice Minister Akın Gürlek said Tuesday.
The funds ordered to be wound down had reached more than $20 billion in assets over just three years. About half a million investors have been affected.
There have been sharp outflows from funds undergoing liquidation, and part of it came from foreign-resident investors, Central Bank of the Republic of Türkiye (CBRT) Governor Fatih Karahan said Tuesday.
He was answering lawmakers’ questions at Parliament’s Planning and Budget Commission.
For domestic residents, Karahan said, where the money goes matters for dollarization.
“We see that a significant portion of this amount has moved into deposits,” he said. He added that total commercial and savings deposits rose by more than TL 800 billion ($16.27 billion) over the same period.
Karahan said there had also been outflows from foreign-currency funds, and that some of that money could be expected to flow into foreign-currency deposit accounts. Even so, he said, overall deposit preferences were in line with the current Turkish lira share.
He put the lira share of investment funds at about 61% to 61.4%, and said it was holding steady.
Connection to wider system ‘weak’
Karahan said the link between the funds in liquidation and the rest of the financial system was critical for assessing contagion risk, and that current data pointed to a weak connection.
“We can say that the shift toward the Turkish lira in the financial system is continuing in some form, at least based on the data we have at the moment,” Karahan said.
He credited coordinated measures by the central bank and other institutions for keeping the risk of contagion limited so far.
He said the impact so far was mostly confined to the portfolio management companies concerned and their investors.
“We assess that the contagion risk is under control based on the data,” Karahan said. “But this does not mean everything is over. If we see the need, we will continue to take the necessary steps in every way.”
He said there had been a risk of volatility and disruption in lira markets, which was why a number of measures had been taken.
3 areas to watch
Karahan said the liquidation process was only at its start, and that a firm assessment of its macroeconomic effects would need to wait to see how it unfolds.
He said the central bank would track the impact in three areas: wealth, reserves and the real sector.
Karahan said financial wealth could decline somewhat, but that the effect on spending was expected to be smaller than that of the recent fall in gold prices.
For reserves, he said, what matters is where investors leaving the funds put their money. So far the data show a strong preference for the lira.
The third area is indirect effects through household and corporate balance sheets. Karahan said the central bank’s first analyses showed that real sector companies hold only a limited share of the liquidated funds, and that these are mostly large firms with strong liquid assets.
Any balance-sheet impact would therefore be expected to feed less strongly into the real economy. He stressed that these were initial findings and would be updated as data come in.
Cautious stance to continue
In his presentation before the commission, Karahan also said that disinflation is expected to regain momentum provided that supply pressures ease
He stressed that the bank would keep a cautious monetary policy to preserve gains achieved so far in lowering inflation.
Türkiye’s annual inflation dipped below 30% for the first time in almost five years in September, official data showed Monday.
Consumer price growth eased more than expected to 29.73% from 31.51% in August.
That marked the fourth consecutive month of decline, after the downward trend that started in mid-2024 stalled earlier this year following a sharp rise in energy prices caused by the Iran war.
Monthly price growth also came in below expectations at 1.84%, the same as in August.
Some analysts said the September reading raises the prospect of an interest rate cut at the Oct. 22 meeting.
The bank has kept its benchmark one-week repo rate at 37% this year, as it monitored the inflation impact of the Iran war.
Karahan said a slowdown in the disinflation process had been caused by war-related energy price volatility. But he added that “the main trend in inflation remains below annual inflation,” signaling that disinflation would continue if supply pressures fade.
He noted that upside risks to energy prices are being evaluated and that tight policy is seen as important in limiting the inflationary impact of supply shocks.
Karahan said a weaker-than-expected improvement in inflation expectations poses a risk to the disinflation process.
On the other hand, a slowdown in services inflation is continuing despite supply shocks, with weaker domestic demand also contributing, he noted.
Leading indicators show that a slowdown in rent inflation is expected to continue, Karahan said.
A slowdown in domestic demand has become marked, with indicators confirming a weakening of consumption activity, he noted.
Karahan also said the current account deficit-to-GDP ratio in 2026 is seen below long-term averages.
Türkiye’s combined electricity generation from solar and wind sources reached a record 9.9 billion kilowatt-hours (kWh) in August, the highest level on record, according to the Energy and Natural Resources Ministry.
Solar power generation stood at 5.16 billion kWh in August, while wind generation reached 4.74 billion kWh, the ministry said Tuesday.
Solar accounted for 14.1% of total electricity generation during the month, while wind’s share was 12.9%. Combined, the two sources generated a record 9.9 billion kWh.
Hydropower remains largest source
Türkiye generated 36.71 billion kWh of electricity in August, with hydropower maintaining its position as the largest source.
Hydropower accounted for 24.7% of total generation, producing 9.08 billion kWh during the month.
Renewable sources accounted for 56.4% of total generation, at 20.7 billion kWh, while domestic sources accounted for 69.7%, or 25.58 billion kWh.
Daily electricity generation also reached its highest level of the year so far in August. The daily record was set on Aug. 13, when generation reached 1,241,291 megawatt-hours.
Domestic generation reaches record share
During the January-August period, hydropower generation reached 75.2 billion kWh, wind generation 30.4 billion kWh and solar generation 29.8 billion kWh, marking the highest levels recorded for the corresponding period since 2000.
Domestic sources accounted for 73.2% of electricity generation during the period, producing 181.8 billion kWh. Both the volume and share were the highest for the corresponding period since 2000.
Renewable sources accounted for 60.3% of generation, at 149.8 billion kWh, also representing the highest volume and share for the corresponding period since 2000.
Energy and Natural Resources Minister Alparslan Bayraktar said Türkiye aimed to build a strong energy infrastructure through long-term investments in renewable energy.
“Our long-term investments in renewable energy infrastructure continue to translate into record generation figures,” Bayraktar said.
“Our goal is not only to meet today’s energy demand, but to build a strong, sustainable and innovative infrastructure that is completely free from external dependence,” he said.
Bayraktar added that Türkiye would continue integrating its substantial solar and wind potential into the grid using advanced technologies as it pursues its goal of achieving full energy independence.
Justice Minister Akın Gürlek said Tuesday that 85 suspects had been arrested so far in the investigation into Türkiye’s fund turmoil, and that five people had already handed back money they made through what he called “unjust gains.”
Gürlek said authorities would recover such profits from others who made them through market manipulation.
Regulators last month ordered the liquidation of over 130 investment funds managed by seven asset managers following warnings by some that they could not meet redemption payments.
Authorities have widened their investigation into suspected market manipulation in stocks and fund markets.
Legal action has been taken against 207 people in total, with measures imposed on the assets of many of them, Gürlek told Anadolu Agency (AA).
The funds ordered to be wound down had reached more than $20 billion in assets over just three years. About half a million investors have been affected.
Türkiye’s Savings Deposit Insurance Fund (TMSF) has opened accounts for investors seeking to return what authorities describe as “excessive gains” from fund sales.
Gürlek said five people had returned their unjust gains so far. Reports said among them was Fatma Betül Sayan Kaya, who resigned as a deputy chair of the ruling Justice and Development Party (AK Party) after she and her husband were alleged to have made substantial profits trading shares ahead of the turmoil.
Profits made by people who earned excessive gains over a short period would be transferred to a fund set up within the TMSF, the minister said.
“We will pursue our rights to the end within the framework of the law,” Gürlek said.
Gürlek drew a line between two kinds of earnings. Legitimate profit, he said, comes from citizens putting their savings into stocks and the stock market. The other kind came from so-called “bubble” stocks, where traders made abnormal profits by moving in and out quickly.
He said investigators had found that some people in closed and open funds had acted on tips and inside information, and used manipulative trades to make “extraordinary” profits over a short time.
He said the Istanbul Chief Prosecutor’s Office, working with data from the Capital Markets Board (SPK), Borsa Istanbul Stock Exchange and the Central Registry Agency, had frozen the assets of people who made abnormal gains.
Some of them had been arrested, he said, and others had fled. He said the process was continuing.
Gürlek said his ministry first noticed unusual movement in some funds and shares in February 2025 and wrote to the SPK about it. Citizens’ complaints then increased sharply in August 2026. Permission to investigate was granted later that month, he said.
Gürlek said the State Supervisory Council (DDK) had been tasked with examining whether any public institutions were negligent.
He said the Turkish market and economy were very strong and that a problem in a small part of the market should not be generalized.
The U.S. trade deficit surged more than analysts expected in August, government data showed Tuesday, hovering at its widest level since March 2025, driven by imports of oil and advanced tech products like chips.
The trade gap in the world’s biggest economy jumped 13.7% to $105.6 billion, according to Commerce Department data.
This was larger than the $102 billion projected in a consensus forecast released by MarketWatch.
U.S. trade flows have swung significantly since President Donald Trump returned to the White House in January 2025, as businesses rushed to get ahead of his sweeping, and fast-changing tariffs on trading partners.
The latest figures, which are adjusted for seasonality but not inflation, also reflect a surge in global energy prices from the war in the Middle East.
U.S.-Israel strikes targeting Iran in late February had triggered Tehran’s response in blocking the Strait of Hormuz, a key waterway for energy transport, which sent oil prices soaring.
Both sides remain locked in conflict.
In August, U.S. imports rose by 4.3% to $420.8 billion, driven by crude oil, gold, semiconductors and industrial machinery.
U.S. exports climbed by 1.4% to $315.2 billion, partially driven by energy exports too.
German factory orders dropped sharply in August, more than forecasted, as large-scale orders for aircraft, ships, trains and military vehicles declined, official data showed Tuesday, underscoring the fragility of a recovery in Europe’s biggest economy.
New orders, a key indicator of future business activity, were down 10.6% from a month earlier due to a drop in large-scale domestic orders, according to provisional data from Destatis.
It was the first decline in four months and more than the 1% decrease forecast by analysts surveyed by the financial data firm FactSet and Reuters.
The long-stagnant German economy has been slowly recovering on the back of massive public spending, with some recent data generally pointing to signs of growing strength.
The economy ministry said August’s order data thus represented a “marked setback.”
The decline was entirely attributable to a 61.5% slump in what the statistics office classifies as “other transport equipment,” a category that more than doubled in July due to an exceptionally high volume of large-scale orders of ships, railway rolling stock and aircraft.
When large-scale orders are excluded, new orders in August were 0.1% lower than in the previous month.
Weak figures likely to drag on Q3 growth
The weak figures suggest industry will weigh on third-quarter economic growth after helping to drive expansion in the first half of 2026, although analysts expect a rebound in the fourth quarter as government contracts pick up.
The German economy grew by 0.3% in the second quarter, prompting the government to raise its full-year forecast to 1.3%.
Much of the momentum seen in German industry so far this year has been driven by defense spending.
“Excluding these highly volatile large orders, bookings in the manufacturing sector have been treading water for months,” said Jupp Zenze, economic expert at the German Chamber of Commerce and Industry.
“Broad-based economic momentum remains absent.”
Economist points to full order books
The three-month comparison, which strips out some of the month-on-month volatility, showed that new orders in the period from June to August were 1.3% higher than in the previous three months.
Based on the figures available so far, the industrial sector likely slowed growth of the German economy in the third quarter, in contrast to the first half of the year, said Commerzbank senior economist Ralph Solveen.
However, Solveen expects this trend to reverse in the fourth quarter, as the government is likely to issue more contracts, which should have a positive long-term impact on sales and production.
“This outlook is also supported by the significant improvement in business sentiment over the past few months,” he said.
After revision of provisional data, new orders in July increased by 3.2% compared with the previous month, up from the previously estimated 2.5%.
According to the latest data from July, the order backlog provided coverage for a record nine months, said Marc Schattenberg, economist at Deutsche Bank.
“The disappointingly weak August figures should be viewed in the context of already very full order books,” Schattenberg said.
Foreign orders were down 5.4% in August on the month, with orders from the euro zone registering a decline of 5.4% and orders from outside the eurozone decreasing by 5.5%. Domestic orders declined by 17.3% on the month.
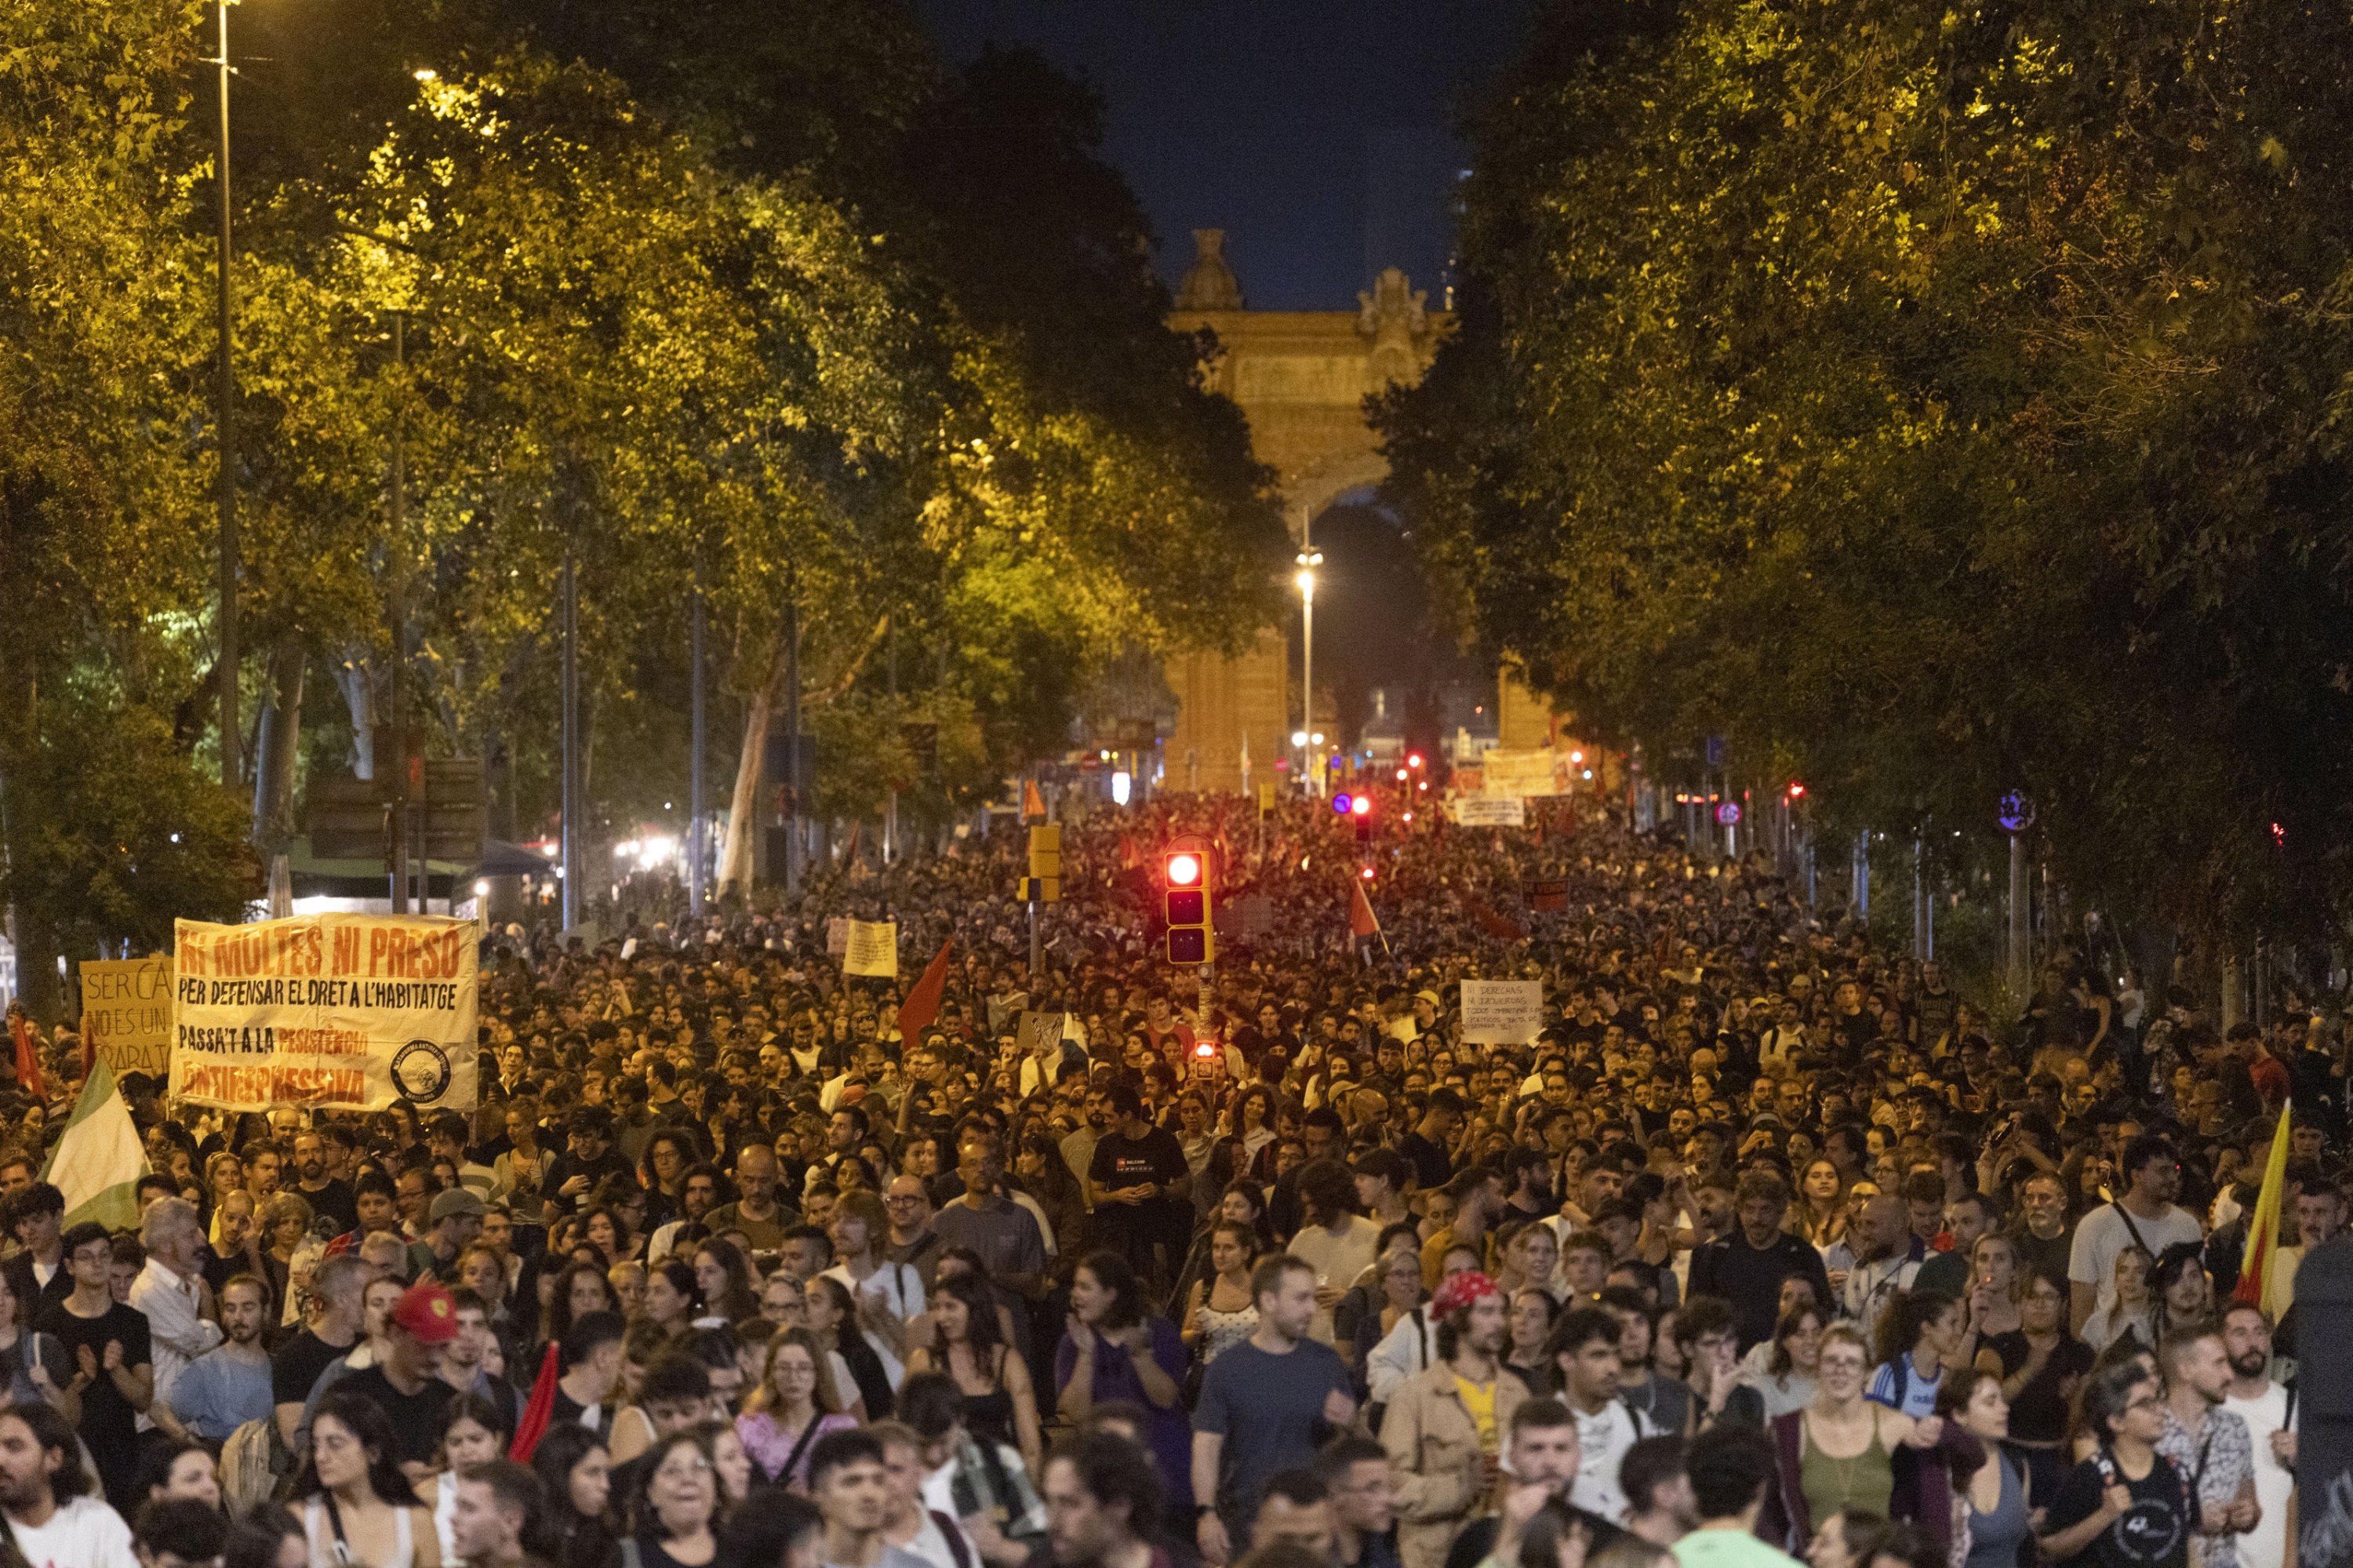
Spain’s government on Tuesday approved emergency measures to address the housing crisis, after an outbreak of violence in the coastal city of Barcelona the previous night that drew tens of thousands of people into the streets.
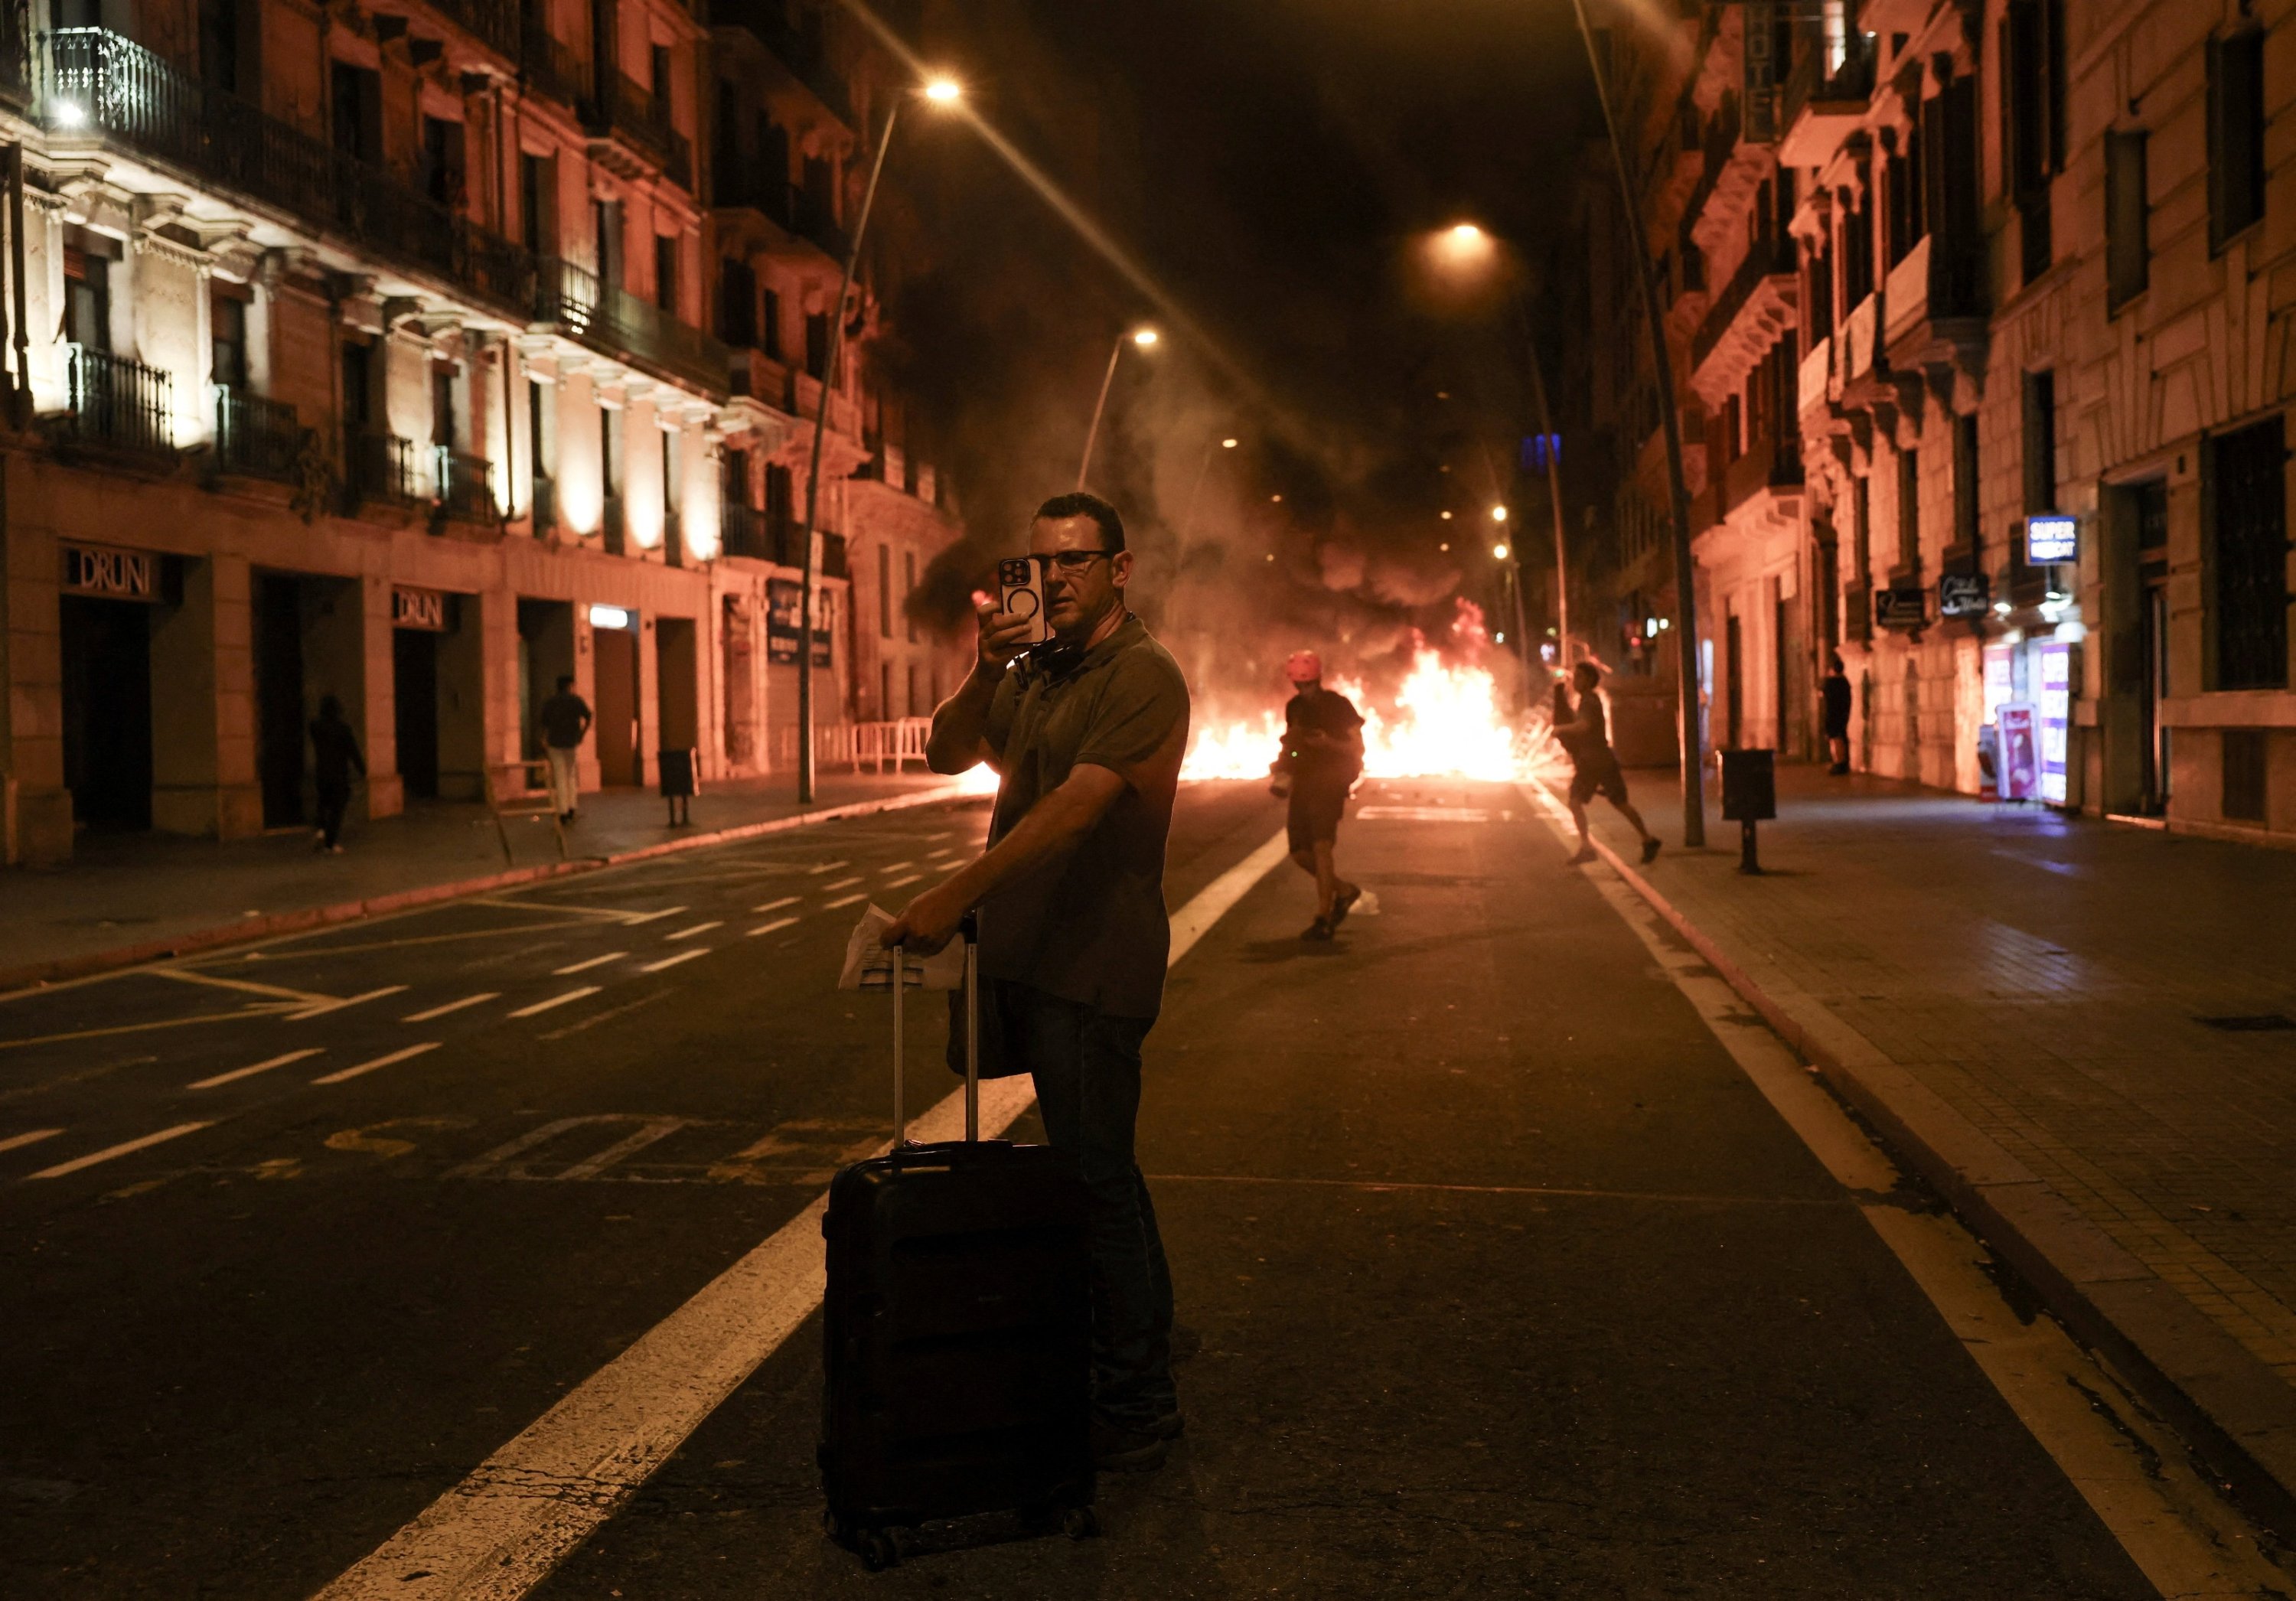
The Barcelona turmoil late on Monday followed protests across the country over the weekend that demanded measures to resolve a crisis sparked by the eviction of an 87-year-old woman in Madrid, the country’s capital.
In Barcelona, Spain’s second-largest city, a severe weather alert over the weekend had forced organizers to reschedule the protest for Monday. What began as a massive peaceful march turned violent when groups of hundreds of hardcore activists clashed with police, throwing stones and setting fire to trash containers.
Prime Minister Pedro Sanchez’s government approved measures similar to those rejected by Parliament last Friday, which prompted his call for early elections on Nov. 29. The measures will be sent for ratification by an interim legislature, which remains active until the elections.
The smaller, interim legislature – known as “permanent commission” – is composed of 69 members, compared to the 350 that sit in the regular Parliament.
Alejandro Quiroga, professor of political science at Madrid’s Complutense University, said the maneuver of having decrees approved by the interim legislature was constitutional but also a necessary political move by Sanchez.
“I don’t think Sanchez had an alternative,” Quiroga told the Associated Press (AP). “If you are calling early elections so you can keep the public’s focus on housing, you can’t just sit back and do nothing about it. That wouldn’t have been smart.”
The new measures are to extend protection against evictions for vulnerable Spaniards until 2030, regulate room rentals, impose a new tax on seasonal rentals, ban speculative real estate purchases and give tax breaks to landlords, Housing Minister Isabel Rodriguez told reporters last week.
Rising costs and a housing shortage are pricing many Spaniards out of the housing market, despite strong economic growth in Europe’s fourth-largest economy.
The protesters have been demanding stronger protections for tenants, measures to combat fraud and a ban on evictions when alternative housing is unavailable.


-
 Economy3 days ago
Revolut: $115 billion fintech taking on Europe’s biggest banks
-

 Economy3 days ago
Global M&A deal rush slowed down in Q3 as borrowing costs bite
-
 Economy2 days ago
Brazilian assets rally as Flavio Bolsonaro tops first-round vote
-
 Economy2 days ago
Türkiye’s Halkbank after secondary offering amid strong interest: CEO
-
 Politics2 days ago
MP hints at more access for Öcalan amid terror-free Türkiye bid
-
 Economy1 day ago
Top central bankers due in Istanbul to discuss policy challenges
-
 Economy1 day ago
Türkiye says Development Road could become $80B ‘energy corridor’
-
 Politics1 day ago
3 jailed in Türkiye over FETÖ-linked infiltration of MASAK data systems