Economy
Finance leaders wrap IMF-World Bank talks as trade tensions linger

International finance chiefs wrapped up their talks in Washington and are returning home with a measure of relief due to the surprising resilience of the global economy amid sweeping U.S. tariffs, but also cautious over what lies ahead.
When finance ministers and central bankers gathered in Washington earlier in April for the first of the twice-yearly meetings of the International Monetary Fund (IMF) and World Bank, the anxiety over U.S. President Donald Trump’s just-unveiled “Liberation Day” tariffs was palpable.
Six months on from the just-concluded October meetings, the initial enthusiasm had given way to fatigue and wariness, as the policy landscape remains never fully settled.
“It’s been just absolutely exhausting since Liberation Day as a policymaker, trying to make sense and then actually make policy and communicate to the public about this,” Bank of Thailand Deputy Governor Piti Disyatat said. “So the uncertainty has been very difficult.”
“The global economy appears to be more resilient than we thought several months ago. But there’s no room for complacency given various types of uncertainty,” said a Japanese delegation official who participated in talks in Washington. “There was a great degree of discussion over uncertainties.”
A week of fractious back-and-forth between the U.S. and China drove the point home as Trump responded to new export controls on rare earth minerals from Beijing with the re-imposition of 100% tariffs on Chinese exports to the U.S.
The re-escalation of tensions between the world’s two largest economies sharpened the focus among the hundreds of policymakers taking part in the meetings, amid growing momentum for new trade arrangements outside the U.S.-China orbit.
IMF Managing Director Kristalina Georgieva said she had rarely seen as much constructive engagement at the semi-annual meetings of finance officials and central bankers.
“It may be because uncertainty is so high that there is no space for theatricals,” Georgieva told a banking conference on Saturday.
“It may be because now many countries realize that what they took for granted – international cooperation that helps us do better – we should not take for granted.”
Strengthening bilateral, regional ties
Georgieva and World Trade Organization (WTO) chief Ngozi Okonjo-Iweala told participants it was promising that U.S.-China tensions, however intense, had not blown up into a wider trade war and noted that many countries were in fact seeking to deepen bilateral and regional ties.
New Zealand Finance Minister Nicola Willis told Reuters she expected that trend to gain momentum against the backdrop of increasing geopolitical and economic uncertainty.
She said that the European Union was now seeking to align with the Comprehensive and Progressive Agreement for Trans-Pacific Partnership, a free trade deal among 11 member countries.
“All of those trade relationships are very strong, and the messages that we’re having from our partners are that they wish to continue to build on them and expand them, rather than go the other way,” she told Reuters in an interview.
Rania Al-Mashat, Egypt’s minister of planning, economic development and international cooperation, told Saturday’s event that increased regional cooperation was a “fallout” of global developments, but would remain important in the future.
Reforms needed everywhere
The situation also drew attention to strains in the global economy, including persistent and “excessive” external balances, near-record debt levels, growing concerns about the non-bank sector, and disruptions from artificial intelligence technologies.
Bank of England (BoE) Governor Andrew Bailey said frank discussion was needed, given the international community’s past failure to identify and halt the subprime mortgage developments that triggered the global financial crisis of 2007-2009.
Transparency was critical in an opaque world with tight cross-links between banking, insurance and private finance.
“It’s our duty to lift the lid and see what’s going on,” Bailey said at an event hosted by the Group of Thirty on Saturday. “We’ve obviously had a few events that are going on at the moment where we are having to ask the question, are these one-offs or is it the canary in the coal mine?”
Georgieva underscored her concern about “stretched valuations,” following the IMF’s warning on Tuesday that markets are too comfortable with risks, including trade wars, geopolitical tensions and yawning government deficits, which heightened the risk of a “disorderly” market correction.
The IMF chief said she ended the week with a long list of to-dos, including reviews of how the IMF conducts its surveillance of countries’ economies and assesses their debt levels, while Okonjo-Iweala underscored the urgency for WTO reforms.
“We need to diversify trade,” WTO’s Okonjo-Iweala said, noting that global trade had clearly helped many countries, even if results had been uneven, leaving other countries behind.
“We need to fix parts of it that don’t work,” she said. “We need to re-imagine globalization. We cannot have what we had in the past,” she said.
Climate risks mounting
Climate change posed perhaps the biggest risk, officials agreed, despite Trump’s recent comments at the U.N., calling it a “con job.”
The issue bubbled up during a meeting of the IMF steering committee on Friday, where South African central bank governor Lesetja Kganyago told officials that climate risk was indisputably a macro-critical issue with huge implications for insurance, economic fundamentals and financial stability.
“In trade negotiations, you can walk away … and you can find another trading partner,” Kganyago told the G-30 conference. “With climate, when you walk away from the negotiations, the whole planet gets warm and we will all suffer.”
Upcoming midterm elections in the U.S. stand as a main reason behind the Trump administration’s sudden announcement that Russian diesel would be released immediately to American and global markets, analysts and critics say.
On Friday, U.S. President Donald Trump said he concluded a “highly successful discussion” with Russian President Vladimir Putin and noted it was agreed that Russia would “immediately” supply over 300,000 tons of diesel fuel to the American and global marketplace.
“Another 500,000 Tons during the month of November, and 1,000,000 Tons immediately therafter,” he wrote in a post shared on his Truth Social.
Separately, the U.S. Treasury Department has shared a notice and issued a temporary exemption from sanctions against Russia, permitting the sale, supply, unloading and import of Russian diesel until April 7, 2027.
Russian Deputy Prime Minister Alexander Novak also announced the immediate lifting of Russia’s ban on diesel exports, according to the state news agency Tass.
Record diesel prices
The prices of diesel reached record highs in the U.S., and many advanced economies, including the U.K., France and Germany, in recent weeks amid the ongoing war between the U.S. and Iran in the Middle East and Ukraine’s attacks on Russian energy infrastructure.
U.S. national average diesel prices reached $6.27 per gallon as of October, according to AAA Fuel Prices.
However, with the midterm elections next month, critics argue that the amount of supply volume shared by Trump is insufficient, also suggesting that Russia is likely unable to produce as much at its refineries impacted by Ukrainian attacks.
Before the reported lift on the ban, Russian authorities had recently extended the ban on exports of diesel untill end of October amid the domestic crunch in supplies – a rare case for the country, which before the invasion of Ukraine was one of the top global energy suppliers.
Can deal ease pressure on prices?
The U.S.-Russia deal, which has led to a rebuke by Ukraine and its European allies, such as Germany, raised a question: could it actually help alleviate the recent cost pressures the customers across Europe and the U.S. have been facing?
Following Trump’s announcement, diesel futures in fact dropped, trading about 4.5% lower at $4.67 per gallon. Data from the NY Harbor chart, displaying costs of futures on Oct. 9, showed that the November price dropped by 4.1% to $4.68.
Still, it is unclear how it would reflect on crude oil prices, with tensions in the Middle East and lately between Saudi Arabia and Houthi rebels also weighing on the outlook.
Diesel is a refined product, and additional shipments do not automatically increase crude production.
WTI price settled Friday at $91.85 per barrel, up 0.39%, while Brent crude closed at $104.72, gaining 0.42%. Both benchmarks finished higher despite the initial reaction to Trump’s announcement.
But since diesel is used in logistics and agriculture and coupled with the recent G-7 decision to release additional emergency stockpiles, any drop in prices would be welcomed by farmers and companies, which have voiced dissatisfaction with the current level of prices.
The U.S.-Russia deal was also criticized by Ukrainian President Volodymyr Zelenskyy, after which Trump said the war-torn country needed a new president.
“Allowing Russia to sell petroleum products is an investment in the war, which must be ended, not prolonged,” Zelenskyy wrote on Telegram on Friday evening.
German Education Minister Karin Prien on Sunday also criticized Trump over his call for a new Ukrainian president amid the recent U.S.-Russia diesel agreement.
“For a few liters of diesel. What a moral bankruptcy,” Prien said on X in response to Trump’s remarks.
Trump on Saturday called for Ukraine to “get a new president,” accusing Zelenskyy of repeatedly failing to reach a deal to end the war with Russia.
“I suggest they get a new leader who can make a deal, because he could have made many deals that, for some reason, he never does,” Trump said.
Meanwhile, Germany reaffirmed its commitment to sanctions against Russia on Saturday following the Trump-Putin agreement, according to German media.
The bank accounts of 214 individuals and companies have been frozen as part of the ongoing investigation into funds and asset management companies following the liquidation order by Turkish authorities, with TL 187 billion (about $3.8 billion) in earnings under scrutiny, according to a Sunday report by Sabah newspaper.
As part of an ongoing investigation into investment funds in Istanbul, authorities identified 141 individuals and 73 companies, 214 in total, who reportedly earned more than TL 100 million from three funds, the report suggested.
The Istanbul Chief Public Prosecutor’s Office is said to have sent the list of these individuals and companies to the Savings Deposit Insurance Fund (TMSF), which has begun formally notifying them about the return of their earnings, it added.
Court orders have also imposed travel bans preventing the relevant individuals and company executives from leaving Türkiye.
Moreover, investigators are reportedly tracing where the money went after it was withdrawn from the investment funds.
On Friday, another report said that Turkish prosecutors have identified 214 individuals and companies they say made a combined TL 187.65 billion from three of the investment funds at the center of the country’s fund turmoil.
The Sunday report names Melis Sütşurup Sandal, the wife of Turkish singer Mustafa Sandal.
According to the investigation documents cited in the report, she reportedly earned TL 2.355 billion from Tera’s TLY investment fund, placing her first among the individuals listed.
Her total withdrawals from fund accounts during 2026 reportedly amounted to nearly TL 15.8 billion. As of Sept. 16, 2026, her fund account reportedly held approximately TL 250 million.
The Financial Crimes Investigation Board, known as MASAK, has also begun examining the bank accounts of people who transferred money from their fund investments into their personal bank accounts. Investigators are said to be preparing detailed reports to determine where the approximately TL 187.65 billion ended up.
Authorities launched a sweeping investigation and market intervention last month after suspected price manipulation in a number of thinly traded stocks triggered heavy losses and redemption pressures at investment funds.
The Capital Markets Board (SPK) halted trading in more than 130 funds on Sept. 17. Nearly half a million investors have been affected.
India targets increasing its steel capacity to 604 million metric tons by 2047 from around 220 million tons at present, according a draft steel policy for public consultation released late on Saturday.
Reuters reported last week, citing the draft document, that the policy lays out plans to cut sector emissions and shore up access to iron ore and coking coal, key raw materials, to meet anticipated demand.
The policy aims to cut the sector’s average carbon-emission intensity to around 1.54 tons of carbon dioxide per ton of crude steel by 2047 from the current 2.54 tons, in line with India’s net zero emission goal for 2070, according to the draft document.
The steel ministry expects iron ore demand at 772 million tons and plans to secure access to high-grade reserves by pursuing foreign assets and joint ventures, the document said.
The ministry also expects coking coal demand to reach 236 million tons, the document said, with the government planning to diversify its sourcing via “strategic global outreach” and acquire overseas assets.
Türkiye generated nearly $823 million from vegetable exports from January through September, up 10% from a year earlier, according to a report on Saturday.
Some 651,087 tons of tomatoes, peppers, cucumbers, zucchini, and other vegetables grown in Türkiye found buyers in international markets, according to information compiled by Anadolu Agency (AA) from data provided by the Türkiye Exporters Assembly (TIM).
Fresh vegetable export revenues, which amounted to some $749.15 million between January and September last year, increased by 10% during the same period this year, reaching $822.68 million.
Tomatoes ranked first among fresh vegetable exports, generating $304.16 million in revenue. Peppers followed, bringing in $275.48 million in export earnings.
Compared with the same period last year, revenue from tomato exports increased by 4%, while revenue from pepper exports rose by 29%. Together, these two products accounted for approximately 70% of total fresh vegetable export revenues.
During this period, Türkiye earned $61.38 million from cucumber and gherkin exports, $57.44 million from zucchini exports, and $39.64 million from carrot and radish exports.
Romania largest export market
Romania ranked first among Türkiye’s fresh vegetable export markets, purchasing products worth approximately $147 million.
Germany followed with $132.7 million, while Russia ranked third with $76 million.
During the same period, Türkiye exported fresh vegetables worth $55.48 million to Bulgaria, $49.96 million to Ukraine, and $47.8 million to the Netherlands.
Hayrettin Uçak, the chair of the Turkish Fresh Fruit and Vegetable Exporters’ Associations Sector Board, told Anadolu Agency (AA) that they viewed the increase in export revenues positively, despite changing conditions throughout the vegetable production season.
“Our exports increased by 10% over the previous year during the first nine months, and this success in exports makes us happy,” Uçak said.
“Neighboring and nearby markets are important for our vegetable exports. We need to closely monitor consumer expectations and shopping habits in the European market. Being able to supply buyers with the products they want, in suitable packaging and on time, plays a decisive role in commercial relationships. In this respect, we consider the growth in exports to Romania and Germany particularly important,” he added.
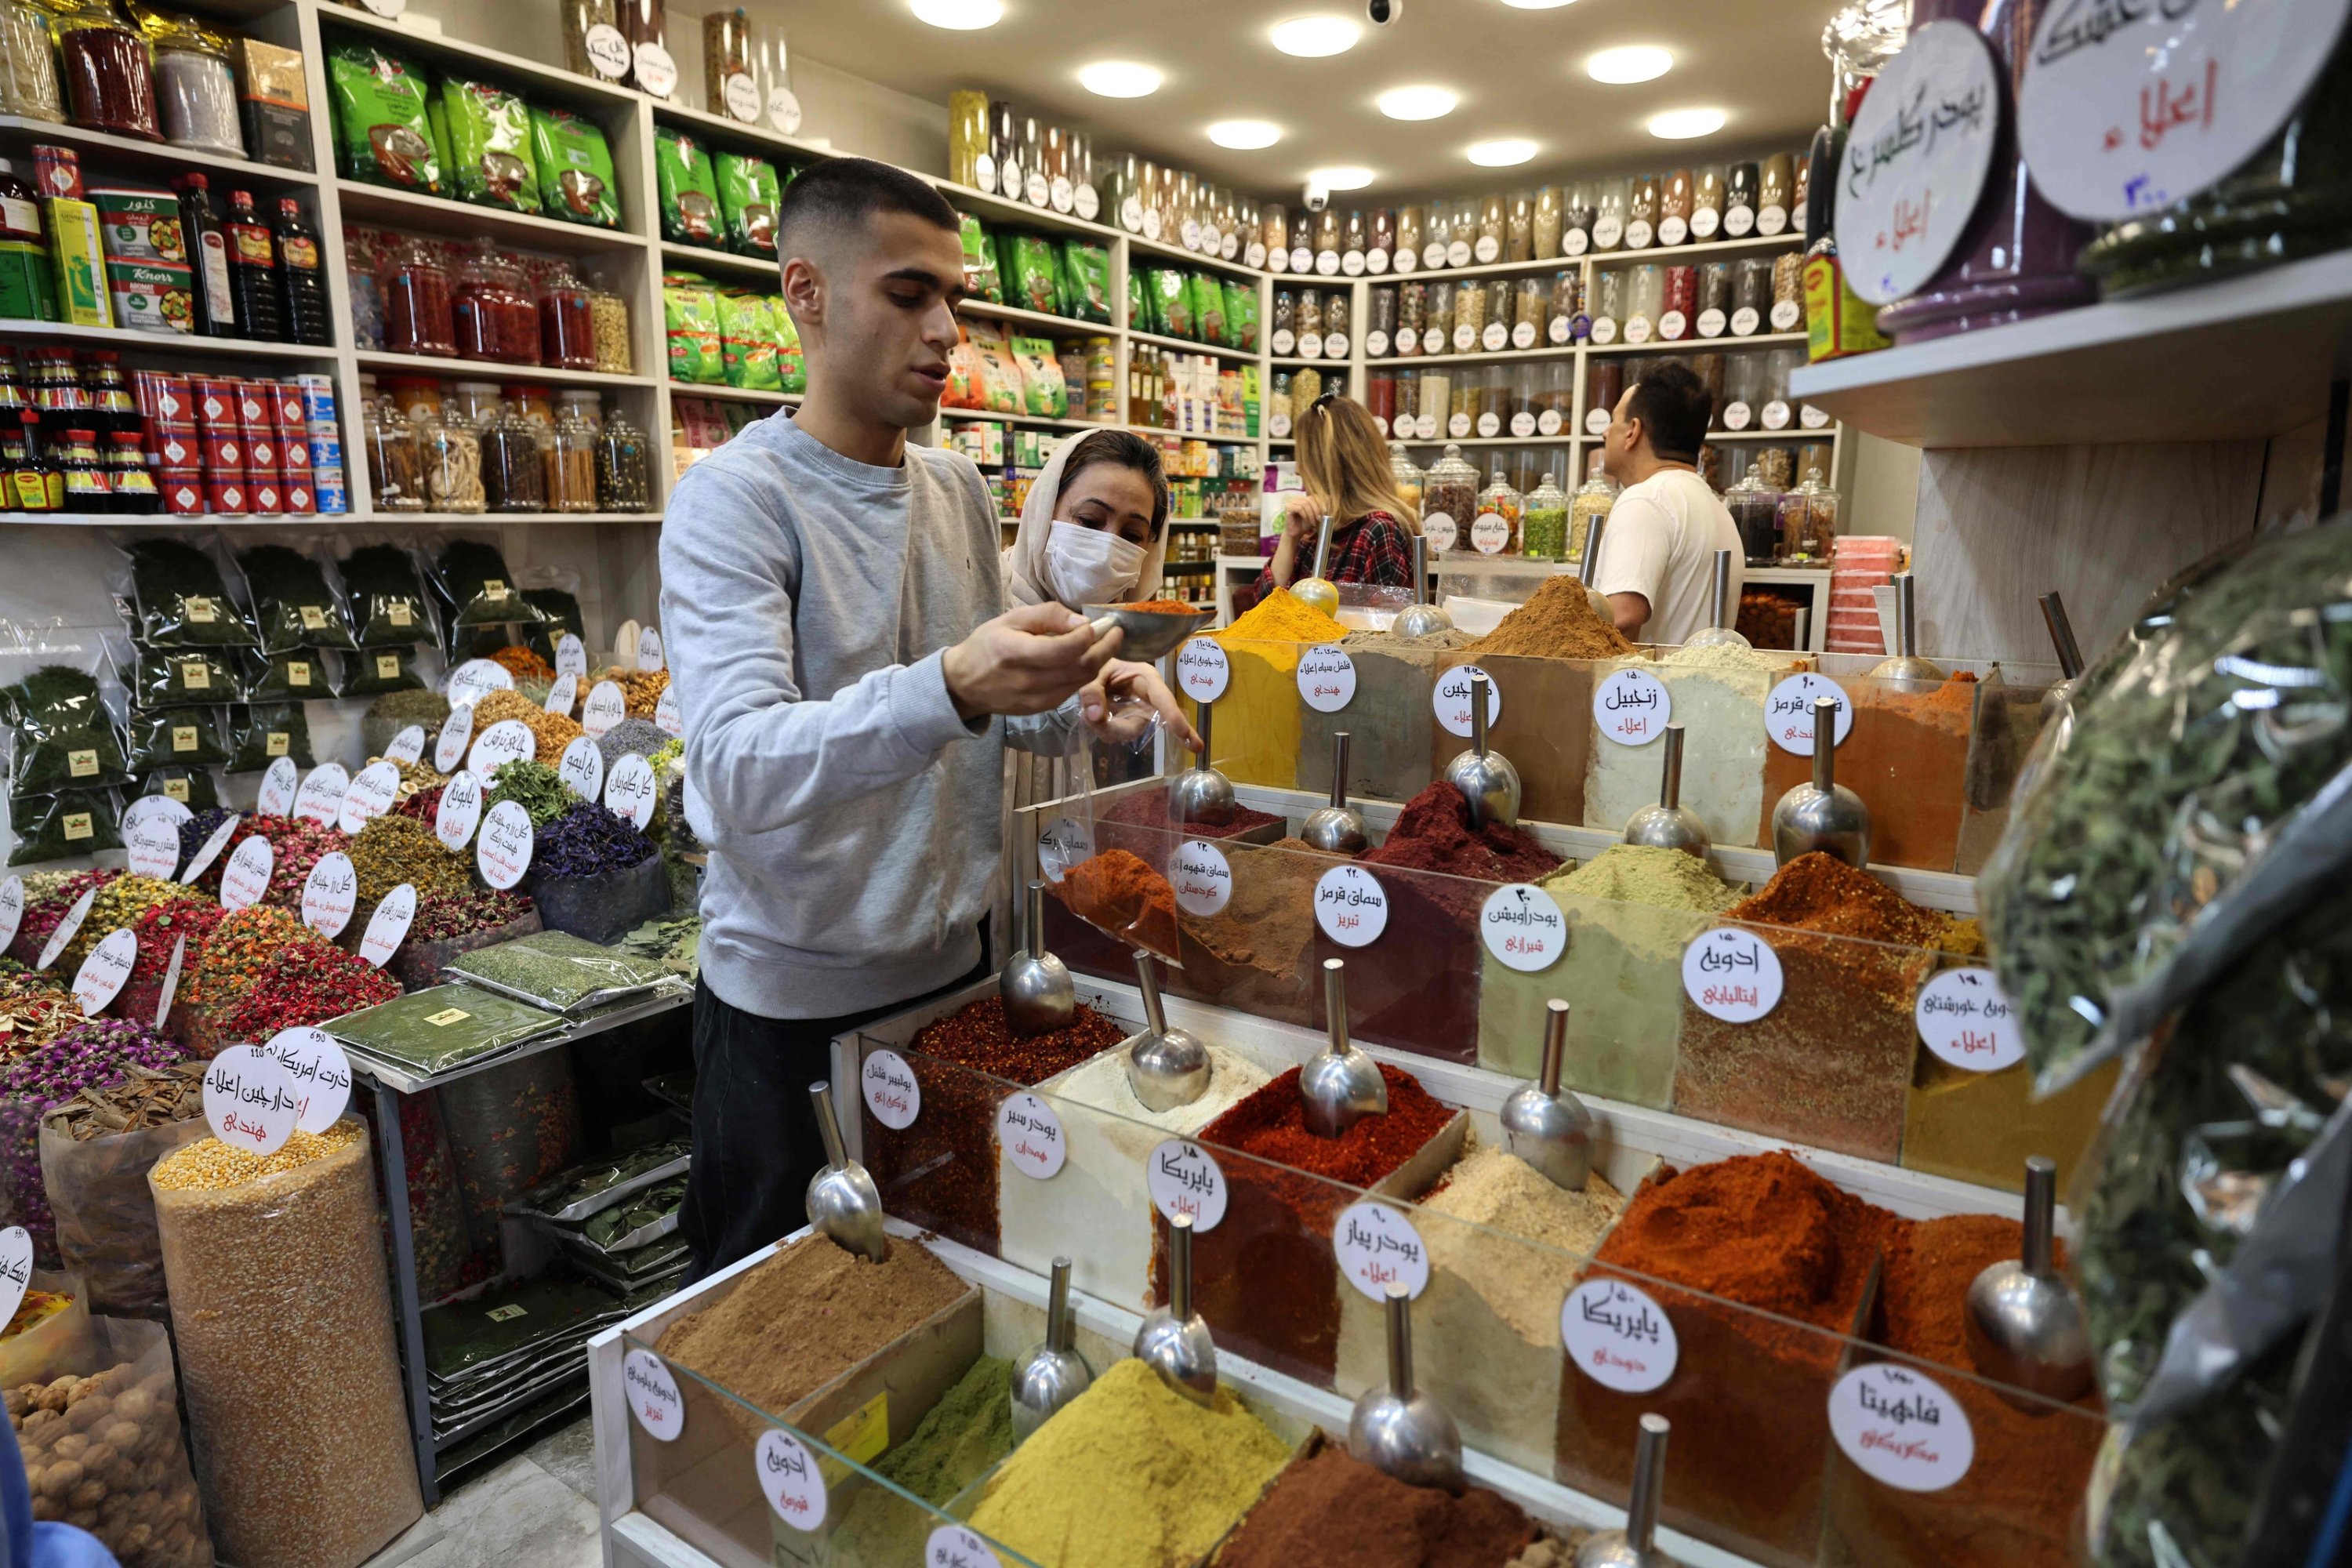
The scent of fragrant herbs and spices drifts through Tehran’s bazaar, but business is far from brisk. Shopkeeper Nasir says locals who once purchased nuts by the kilo are buying less as the U.S.-Iran war-driven price increases squeeze demand and push traders to the brink.
The marketplace in the Iranian capital’s north would usually be abuzz with customers, but shops now sit mostly empty with only small numbers of people walking its old narrow paths, a jarring shift for the sellers shouting to promote their goods.
“There used to be customers who bought 2 to 5 kilograms. Now, they’re down to buying one kilogram or half a kilogram,” said the 61-year-old.
“Prices are truly high. We all know it, and it would be a lie to say otherwise.”
Nasir called on authorities to stabilize the currency so businesses could plan ahead.
“We’re left in limbo; everyone is,” said the fruit and nut seller.
“They need to stabilize the dollar exchange rate.”
Iran’s economy has been battered by years of sanctions, but the conflict that began in February with U.S.-Israeli attacks and an American blockade of the country’s ports has put extra strain on daily life.
Rising inflation, nearly 90% year-over-year in September according to official figures, and erratic currency exchange fluctuations have driven up the cost of everyday items. Food prices have more than doubled since last year.
At the bazaar, a historic covered market in Tehran’s Tajrish square, locals surrounded by Iranian flags and Persian signage try to escape the economic gloom, scanning sweets, jewellery, traditional garments and cuts of meat before their weekend begins.
In an alley, a street artist plays a guitar while another drums his hands on a box to draw tips from passersby.
‘Just need stability’
But across the commercial district, many struggle to see a future for their businesses.
“It is a desperate, last-ditch struggle. Manufacturers are going bankrupt, laying off staff and closing shops, and the impact inevitably reaches us,” said Ali Nowruzi, 36, who runs a sportswear shop in the bazaar.
The businessman now orders only a few items for display on his shop’s shelves to stop them from looking bare like his warehouse, which he says lies empty due to lack of demand.
“We have absolutely no plan for the future. When people don’t come to buy … it effectively spells bankruptcy for the business,” he said, citing rising rent and utility bills.
“We just need some stability.”
Many shoppers, whose purchasing power has weakened since the outbreak of war, are seen leaving the bazaar without buying anything.
Azadeh, a 45-year-old woman currently out of work, says she just goes there to “watch the shops”.
Mounting pressure over the war saw Iran’s gross domestic product (GDP) contract 10.1% year-over-year between late March and late June, according to official figures.
The rial traded at around 2.7 million to the dollar on the unofficial market in the past week, compared with about 1.7 million before the war.
The minimum monthly wage that stood at around $120 a year ago has fallen to $65.
The country’s economy minister has rejected predictions of an imminent economic collapse, accusing Iran’s foes of trying to fuel public anxiety and drive up exchange rates.
Prices ‘skyrocketed’
Azadeh offers a price comparison of a kitchen cloth bought several months ago for 22 cents. She says that the item now costs $1.10, five times more.
“It shows that prices haven’t just gone up; they’ve truly skyrocketed,” she said.
She has stopped buying some fruits and says she can no longer afford holidays.
“We aren’t meant to just exist, we’re meant to actually live, right?” she asked.
Car mechanic Mojtaba Rezaei says his customers have “dropped to a 10th of what it was” because “goods now cost two or three times as much.”
“I actually feel embarrassed telling prices to customers. People just come in, ask the price, and leave,” the 57-year-old told Agence France-Presse (AFP) at the bazaar.
“So many things – buying clothes, going out for leisure, dining at restaurants – have all been cut out of our lives.”
Global finance leaders will meet in Thailand this week as the widening Middle East war, a historic energy supply shock and higher interest rates threaten to weigh further on already lackluster global economic growth.
The U.S.-Israeli-led war with Iran, now in its eighth month, and the inflation and hardship it has caused, will dominate the agenda and sideline conversations during the annual meetings of the International Monetary Fund (IMF) and World Bank, being held outside of Washington for the first time in three years.
Notably absent will be U.S. Treasury Secretary Scott Bessent, who dispatched two senior officials in his stead while he handled some “domestic engagements,” a U.S. official said.
His decision to skip the high-profile gathering and a meeting of the G-20 major economies, which the U.S. leads this year, may frustrate counterparts amid rising tensions over the Iran war, Ukraine’s battle with Russia and the U.S. move to impose sanctions on the International Criminal Court (ICC).
World Bank President Ajay Banga told Reuters that while global growth had held up better than feared when Iran closed the Strait of Hormuz, shutting off some 20% of the world’s oil, pressures were building again.
Soaring prices for diesel, rising fertilizer prices and a looming “super” El Nino weather effect that experts say could lead to 450,000 heat-related deaths are all hitting at once.
G-7 countries have agreed to release 100 million barrels of diesel and crude oil from emergency reserves under pressure from U.S. President Donald Trump, who is keen to see lower gasoline prices before the November elections that could see his Republican Party lose control of Congress.
Trump on Friday announced a deal with Russia that would provide even more diesel to global markets and a temporary waiver of U.S. sanctions designed to deprive Moscow of revenues for its war on Ukraine. The move drew swift criticism from Ukrainian President Volodymyr Zelenskyy.
More than 1 billion barrels of oil have been released mainly from onshore commercial inventories since the start of the war on Feb. 28, but industry executives say the amount of oil in storage that is accessible to the global market is running low, making the market more fragile and fueling pressure on prices.
Banga said the bank was not revising down its global forecasts at the moment, but was keeping a close eye on developments.
“The real thing is not just El Nino by itself; it’s the combination … What’s happening to fertilizer prices? What’s happening to energy costs? What’s happening to debt? It’s that put together that creates its own challenges,” he said.
“And I think that will call upon all of us to be far more careful on what we prepare for in the coming months.”
Rising debt
IMF Managing Director Kristalina Georgieva issued a similar warning in her traditional curtain raiser speech previewing the meetings, telling the audience, “Winter is coming.”
The IMF has signaled little change in its forecast for 3% global growth in 2026 and may edge its forecast for next year slightly higher.
But some countries will see downgrades, including Ukraine, now in its fifth year of war against Russia’s invasion, and Gulf countries hit by Iranian strikes and sharply reduced energy exports.
IMF research released on Tuesday showed that sharp spikes in food and energy prices are an increasingly common source of crises that drive inflation expectations higher for longer, worsen poverty and threaten economic stability.
One huge headache for policymakers is the growing public debt burden that is sapping growth and adding inflationary pressures. The IMF says public debt is at the highest level since World War II and will exceed 100% of GDP before 2030.
Advanced economies, led by the U.S., have the highest debt-to-GDP ratios, but emerging markets and low-income countries are particularly vulnerable, given a perfect storm of challenges: capital outflows in search of higher U.S. rates, El Nino and lack of investment in AI, which has mitigated negative supply shocks in the U.S. and other rich countries.
Emerging market concerns
Developing countries are particularly vulnerable given high public debt levels that will have to be renegotiated at higher interest rates.
Interest payments already exceed 10% of revenue in developing countries on average.
Early in the COVID-19 crisis, G-20 leaders announced a suspension of debt service payments for the poorest countries, but there is little appetite for such action now, according to diplomats from G-20 countries, who said high debt levels and political pressures posed bigger hurdles this time.
Many lower-income countries are worried about new IMF recommendations for loan programs that call for fewer, but deeper reforms as a condition for approving lending, a change that many fear will lead to painful austerity measures.
“Countries are already cutting their expenditures because their debt payments are going high and because of the IMF conditionality,” said Iolanda Fresnillo, who works on debt justice for Eurodad.
“We fear that this review of conditionality policy is just going to make things worse.”
Kenya, she said, had avoided a debt restructuring by cutting public expenditures and trying to raise taxes, but the changes sparked significant protests, especially among young people.
The IMF risked losing credibility unless it acknowledged the severity of the crisis facing many developing countries.
“As long as they continue with the governance structure that they have, they are becoming less and less relevant,” she said.
Flight routes to Bangkok often route through the Middle East, posing immediate security challenges to the 10,000-plus travelers descending on Thailand’s bustling capital city of 9 million residents following recent attacks on Saudi airports.


-
 Politics3 days ago
Türkiye rules out ops against Houthis, vows to help Saudi defense
-
 Economy3 days ago
Türkiye’s Kalyon PV to build solar panel factory in US
-
 Economy3 days ago
Türkiye identifies 214 people, firms made about $3.8B from troubled funds
-
 Politics3 days ago
Türkiye, France deepen military ties under new road map
-
 Economy3 days ago
Türkiye extends high-speed rail network to EU border
-
 Politics3 days ago
Türkiye’s Akıncı drones extend gendarmerie’s reach across country
-
 Economy3 days ago
European firms called to expand partnerships with Turkish contractors
-
 Politics3 days ago
Türkiye cooperates with EU for foreign nationals in need