Economy
Factories across world struggle in Sept. as demand remains muted

Factory activity contracted in much of the world last month, according to surveys released on Wednesday, as signs of a slowdown in U.S. growth and the expected impact of U.S. President Donald Trump’s sweeping tariffs added to pressure from weak Chinese demand.
Eurozone manufacturing slipped back into contraction as new orders fell at their fastest rate in six months, with export markets acting as a particular drag, signalling that the recovery in the region’s industrial sector was fragile.
The HCOB Eurozone Manufacturing Purchasing Managers’ Index (PMI), compiled by S&P Global, fell to 49.8 in September from August’s 50.7, which was the first reading above the 50.0-point line denoting growth since mid-2022.
“The drop in the PMI is showing up across the board, with respective figures for consumer goods, capital goods and intermediate goods all down on the month,” said Cyrus de la Rubia, chief economist at Hamburg Commercial Bank.
Surveys revealed a split across the currency union, with the Netherlands leading the expansion, as activity reached a 38-month high, while growth continued in Greece, Ireland and Spain. Meanwhile, the bloc’s three largest economies – Germany, France and Italy – all registered contractions.
In Britain, outside the European Union, activity shrank at the fastest pace in five months, reflecting subdued domestic demand and fewer export orders, painting a more downbeat picture than recent official data.
In Asia, the stress on manufacturers highlights the challenge policymakers face in protecting their export-reliant region from higher U.S. levies, a key policy of the Trump administration that has upended the global trade order and put the brakes on economic growth.
Export powerhouse Japan and global tech hub Taiwan saw manufacturing activity shrink in September, according to the surveys, leaving businesses in Asia – heavily dependent on the U.S. market – on a fragile footing.
Worryingly, China, a key engine of the global economy, also remained in the doldrums. An official survey released on Monday showed that manufacturing activity in the world’s second-largest economy contracted for a sixth consecutive month in September, dragged down by weak consumption and the squeeze from U.S. tariffs.
The prolonged slump underlines the twin pressures on China’s economy: Domestic demand has failed to mount a durable recovery in the years since the COVID-19 pandemic, while Trump’s tariffs have squeezed Chinese factories as well as overseas firms that buy components.
“The September PMI readings for most countries in Asia remained weak, and we continue to expect manufacturing activity in the region to struggle in the near term,” said Shivaan Tandon, emerging markets economist at Capital Economics.
“With growth set to soften and inflation likely to remain contained, we expect central banks in Asia to loosen policy further.”
The S&P Global Japan Manufacturing PMI fell to 48.5 in September from 49.7 in August, staying below the 50.0 threshold. It shrank at the fastest pace in six months due to steep falls in output and new orders, the survey showed.
Taiwan’s manufacturing PMI fell to 46.8 last month. Factory activity also shrank in the Philippines and Malaysia, the private surveys showed.
By contrast, South Korea’s factory activity expanded for the first time in eight months, underpinned by improving overseas demand. The manufacturing PMI in Asia’s fourth-largest economy, released by S&P Global, rose to 50.7 in September, moving above the 50-mark for the first time since January 2025.
The outlook for South Korea’s exporters, however, hinges on negotiations to formalize a July deal aimed at reducing U.S. tariffs on Korean goods imports, including automobiles, to 15% from 25% in return for South Korea’s investment of $350 billion in the U.S. The talks have stalled due to Seoul’s concerns over foreign exchange implications.
India’s manufacturing sector expansion lost some momentum and slipped to its weakest pace in four months, suggesting Washington’s punitive 50% tariffs on its goods could be starting to hurt Asia’s third-largest economy.
India targets increasing its steel capacity to 604 million metric tons by 2047 from around 220 million tons at present, according a draft steel policy for public consultation released late on Saturday.
Reuters reported last week, citing the draft document, that the policy lays out plans to cut sector emissions and shore up access to iron ore and coking coal, key raw materials, to meet anticipated demand.
The policy aims to cut the sector’s average carbon-emission intensity to around 1.54 tons of carbon dioxide per ton of crude steel by 2047 from the current 2.54 tons, in line with India’s net zero emission goal for 2070, according to the draft document.
The steel ministry expects iron ore demand at 772 million tons and plans to secure access to high-grade reserves by pursuing foreign assets and joint ventures, the document said.
The ministry also expects coking coal demand to reach 236 million tons, the document said, with the government planning to diversify its sourcing via “strategic global outreach” and acquire overseas assets.
Türkiye generated nearly $823 million from vegetable exports from January through September, up 10% from a year earlier, according to a report on Saturday.
Some 651,087 tons of tomatoes, peppers, cucumbers, zucchini, and other vegetables grown in Türkiye found buyers in international markets, according to information compiled by Anadolu Agency (AA) from data provided by the Türkiye Exporters Assembly (TIM).
Fresh vegetable export revenues, which amounted to some $749.15 million between January and September last year, increased by 10% during the same period this year, reaching $822.68 million.
Tomatoes ranked first among fresh vegetable exports, generating $304.16 million in revenue. Peppers followed, bringing in $275.48 million in export earnings.
Compared with the same period last year, revenue from tomato exports increased by 4%, while revenue from pepper exports rose by 29%. Together, these two products accounted for approximately 70% of total fresh vegetable export revenues.
During this period, Türkiye earned $61.38 million from cucumber and gherkin exports, $57.44 million from zucchini exports, and $39.64 million from carrot and radish exports.
Romania largest export market
Romania ranked first among Türkiye’s fresh vegetable export markets, purchasing products worth approximately $147 million.
Germany followed with $132.7 million, while Russia ranked third with $76 million.
During the same period, Türkiye exported fresh vegetables worth $55.48 million to Bulgaria, $49.96 million to Ukraine, and $47.8 million to the Netherlands.
Hayrettin Uçak, the chair of the Turkish Fresh Fruit and Vegetable Exporters’ Associations Sector Board, told Anadolu Agency (AA) that they viewed the increase in export revenues positively, despite changing conditions throughout the vegetable production season.
“Our exports increased by 10% over the previous year during the first nine months, and this success in exports makes us happy,” Uçak said.
“Neighboring and nearby markets are important for our vegetable exports. We need to closely monitor consumer expectations and shopping habits in the European market. Being able to supply buyers with the products they want, in suitable packaging and on time, plays a decisive role in commercial relationships. In this respect, we consider the growth in exports to Romania and Germany particularly important,” he added.
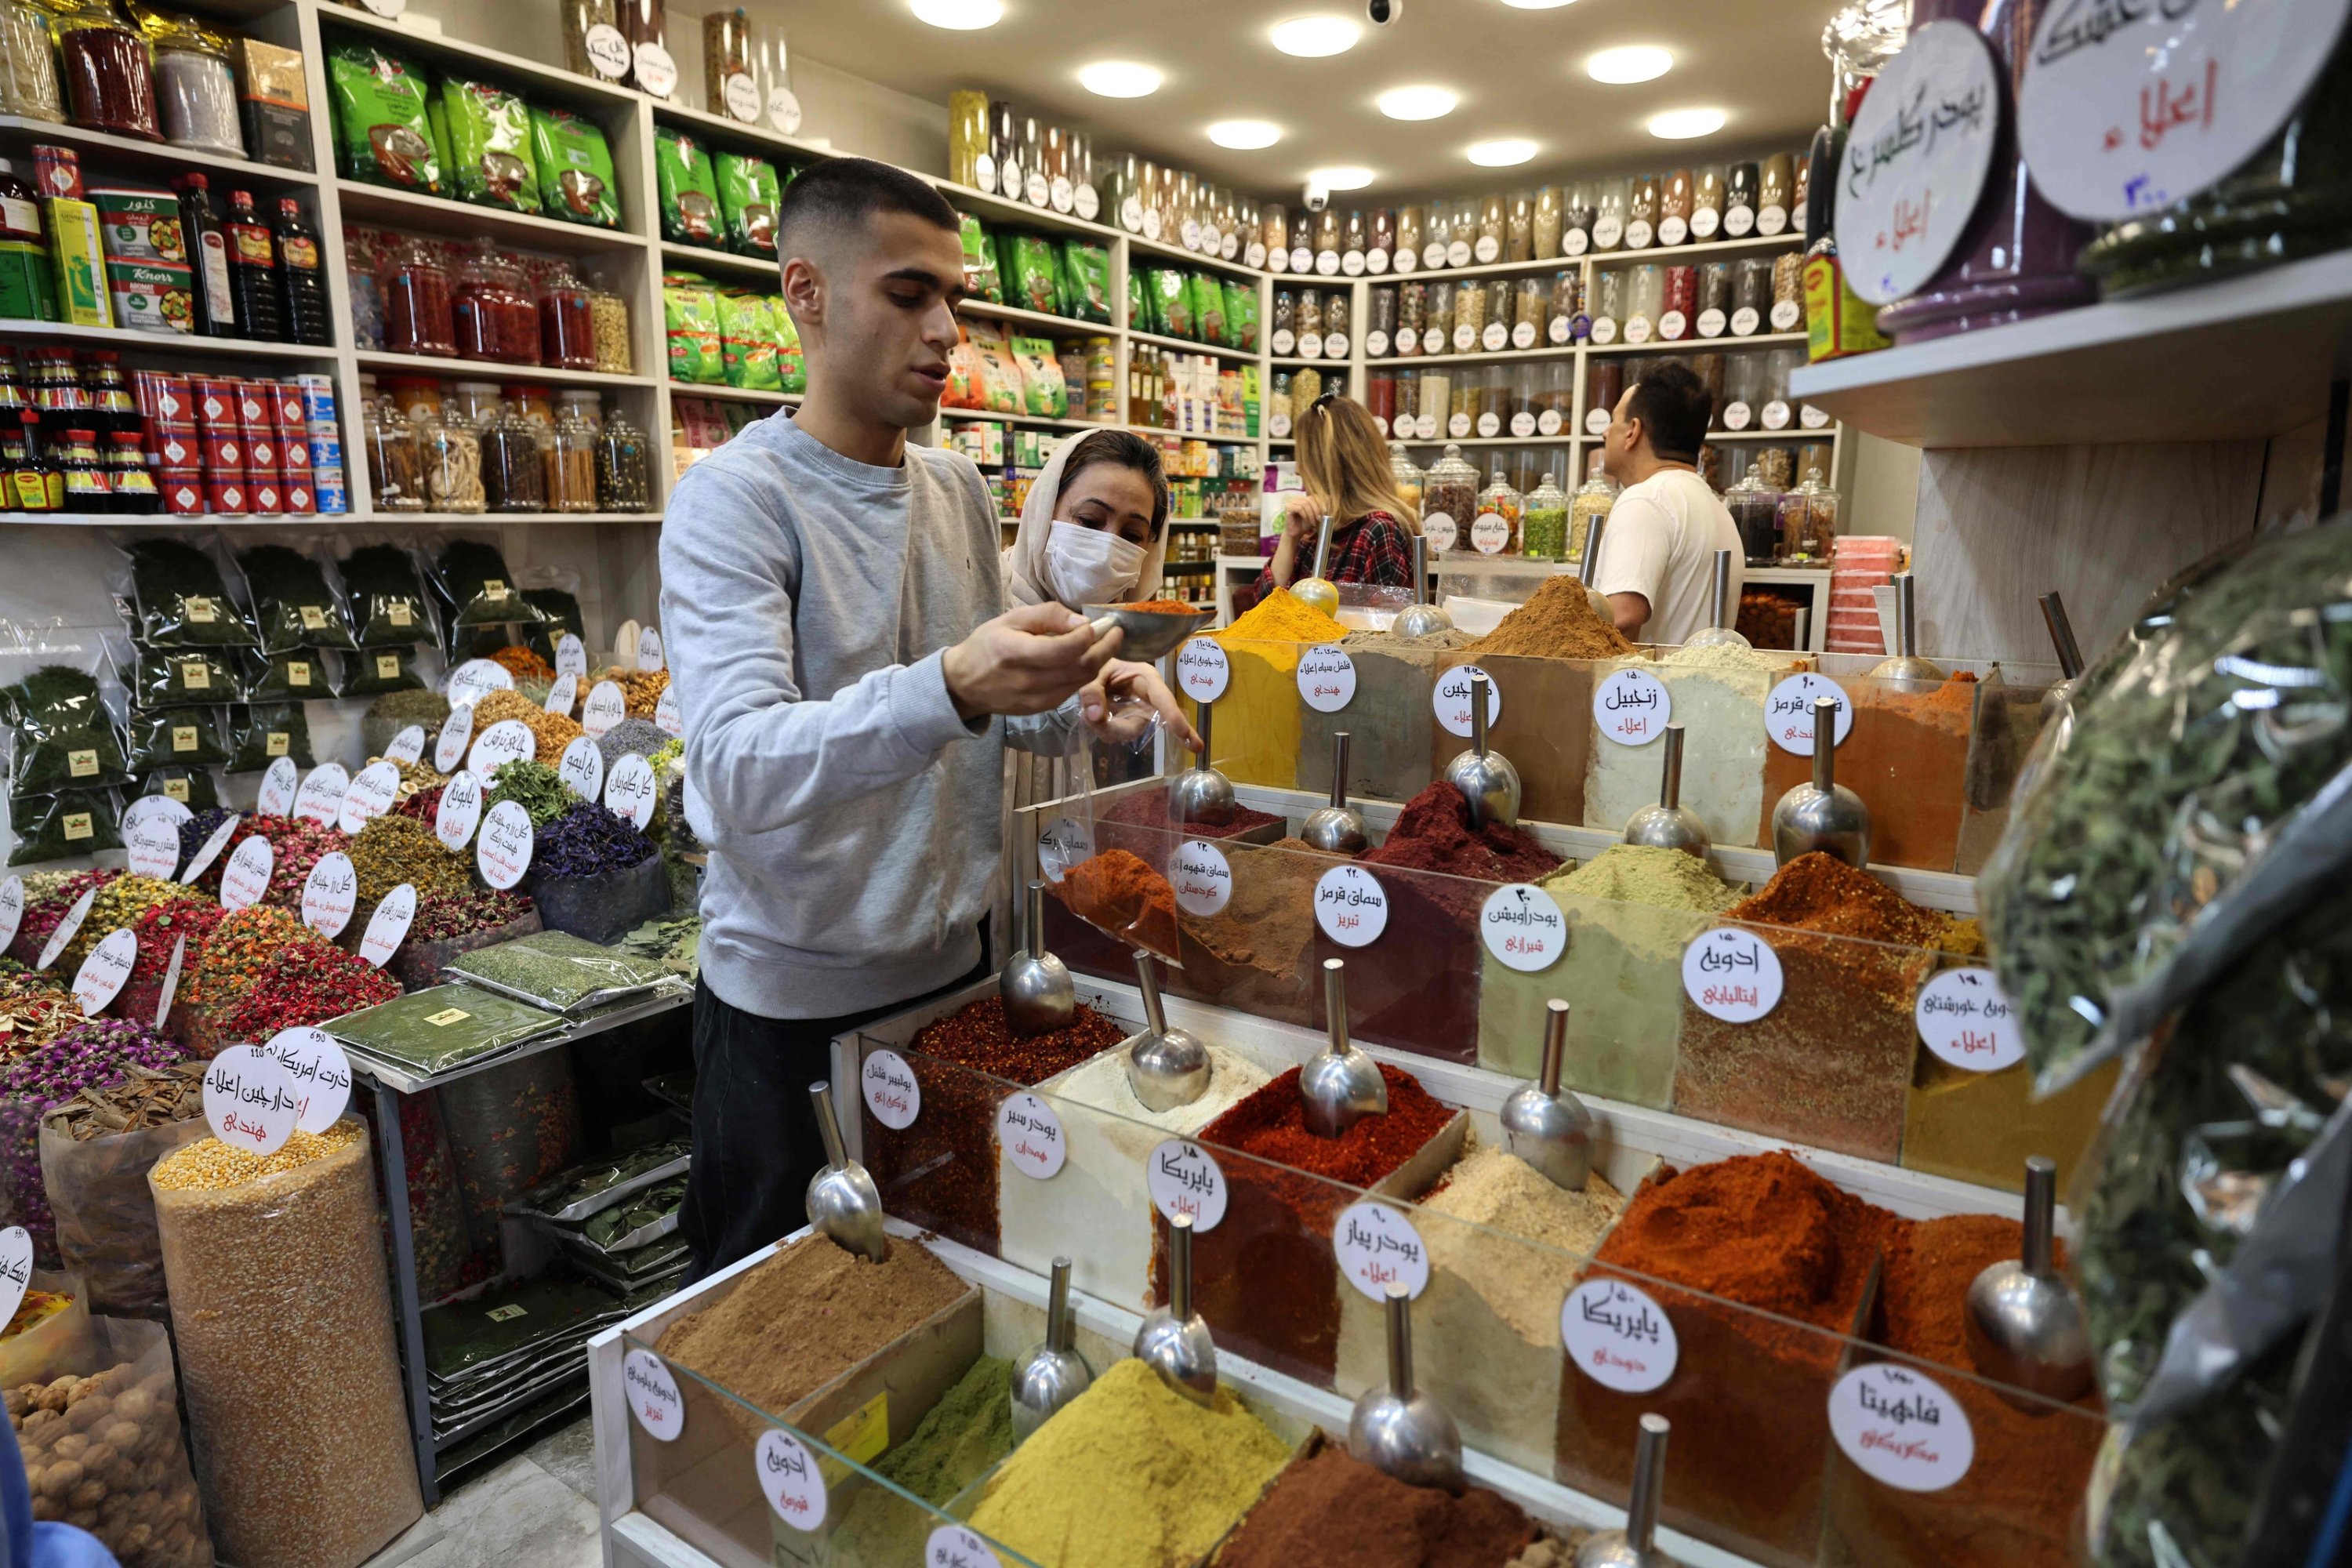
The scent of fragrant herbs and spices drifts through Tehran’s bazaar, but business is far from brisk. Shopkeeper Nasir says locals who once purchased nuts by the kilo are buying less as the U.S.-Iran war-driven price increases squeeze demand and push traders to the brink.
The marketplace in the Iranian capital’s north would usually be abuzz with customers, but shops now sit mostly empty with only small numbers of people walking its old narrow paths, a jarring shift for the sellers shouting to promote their goods.
“There used to be customers who bought 2 to 5 kilograms. Now, they’re down to buying one kilogram or half a kilogram,” said the 61-year-old.
“Prices are truly high. We all know it, and it would be a lie to say otherwise.”
Nasir called on authorities to stabilize the currency so businesses could plan ahead.
“We’re left in limbo; everyone is,” said the fruit and nut seller.
“They need to stabilize the dollar exchange rate.”
Iran’s economy has been battered by years of sanctions, but the conflict that began in February with U.S.-Israeli attacks and an American blockade of the country’s ports has put extra strain on daily life.
Rising inflation, nearly 90% year-over-year in September according to official figures, and erratic currency exchange fluctuations have driven up the cost of everyday items. Food prices have more than doubled since last year.
At the bazaar, a historic covered market in Tehran’s Tajrish square, locals surrounded by Iranian flags and Persian signage try to escape the economic gloom, scanning sweets, jewellery, traditional garments and cuts of meat before their weekend begins.
In an alley, a street artist plays a guitar while another drums his hands on a box to draw tips from passersby.
‘Just need stability’
But across the commercial district, many struggle to see a future for their businesses.
“It is a desperate, last-ditch struggle. Manufacturers are going bankrupt, laying off staff and closing shops, and the impact inevitably reaches us,” said Ali Nowruzi, 36, who runs a sportswear shop in the bazaar.
The businessman now orders only a few items for display on his shop’s shelves to stop them from looking bare like his warehouse, which he says lies empty due to lack of demand.
“We have absolutely no plan for the future. When people don’t come to buy … it effectively spells bankruptcy for the business,” he said, citing rising rent and utility bills.
“We just need some stability.”
Many shoppers, whose purchasing power has weakened since the outbreak of war, are seen leaving the bazaar without buying anything.
Azadeh, a 45-year-old woman currently out of work, says she just goes there to “watch the shops”.
Mounting pressure over the war saw Iran’s gross domestic product (GDP) contract 10.1% year-over-year between late March and late June, according to official figures.
The rial traded at around 2.7 million to the dollar on the unofficial market in the past week, compared with about 1.7 million before the war.
The minimum monthly wage that stood at around $120 a year ago has fallen to $65.
The country’s economy minister has rejected predictions of an imminent economic collapse, accusing Iran’s foes of trying to fuel public anxiety and drive up exchange rates.
Prices ‘skyrocketed’
Azadeh offers a price comparison of a kitchen cloth bought several months ago for 22 cents. She says that the item now costs $1.10, five times more.
“It shows that prices haven’t just gone up; they’ve truly skyrocketed,” she said.
She has stopped buying some fruits and says she can no longer afford holidays.
“We aren’t meant to just exist, we’re meant to actually live, right?” she asked.
Car mechanic Mojtaba Rezaei says his customers have “dropped to a 10th of what it was” because “goods now cost two or three times as much.”
“I actually feel embarrassed telling prices to customers. People just come in, ask the price, and leave,” the 57-year-old told Agence France-Presse (AFP) at the bazaar.
“So many things – buying clothes, going out for leisure, dining at restaurants – have all been cut out of our lives.”
Global finance leaders will meet in Thailand this week as the widening Middle East war, a historic energy supply shock and higher interest rates threaten to weigh further on already lackluster global economic growth.
The U.S.-Israeli-led war with Iran, now in its eighth month, and the inflation and hardship it has caused, will dominate the agenda and sideline conversations during the annual meetings of the International Monetary Fund (IMF) and World Bank, being held outside of Washington for the first time in three years.
Notably absent will be U.S. Treasury Secretary Scott Bessent, who dispatched two senior officials in his stead while he handled some “domestic engagements,” a U.S. official said.
His decision to skip the high-profile gathering and a meeting of the G-20 major economies, which the U.S. leads this year, may frustrate counterparts amid rising tensions over the Iran war, Ukraine’s battle with Russia and the U.S. move to impose sanctions on the International Criminal Court (ICC).
World Bank President Ajay Banga told Reuters that while global growth had held up better than feared when Iran closed the Strait of Hormuz, shutting off some 20% of the world’s oil, pressures were building again.
Soaring prices for diesel, rising fertilizer prices and a looming “super” El Nino weather effect that experts say could lead to 450,000 heat-related deaths are all hitting at once.
G-7 countries have agreed to release 100 million barrels of diesel and crude oil from emergency reserves under pressure from U.S. President Donald Trump, who is keen to see lower gasoline prices before the November elections that could see his Republican Party lose control of Congress.
Trump on Friday announced a deal with Russia that would provide even more diesel to global markets and a temporary waiver of U.S. sanctions designed to deprive Moscow of revenues for its war on Ukraine. The move drew swift criticism from Ukrainian President Volodymyr Zelenskyy.
More than 1 billion barrels of oil have been released mainly from onshore commercial inventories since the start of the war on Feb. 28, but industry executives say the amount of oil in storage that is accessible to the global market is running low, making the market more fragile and fueling pressure on prices.
Banga said the bank was not revising down its global forecasts at the moment, but was keeping a close eye on developments.
“The real thing is not just El Nino by itself; it’s the combination … What’s happening to fertilizer prices? What’s happening to energy costs? What’s happening to debt? It’s that put together that creates its own challenges,” he said.
“And I think that will call upon all of us to be far more careful on what we prepare for in the coming months.”
Rising debt
IMF Managing Director Kristalina Georgieva issued a similar warning in her traditional curtain raiser speech previewing the meetings, telling the audience, “Winter is coming.”
The IMF has signaled little change in its forecast for 3% global growth in 2026 and may edge its forecast for next year slightly higher.
But some countries will see downgrades, including Ukraine, now in its fifth year of war against Russia’s invasion, and Gulf countries hit by Iranian strikes and sharply reduced energy exports.
IMF research released on Tuesday showed that sharp spikes in food and energy prices are an increasingly common source of crises that drive inflation expectations higher for longer, worsen poverty and threaten economic stability.
One huge headache for policymakers is the growing public debt burden that is sapping growth and adding inflationary pressures. The IMF says public debt is at the highest level since World War II and will exceed 100% of GDP before 2030.
Advanced economies, led by the U.S., have the highest debt-to-GDP ratios, but emerging markets and low-income countries are particularly vulnerable, given a perfect storm of challenges: capital outflows in search of higher U.S. rates, El Nino and lack of investment in AI, which has mitigated negative supply shocks in the U.S. and other rich countries.
Emerging market concerns
Developing countries are particularly vulnerable given high public debt levels that will have to be renegotiated at higher interest rates.
Interest payments already exceed 10% of revenue in developing countries on average.
Early in the COVID-19 crisis, G-20 leaders announced a suspension of debt service payments for the poorest countries, but there is little appetite for such action now, according to diplomats from G-20 countries, who said high debt levels and political pressures posed bigger hurdles this time.
Many lower-income countries are worried about new IMF recommendations for loan programs that call for fewer, but deeper reforms as a condition for approving lending, a change that many fear will lead to painful austerity measures.
“Countries are already cutting their expenditures because their debt payments are going high and because of the IMF conditionality,” said Iolanda Fresnillo, who works on debt justice for Eurodad.
“We fear that this review of conditionality policy is just going to make things worse.”
Kenya, she said, had avoided a debt restructuring by cutting public expenditures and trying to raise taxes, but the changes sparked significant protests, especially among young people.
The IMF risked losing credibility unless it acknowledged the severity of the crisis facing many developing countries.
“As long as they continue with the governance structure that they have, they are becoming less and less relevant,” she said.
Flight routes to Bangkok often route through the Middle East, posing immediate security challenges to the 10,000-plus travelers descending on Thailand’s bustling capital city of 9 million residents following recent attacks on Saudi airports.
Turkish contractors have undertaken 12,900 projects worth $570 billion across 139 countries, Trade Minister Ömer Bolat said Friday, inviting European companies to expand their partnerships with Turkish firms.
Speaking at the European International Contractors (EIC) General Assembly in Istanbul, Bolat said the portfolio included completed and ongoing projects, with $520 billion of the total achieved over the past 23 years.
The sector began its overseas operations in Libya in 1972. Bolat said the Turkish companies have since completed more than 3,100 international technical consultancy projects worth $3.5 billion.
Forty-nine Turkish companies featured in Engineering News-Record’s 2025 ranking of the world’s top 250 international contractors, placing Türkiye second behind China, which had 71 firms.
Europe accounted for 40% of overseas contracts secured by Turkish contractors in 2025, Bolat said, citing projects in Spain, Portugal, the Netherlands, Poland and Romania.
He said the growing need to renew social housing, infrastructure, transport networks and buildings across Europe offered significant opportunities for cooperation.
“As Turkish contracting companies, we are ready to work with you and enter into partnerships,” Bolat said.
He also invited European businesses to invest in Türkiye, saying the country hosted 89,000 foreign-invested companies, 63% of them European.
“If you are not in Türkiye, you are not too late. We invite you to Türkiye,” he said.
Bolat said Türkiye has invested more than $300 billion in infrastructure over the past 23 years, expanding its ports, airports, roads, railways and logistics networks.
Amid regional wars, protectionism and supply chain disruptions, resilience has become as important as efficiency, he said.
Türkiye aims to become a center for production, trade, logistics, investment and connectivity, Bolat added.
Turkish prosecutors have identified 214 individuals and companies they say made a combined TL 187.65 billion ($3.8 billion) from three of the investment funds at the center of the country’s fund turmoil, according to a report Friday.
Authorities are now seeking to recover what they describe as unjust gains and return money to affected investors, the Sabah newspaper said.
Justice Minister Akın Gürlek told Sabah that the Istanbul Chief Public Prosecutor’s Office had passed the names to the Savings Deposit Insurance Fund (TMSF).
The TMSF has started notifying those on the list formally that the money must be returned. The recovered funds will be collected in accounts set up for investors who suffered losses.
Who made gains
According to the investigation file, the list includes 141 individuals and 73 companies. The individuals are reported to have each made more than TL 100 million, for a total of about 100.68 billion. The companies made almost TL 86.98 billion in total.
The gains came from funds managed by Tera, Pusula and Hedef Portföy, three of the seven management companies whose funds are being liquidated.
Tera funds generated approximately TL 28 billion in gains for 102 individuals and TL 62.1 billion for 38 companies, the report said.
Pusula funds yielded around TL 69.7 billion for 19 individuals and approximately TL 10 billion for 20 companies. Hedef Portföy funds generated nearly TL 3 billion for 20 individuals and TL 14.9 billion for 15 companies.
Focus on mid-September withdrawals
Authorities launched a sweeping investigation and market intervention last month after suspected price manipulation in a number of thinly traded stocks triggered heavy losses and redemption pressures at investment funds.
The Capital Markets Board (SPK) halted trading in more than 130 funds on Sept. 17. Nearly half a million investors have been affected.
Gürlek said investigators were looking especially closely at people who sold fund holdings and withdrew their money on Sept. 13, 14, 15 and 16.
Prosecutors’ examination found that these people withdrew in advance, acting on information given to them. Gürlek said the investigation was being widened in light of these findings.
Payments underway
Separately, Treasury and Finance Minister Mehmet Şimşek said on Thursday that 17 funds open to trading on the TEFAS electronic fund platform had been liquidated and that the money owed to about 43,000 fund investors had been deposited in the relevant banks.
Şimşek said comprehensive regulations were being introduced to prevent a repeat, and that further measures would be taken beyond the existing rules.
Meanwhile, the ruling Justice and Development Party (AK Party) was due Friday to submit draft legislation governing the liquidation of the funds.
The proposed temporary law aims to establish a legal framework for the liquidations, prioritize the protection of small investors and set rules for payments.
Under the proposal, authorities would adjust amounts invested in and withdrawn from the funds for inflation, with interim payments of up to TL 1 million per investor targeted for October.
The bill would also include provisions for recovering losses from those held responsible and establish a legal basis for extraordinary liquidation proceedings.
Real estate is among the assets that could be sold to raise funds for investor payments, with the legislation setting out how such assets would be liquidated and the proceeds distributed.


-
 Economy3 days ago
Trump says anyone who doesn’t call AI ‘super intelligence’ is ‘enemy’
-
 Politics3 days ago
Turkish, Greek Cypriot leaders to hold new round of talks Oct. 13
-
 Economy2 days ago
Türkiye identifies 214 people, firms made about $3.8B from troubled funds
-
 Politics2 days ago
Türkiye rules out ops against Houthis, vows to help Saudi defense
-
 Politics2 days ago
Turkish intelligence chief discusses SDF integration with Syrian FM
-
 Economy3 days ago
Drone hits data center of Russia’s ‘Google’ in 1st for Ukraine war
-
 Economy2 days ago
Türkiye’s Kalyon PV to build solar panel factory in US
-
 Politics2 days ago
Türkiye, France deepen military ties under new road map